

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EV Pantograph Market Hits $485.5M in 2025, Surging to $805.47M by 2032

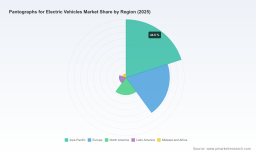
Strategic Intelligence for the Worldwide Pantographs for Electric Vehicles Market: Navigating the 2026–2032 Outlook
The worldwide pantographs for electric vehicles market is undergoing a structural transformation that demands immediate strategic attention from infrastructure developers, automotive OEMs, public transit authorities, and energy service providers. As urban electrification accelerates and zero-emission mobility mandates tighten, pantograph-based charging and power collection systems have evolved from niche electrification components into critical enablers of commercial fleet readiness and public transport modernization. Our latest market research publication delivers a comprehensive, data-backed assessment of this sector, framed to equip executive teams with the analytical clarity required to align capital allocation, partnership strategies, and product roadmaps throughout the 2026–2032 forecast horizon.
Market Trajectory and Core Forecast Signals
The sector has demonstrated consistent expansion across the historical window, with total revenue advancing from approximately 339.22 million USD in 2020 to an estimated 485.5 million USD in 2025. This progression reflects sustained commercial-vehicle electrification momentum, infrastructure modernization programs in leading metropolitan corridors, and accelerating adoption of high-power opportunity charging architectures for heavy-duty electric buses and tram networks. Looking forward, the market is projected to reach 523.68 million USD in 2026, with continued growth steering the sector toward 805.47 million USD by 2032.
At the core of this trajectory lies a forecast compound annual growth rate of 7.5 percent across the full assessment window. This growth profile signals more than incremental volume expansion; it indicates an ecosystem-wide shift in how cities and fleet operators approach electric commercial mobility. The rate underscores the compounding impact of regulatory pressure, operational efficiency imperatives, and the maturation of charging hardware compatible with high-load transit cycles. However, despite the clarity of the aggregate direction, the strategic value of this research lies in its ability to translate these headline numbers into actionable intelligence. Understanding where demand concentrates, which product configurations gain traction, and how value migrates across supply chains requires a level of segmentation detail that only the full report provides.
Why This Research Matters for 2026 Decision-Making
For strategy leaders operating in the electric mobility infrastructure space, 2026 represents a pivotal inflection point. Capital programs initiated today must account for hardware durability, compatibility with high-power transfer architectures, compliance with evolving regional standards, and cost structures influenced by both raw material volatility and specialized installation requirements. Pantograph systems sit at the intersection of mechanical engineering, high-voltage energy transfer, and urban transport planning, meaning that decisions made now will shape competitive positioning for the remainder of the decade.
This research is designed to reduce uncertainty in that planning process. Rather than stopping at top-line forecasts, the study dissects the operational and commercial variables that determine real-world deployment economics. It examines how product design choices influence installation complexity, how power-transfer capabilities align with fleet duty cycles, and how regional regulatory frameworks are shaping procurement criteria. The goal is to give decision-makers a structured framework for assessing risk, identifying white space, and evaluating whether to build, buy, partner, or localize components within their value chains.
What the Report Delivers
The full publication is organized to support both strategic planning and tactical execution. It integrates historical performance data with forward-looking analysis, enabling readers to benchmark current portfolios against market trajectories and anticipate demand shifts before they are fully priced into supply contracts. The report also includes a detailed examination of the factors reshaping cost dynamics across the pantograph ecosystem, including material pricing volatility, specialized labor constraints, and the impact of design innovations on deployment speed and system performance.
Readers will also find an in-depth exploration of the operational requirements that distinguish pantograph deployments from conventional charging infrastructure. Because these systems serve heavy-duty commercial fleets and rail-based transit applications, the analysis addresses compatibility considerations, safety standards, environmental protection expectations, and the practical realities of integrating roof-mounted or inverted configurations into existing vehicle platforms. The report evaluates how these constraints are driving product differentiation, influencing procurement specifications, and altering the cost-benefit equation for fleet operators comparing pantograph-based opportunity charging with alternative energy transfer models.
Additionally, the research maps the evolving technology landscape, including engineering advances that are reducing system weight, improving deployment speeds, and expanding the range of viable operating conditions. These innovations matter because they directly affect uptime, service frequency, and total cost of ownership for commercial electric fleets. By capturing how design evolution intersects with performance requirements and procurement priorities, the report provides a narrative that goes far beyond volume projections.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment, with the top three firms accounting for approximately 55 percent of market value and the top five collectively representing about 72 percent. This concentration reflects the specialized engineering requirements of pantograph systems, the importance of certification and reliability records, and the role of long-term infrastructure partnerships in securing recurring deployment opportunities. It also means that late entrants or smaller players must navigate meaningful barriers if they aim to compete on integration capability, technical performance, or procurement trust.
Several established players define the current competitive frontier. Schunk Group remains a leading provider of pantographs for electric bus charging and rail electrification, offering dynamic and static pantograph systems designed for overhead contact lines in EV infrastructure. ABB supplies pantograph-based charging solutions for electric buses and trucks, including its Pantograph Charging System integrated with high-power DC chargers. Siemens Mobility develops pantographs for electric road vehicles such as buses, with a focus on high-speed opportunity charging and systems compatible up to 1 MW power transfer. Alstom provides pantographs for electric buses and trolleybuses, extending its APS system capabilities into overhead pantograph charging applications. Heliox offers pantograph charging technology for electric buses, including automated roof-mounted pantographs suited to megawatt-level fast charging. Setec Power manufactures dynamic pantographs for electric buses and commercial vehicles, with deployments tied to large-scale electric bus fleets in China. WEG supplies pantograph systems for electric bus charging, supporting overhead catenary charging within Latin American e-bus networks.
Worldwide Mobile Charging Robot for Electric Vehicle Market
Recent activity among these firms reinforces the pace of competitive escalation. In October 2025, ABB launched an upgraded Pantograph Charging System v2.0 for electric buses, introducing 1.5 MW capability and improved alignment sensors. In June 2025, Siemens Mobility deployed pantograph charging infrastructure for 50 electric buses across Hamburg’s public transport network. In March 2025, Schunk Group received IEC 61851 certification for its new generation of dynamic pantographs used in EV bus charging. In November 2024, Heliox signed a joint development agreement with VDL Bus for pantograph integration on next-generation electric coaches. These moves illustrate how product upgrades, regional deployments, certification milestones, and partnership structures are compounding into defensible competitive positions.
For customers and investors, the strategic question is not simply who leads today, but which capabilities will matter most in the next procurement cycle. The full report provides company-level analysis, including positioning narratives, product emphasis, deployment relevance, and the strategic implications of recent announcements. That level of detail is essential for benchmarking vendor options, anticipating partnership opportunities, and evaluating where the market is likely to reward differentiation.
Industry Dynamics Shaping the Next Cycle
Several structural forces are reshaping the operational environment for pantograph systems. On the supply side, raw material pricing continues to exert pressure on component economics. Copper prices for pantograph contact strips have risen sharply year over year amid supply constraints tied to mining disruptions, creating cost volatility that manufacturers and integrators must absorb or pass through. This dynamic is particularly relevant because contact-strip material quality affects conductivity, wear performance, and long-term maintenance requirements, making input-cost management a strategic concern rather than a simple procurement task.
Regulatory expectations are also becoming more explicit. In Europe, EU Regulation 2024/1680 mandates that pantograph systems used in e-bus charging comply with IP67 ingress protection and EN 50121-4 EMC standards. Such requirements elevate the importance of conformity testing, region-specific design adjustments, and documentation readiness. They also create a competitive advantage for suppliers with mature certification pathways and experienced integration teams.
Technology-driven performance gains are equally significant. Advances in carbon fiber reinforced polymers have reduced pantograph weight by roughly 25 percent compared with aluminum, enabling faster deployment speeds of up to 40 km/h. These changes influence vehicle packaging, cycle times, and operational flexibility, especially for high-frequency transit routes and opportunity charging scenarios where alignment precision and rapid engagement matter. Engineers and fleet planners are increasingly evaluating these improvements as part of the broader business case for pantograph-based electrification.
On the commercial implementation side, installation economics remain an important consideration. Average installation costs for pantograph infrastructure can be substantial in mature labor markets, where skilled labor rates and site preparation requirements drive project budgets higher. This reinforces the value of planning that accounts for total deployed cost rather than hardware price alone, particularly for operators expanding networks across multiple cities or jurisdictions.
Safety and scope limitations also define market boundaries. Pantographs for EVs are restricted to commercial vehicles over 3.5 tonnes, and passenger car use is prohibited under UN ECE R100 safety norms. This regulatory framing shapes the addressable market in practical terms, directing investment toward bus fleets, rail and tram systems, and light rail transit use cases rather than mass-market passenger car segments. Recognizing those boundaries early helps teams avoid misaligned roadmap assumptions and focus on the segments where pantograph value propositions are both viable and defensible.
Worldwide Pantographs for Electric Vehicles Market
Why the Full Report Is Essential for Execution
Aggregate figures and competitive narratives provide the starting point for strategy, but they do not replace the precision required for procurement planning, market entry decisions, or investor communication. The complete Worldwide Pantographs for Electric Vehicles Market study extends far beyond the summary view presented here. It delivers detailed segmentation insights, demand distribution patterns, application-level context, regional performance dynamics, and vendor-level intelligence that collectively enable organizations to translate market direction into operational plans.
For infrastructure developers, the report supports site-level economic modeling and technology selection. For component manufacturers and system integrators, it clarifies where product roadmaps should be concentrated and how certification and performance standards are influencing purchasing criteria. For fleet operators and transit authorities, it informs total-cost comparisons and deployment sequencing. For investors and strategy teams, it identifies where concentration, innovation, and regulatory alignment are likely to create durable advantages or expose vulnerability.
The strategic value of this analysis is that it bridges the gap between directional market growth and the granular decision-making that determines execution success. Organizations that rely only on top-line data risk underestimating segmentation opportunities, overstating addressable scope, or misjudging the speed at which compliance and cost pressures will reshape procurement behavior. The complete report is structured to mitigate those risks by providing the depth that planning teams require when they move from market awareness to action.
Conclusion: Positioning for the 2026–2032 Cycle
The worldwide pantographs for electric vehicles market is expanding along a clear growth path, but the most consequential strategic choices will be made in the details. Which product architectures align with high-power opportunity charging needs, how compliance requirements affect regional rollout speed, where material and installation costs reshape economics, and which competitors are strengthening moats through certification, partnerships, and deployment records all determine whether organizations capture value or merely follow the market.
This research is built to support those choices with analytical rigor and practical context. It translates historical performance and forecast direction into a framework for strategic planning across the 2026–2032 period, while leaving the most decision-critical segmentation and competitive intelligence to the full publication. For teams evaluating market entry, portfolio expansion, vendor selection, or long-term infrastructure investment, the complete report offers the level of depth required to move forward with confidence. To access the full market intelligence, detailed segmentation breakdowns, competitive profiles, and forward-looking deployment context, request the complete study and integrate its findings directly into your 2026 strategy process.
For detailed analysis of this topic, please visit the official page: Worldwide Pantographs for Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com