

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Mineral Fiber Ceiling Tiles Market to Expand at 5.1% CAGR (2026–2032), Reaching USD 7,871.15 Million by 2032
By pmarketresearch, 2026-06-29
Mineral Fiber Ceiling Tiles Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
PW Consulting today releases an executive industry brief accompanying its full Mineral Fiber Ceiling Tiles Market report (base year 2025). This preview synthesizes the structural trends, competitive dynamics, and actionable strategic priorities that will shape boardroom decisions through 2026 — and outlines why leading manufacturers, suppliers, and institutional buyers must recalibrate procurement, product and M&A playbooks now to capture durable value.
Mineral Fiber Ceiling Tiles Market
Why 2026 is a Strategic Inflection Point
Our market model shows the sector has experienced steady expansion through the 2020–2025 reference period, increasing from approximately USD 4.31 billion in 2020 to roughly USD 5.56 billion in 2025. The market is forecast to resume robust expansion across the 2026–2032 horizon, with a compound annual growth rate (CAGR) of 5.1% embedded in our base-case projection. By 2032 the market is expected to reach an elevated scale consistent with accelerating end‑market demand for acoustic, fire‑performance and sustainability‑oriented ceiling solutions.
Mineral Fiber Ceiling Tiles Market
That trajectory, however, masks material near‑term volatility driven by raw‑material inflation, regulatory tightening, and episodic price adjustments by major suppliers. These dynamics introduce both risk and opportunity: firms that proactively shore up supply chains, product differentiation, and price governance will translate market growth into margin expansion; others risk margin erosion and share loss.
Mineral Fiber Ceiling Tiles Market
Macro Drivers and Structural Dynamics
-
End‑use momentum: Demand is being supported by continued investment in commercial construction, targeted retrofit programs (acoustics, indoor air quality), and increased specification of ceiling systems that deliver thermal and acoustic comfort without compromising fire performance.
-
Regulatory tightening: Evolving standards on energy efficiency, indoor air quality and fire performance are reshaping technical specifications and procurement criteria. In particular, regional regulatory regimes have intensified certification requirements that directly affect product development, third‑party testing cadence, and time‑to‑market for reformulated offerings.
-
Input cost pressure and pricing actions: Minerals such as perlite, cellulose and certain mineral wools remain subject to price swings. Recent manufacturer notices and industry price alerts confirm a trend of supplier‑led price increases tied to raw‑material inflation — a structural cost risk that compels both immediate procurement hedges and longer‑term product redesigns to reduce material intensity.
-
Consolidation and competitive concentration: The market exhibits a measurable concentration among incumbent players, which creates a strategic environment where scale, distribution breadth, and specification relationships matter more than ever for national and project‑level wins.
-
Product innovation emphasis: Acoustic performance (including Class A grades), recycled content and lifecycle carbon footprints have become primary buyer filters, driving premiumization in defined subsegments.
What the Full Report Covers — Practical, Boardroom‑Ready Content
PW Consulting’s comprehensive report is designed as an operational playbook for executives preparing 2026 plans. Key deliverables include:
-
Market sizing and forecasting (2020–2032) with transparent modelling assumptions and scenario variants (base / upside / downside).
-
Demand‑side analysis by product architecture and end‑use drivers, with specification pathways for new build versus retrofit procurement.
-
Supply‑side mapping and capacity analysis, including plant footprint, recent expansions and capacity utilization indicators.
-
Input cost and price stack analytics, highlighting sensitivity to key minerals and fibre content, plus supplier price‑notice impacts on margins.
-
Regulatory matrix across major jurisdictions, with compliance timelines and recommended certification strategies.
-
Competitive intelligence dossiers and scorecards covering product portfolios, route‑to‑market, sustainability claims, and commercial strategies for the sector’s leading firms.
-
M&A and partnership heatmaps, with deal scenarios, target archetypes and integration playbooks focused on scale, technology or geographic fill.
-
Risk register and mitigation playbooks (procurement hedges, dual‑sourcing, product reformulation, contract clauses), plus a 100‑day operational action plan for rapid execution.
Note: The full report includes detailed spreadsheets, proprietary segmentation matrices and downloadable models. This public brief intentionally omits granular subsegment values to preserve the report’s strategic utility — full access is available via the PW Consulting portal.
Competitive Landscape — Who’s Moving and What It Means
The sector is anchored by a set of legacy manufacturers and specialist ceiling systems providers that collectively shape specification practices and pricing dynamics. Recent corporate actions illuminate near‑term competitive intent:
-
Armstrong World Industries: Continues to push the sustainability agenda with next‑gen product lines that prioritize recycled content and lower embodied carbon. Its recent launches underline a strategy to secure green specifications and maintain pricing power amid input inflation.
-
USG Corporation: Focused on broad commercial distribution and system compatibility, USG’s offerings aim to balance acoustic performance with cost efficiency for large projects and specifiers.
-
Saint‑Gobain: Pursuing capacity expansion in high‑growth corridors to shorten lead times and better serve institutional and commercial clients with localized manufacturing and tailored product mixes.
-
Knauf: Strategic investments in integrated facilities highlight a push to consolidate supply chains across insulation and ceiling systems — an approach that improves cost control and accelerates innovation cycles for mineral‑based offerings.
-
Rockfon and OWA Ceiling Systems: These specialized players are differentiating through acoustics and performance classes, introducing competitive products that target education, healthcare and other standards‑sensitive segments.
-
CertainTeed: Leveraging North American distribution channels and contractor relationships, the company focuses on specification velocity and project execution efficiencies.
Recent publicized moves — product launches emphasizing recycled content and acoustic Class A performance, strategic capacity buildouts in Europe and Asia, and coordinated price‑increase notices — collectively signal that incumbents are defending margins and pre‑positioning for higher‑specification demand. These maneuvers increase the value of scale, vertical integration and specification relationships.
Strategic Priorities for Leadership Teams in 2026
-
Procurement and Cost: Implement a short‑term hedging program for critical mineral inputs and renegotiate supply contracts to include indexation and shared‑inflation clauses. Simultaneously, accelerate material‑efficiency projects to reduce dependency on price‑volatile inputs.
-
Portfolio & R&D: Prioritize development of low‑carbon formulations and acoustic high‑performance lines. Certification readiness for energy and indoor‑air regulations should be a gated R&D milestone, not an afterthought.
-
Commercial: Reassess pricing architecture to capture value from differentiated products. Strengthen specification teams to convert architectural and institutional buyers, and deploy value‑based contracting where feasible.
-
Operations & Capacity Planning: Map capacity constraints against forecast scenarios and prepare contingency plans — e.g., temporary tolling agreements or regional contract manufacturing — to mitigate supplier bottlenecks.
-
M&A & Partnerships: Given the market’s concentration profile, consider bolt‑on acquisitions for geographic fill, specialty acoustics assets, or recycling capabilities that accelerate sustainability claims.
-
Risk & Compliance: Build an active regulatory watch and a rapid certification squad to respond to incremental standards in major markets, turning compliance into a commercial differentiator.
Final Takeaways — Translate Growth Into Sustainable Margin
The mineral fiber ceiling tiles market is not a simple volume play. Growth alone will not guarantee profitability in 2026. Companies that combine disciplined cost management, targeted product differentiation (particularly around acoustics and sustainability), and proactive regulatory positioning will outperform. The market’s structural concentration gives incumbents leverage, but it also raises the bar for challengers who must demonstrate clear technical or commercial differentiation to win specification share.
PW Consulting’s full report supplies the quantitative backbone and actionable templates executives need to operationalize these recommendations — including detailed scenario models, supplier heatmaps, and a 100‑day execution plan tailored for manufacturers, distributors and institutional buyers.
How to Access the Full Analysis
This release is a strategic preview. The full Mineral Fiber Ceiling Tiles Market report contains the proprietary subsegment breakdowns, downloadable financial models (USD Million basis), supplier scorecards, and implementation playbooks that boards and operating teams require to execute in 2026. Clients and interested executives are invited to visit the PW Consulting publications page to request the complete report and associated data packs.
For detailed analysis of this topic, please visit the official page: Mineral Fiber Ceiling Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Magnesium Sulfate Market Poised to Reach USD 1,548.74 Million by 2032
By pmarketresearch, 2026-06-29

Magnesium Sulfate Market Outlook 2026: Strategic Imperatives for Executive Decision-Making
PW Consulting’s latest Magnesium Sulfate Market study (base year 2025) positions procurement leaders, product strategists, and corporate development teams to make high-conviction decisions in 2026. The industry is on a sustained expansion path: our modeling shows a compound annual growth rate (CAGR) of 5.78% over the 2026–2032 forecast window, with the market valued at USD 1,030.0 Million in 2025 and projected to reach approximately USD 1,548.7 Million by 2032. These macro dynamics create windows for commercial advantage—but only for organizations that combine operational rigor with strategic foresight.
Magnesium Sulfate Market
Executive snapshot: Why the 2026 inflection matters
-
Volume-demand resilience: End-use demand from agriculture, pharmaceuticals, personal care and industrial applications continues to underpin growth, even as supply-side volatility injects episodic price and availability shocks.
Magnesium Sulfate Market -
Supply-side tightening: Elevated upstream input costs—particularly magnesia ore and sulfuric acid—together with environmental compliance-driven curtailments at select processing sites, are compressing regional availability and raising operating cost baselines.
Magnesium Sulfate Market -
Moderate market concentration: The sector displays mid-level concentration (CR3 ≈ 42%; CR5 ≈ 43%), which translates into meaningful but not dominant supplier influence—an optimal environment for differentiated players and well-structured procurement strategies.
What the PW Consulting report delivers (practical and actionable)
This study is designed as a decision-support toolkit for 2026 initiatives. We intentionally combine high-fidelity modeling with practitioner-ready templates so that commercial teams can move from insight to action within weeks, not months. Key deliverables include:
-
Demand and pricing model: A robust, bottom-up forecast engine calibrated to the 2020–2025 historical series and stressed across multiple macro scenarios to quantify exposure under alternative commodity-price and regulatory pathways.
-
Supply-mapping and risk heatmap: Facility-level intelligence, logistics chokepoints, and input-cost sensitivity analyses that identify single-source risks and regional bottlenecks—presented as prioritized mitigation options.
-
Commercial playbook: Contract archetypes, indexation clauses, and inventory strategies tailor-made for buyers and traders to preserve margin while ensuring continuity of supply in a tighter market.
-
Product and channel go-to-market templates: Value-mapping for specialty and high-purity grades, differentiated packaging and logistics solutions for industrial and pharmaceutical customers, and channel segmentation for distributors.
-
M&A and partnership framework: Target-screening criteria, accretion/dilution scenarios, and integration checklists focused on bolt-on production capacity, distribution reach, and feedstock security.
-
Sustainability and compliance roadmap: Practical guidance on emissions reduction levers, capex prioritization, and regulatory-compliance sequencing that reduce the risk of operational curtailments.
Note: The public summary intentionally omits granular region- and application-level tables found in the full report. Those segmented datasets and price curves are included in the subscriber deliverable and are essential for transaction-level decisions.
Supply dynamics and near-term headwinds
-
Input-cost pressure: Rising costs for magnesite ore and sulfuric acid are materially increasing unit production costs for regional manufacturers. Our sensitivity analyses indicate these feedstock pressures are the dominant driver of margin erosion in the near term.
-
Regulatory tightening: Environmental compliance requirements have precipitated localized production curtailments at several processing facilities. The effect is a geographically uneven tightening of supply that amplifies spot volatility and increases the value of secured contracts.
-
Inventory and logistics friction: Just-in-time procurement models face renewed scrutiny as lead times lengthen and working capital considerations collide with the need for resilience. Organizations that optimize safety stock with active supplier collaboration will secure a competitive edge.
Competitive landscape: strategic profiles and implications
The market is served by a mix of vertically integrated producers, regional specialists, and national distributors. Understanding each archetype’s strategic levers is essential for buyers, partners, and potential acquirers.
-
Giles Chemical (Waynesville, NC) : As a leading North American producer of heptahydrate and liquid solutions, Giles’ strengths lie in product breadth (crystal and liquid forms), established industrial and agricultural relationships, and manufacturing footprint. For corporates, Giles represents a benchmark for supply reliability in the region and a potential target for offtake or joint-venture arrangements where liquid formulations are strategic.
-
PQ Corporation (Malvern, PA) : PQ offers industrial and technical grades and competes on process expertise and product consistency. Their positioning makes them a preferred supplier for technical applications and specialty formulations—useful for firms seeking quality-differentiated inputs rather than commoditized sources.
-
K+S Aktiengesellschaft (Kassel, Germany) : K+S’ focus on high-purity anhydrous and specialized heptahydrate grades, combined with a public sustainability initiative to reduce carbon intensity, signals a premium strategy that aligns with high-value agriculture and industrial customers where traceability and emissions are prioritized.
-
Compass Minerals (Overland Park, KS) : With integrated plant-nutrient capabilities, Compass Minerals acts as both a product supplier and a channel partner for agriculture-focused customers. Their scale and downstream relationships make them a natural collaborator for fertilizer formulators and large distributors.
-
CoreChem, Connection Chemical, Univars Solutions : These distributors and logistics-focused players offer national stocking, packaging services, and flexible fulfillment solutions. For manufacturers and brands seeking cost-efficient distribution or near-market inventory, distributor partnerships are an essential component of go-to-market optimization.
Competitive takeaway: with a mid-level CR concentration, there is room for nimble suppliers to win share through service, specialty grades, and regional securement strategies. At the same time, larger players exert enough influence that strategic contracting and hedging are now table stakes.
Recent strategic moves and their signal value
-
Partnership activity: Nutrien’s strategic collaboration with an ag-tech firm (Aug 2025) to develop advanced magnesium sulfate fertilizers underscores the sector’s move toward product innovation and agronomic yield optimization. Buyers and ingredient suppliers should monitor such partnerships as early indicators of evolving specification demand.
-
Sustainability commitments: K+S’ sustainability initiative (Sep 2025) to lower production emissions is emblematic of a broader trend—customers increasingly value low-carbon inputs. This shifts investment priority toward energy- and emissions-efficient process upgrades and creates premium pricing potential for certified low-carbon materials.
Practical strategies for 2026 decision-makers
-
De-risk supply with layered contracts: Combine fixed-volume contracts with indexed flexible tranches and spot-purchase windows. This hybrid approach preserves price advantage while ensuring continuity during episodic shortfalls.
-
Prioritize feedstock visibility: Build upstream insight into magnesite and sulfuric acid supply—either through direct supplier partnerships, data subscriptions, or equity stakes—to anticipate cost pass-through and negotiate defensible pricing.
-
Invest selectively in differentiation: For manufacturers, prioritize grades where purity, particle form or certification (e.g., pharma, food-grade) command sustainable premiums and create barriers to fast-followers.
-
Hedge operational risk with geography-aware inventories: Where regional curtailments are likely, hold strategically placed safety inventory or multi-source agreements in different regulatory jurisdictions.
-
Align sustainability with commercial value: Quantify the payback of emissions-reduction investments not only by compliance risk mitigation but also via price-premium capture and customer retention.
-
Pursue bolt-on M&A and offtake partnerships: Look for targets that add feedstock security, logistics scale, or specialty grades rather than merely incremental volumes—those are the acquisitions most likely to accelerate margin expansion.
How PW Consulting helps you convert insight into outcomes
For 2026 planning cycles, PW Consulting provides a suite of advisory packages that convert the report’s analytics into executable plans:
-
Customized procurement playbooks and contract templates calibrated to your portfolio and exposure profile.
-
Supply-security audits with prioritized remediation roadmaps and supplier engagement playbooks.
-
Commercial diligence for M&A or JV activity, including accretion modeling and integration risk maps.
-
Sustainability cost-benefit analyses and design of phased decarbonization programs tied to regulatory timelines.
Each engagement is supported by the full dataset and modeling engine that underlie the report. The granular regional and application-level segmentation, supplier scorecards, and pricing curves are available in the subscriber deliverable and are essential for transactional and capital-allocation decisions.
Concluding perspective
The magnesium sulfate market is transitioning from a historically stable commodity space to a more dynamic landscape shaped by upstream feedstock pressures, regulatory tightening, and selective product innovation. Growth is robust at the macro level—supported by a 5.78% CAGR over 2026–2032—but the path to premium returns requires disciplined supply-risk management, targeted differentiation, and timely investments in sustainability. Organizations that move early to secure feedstock, rationalize supplier exposure, and align product portfolios with emerging quality and emissions demands will capture disproportionate value in 2026 and beyond.
To access the full report, detailed segment tables, and subscriber-only scenario models, visit the PW Consulting research portal. Our team is available to design a 6–8 week advisory engagement to convert the report’s insights into a 2026 execution plan tailored to your priorities.
For detailed analysis of this topic, please visit the official page: Magnesium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wireless Charging IC Market to Accelerate at 20.54% CAGR, Reaching USD 7,910 Million by 2032
By pmarketresearch, 2026-06-29

Wireless Charging IC Market 2026: Strategic Imperatives from PW Consulting
Executive snapshot
PW Consulting’s new Wireless Charging IC Market report — base year 2025, historical horizon 2020–2025, forecast period 2026–2032 — maps a high-growth trajectory that will reshape product roadmaps and sourcing strategies across consumer electronics, automotive, healthcare, and industrial sectors. The market has already more than doubled since 2020, rising from approximately USD 1,200 million in 2020 to about USD 2,150 million in 2025. Under our central scenario, the market accelerates in 2026 and beyond, with an expected compound annual growth rate (CAGR) of 20.54% over the 2026–2032 forecast window, driving the market toward a multi-billion-dollar opportunity by 2032.
Wireless Charging IC Market
Why this report matters to executives making decisions in 2026
- Timing and scale: The 20.54% CAGR in the forecast window demands that product, procurement, and partnership decisions made in 2026 account for both rapid demand expansion and concentrated supplier dynamics.
- Standards-driven interoperability: Emerging standards (Qi2 family, MPP, and NFC Forum WLC 2.0) are shaping integration choices and supplier selection; non-compliant architectures risk costly rework and slow time-to-market.
- Technology bifurcation: Ultra-compact, NFC-enabled receivers for wearables and high-power PMICs for automotive and consumer fast-charging are evolving along different development and qualification timelines—each requiring distinct sourcing and validation programs.
- M&A and partnership playbooks: A moderately concentrated market structure means strategic alliances, minority investments, or bolt-on acquisitions can materially alter competitive positioning within 12–24 months.
What executives will find actionable in the report
We designed the report as a practical decision-support toolkit for 2026 strategy cycles. Highlights include:
Wireless Charging IC Market
- Top-level market sizing and forward-looking scenarios calibrated to multiple adoption pathways, regulatory developments, and component-level cost curves.
- Go-to-market playbooks for OEMs and Tier-1 suppliers: vendor shortlists, qualification timelines, certification milestones, and sample supply strategies to compress commercialization lead times.
- Technology roadmaps that reconcile trade-offs across power class (ultra-low power wearables to 50 W+ systems), on-chip security/authentication, and multi-device magnetic power profiles.
- Value-chain and margin waterfall analysis to inform pricing strategies and captive vs. outsourced IC sourcing decisions.
- Competitive benchmarking and supplier scorecards that evaluate technical maturity, production readiness, standards compliance, IP exposure, and aftermarket support.
- Regulatory and interoperability tracker covering Qi2/MPP, NFC WLC 2.0, and other certification regimes that materially affect product launch risk.
- Scenario-based investment cases and M&A theses designed for corporate development teams looking to deploy capital with asymmetric upside.
Competitive landscape — what to watch in 2026
The wireless charging IC ecosystem in 2026 blends legacy semiconductor players with specialized power-management and RF-focused vendors. Market concentration remains meaningful: the top three vendors control approximately two-thirds of the market, and the top five approach three-quarters, creating both supplier risk and strategic opportunity for OEMs who need differentiated supply strategies.
Wireless Charging IC Market
- ROHM Semiconductor (Kyoto, Japan) — In April 2026 ROHM entered mass production of an ultra-compact NFC wireless power receiver/transmitter chipset aimed at ultra-small wearables (e.g., smart rings and pens). The ML7670/ML7671 family is notable for its footprint and NFC Forum WLC 2.0 compliance, signaling a clear path for NFC-based power in compact devices.
- Samsung Electronics (Suwon, South Korea) — Samsung’s S2MIW06 PMIC has completed extensive Qi pre-testing and targets up to 50 W transfer efficiencies. Samsung’s credibility in both silicon and system integration increases competitive pressure in high-power consumer and fast-charging categories.
- NXP Semiconductors (Eindhoven, Netherlands) — NXP’s transmitter/receiver MCU families bring on-chip authentication, MPP multi-device support, and explicit Qi2 compliance, aligning them closely with automotive and multi-device transmitter architectures.
- Texas Instruments , STMicroelectronics , Infineon , Renesas , Qualcomm , Analog Devices , Semtech , and ON Semiconductor — Each offers differentiated value propositions across power classes, integration depth, and manufacturing footprints, from compact 5 W receiver ICs to cost-effective 50 W transmitter solutions and wide-bandgap-enabled designs for higher-efficiency power stages.
Regulatory, standards, and interoperability dynamics
Standards activity is not academic — it is the primary determinant of architecture choices and component sourcing in 2026. Key developments shaping decisions include:
- Qi2 Magnetic Power Profile (MPP) requirements that embed magnetic alignment and authentication capabilities on-chip, favoring suppliers with strong firmware and security support.
- NFC Forum WLC 2.0 enabling NFC-based wireless power for ultra-compact wearables; suppliers with compliant silicon and firmware stacks (as demonstrated by recent product launches) gain early access to the wearables segment.
- Interoperability testing regimes and OEM pre-certification programs that shorten or lengthen time-to-market depending on supplier collaboration and design-for-certification practices.
Strategic implications for 2026 planning
Based on our analysis, we recommend four priority actions for companies with stake in wireless charging ICs:
- Segment your roadmap by power-class and standards dependency. Treat ultra-compact, NFC-enabled wearables and high-power consumer/automotive designs as separate product streams with tailored supplier qualification and firmware roadmaps.
- Adopt multi-sourcing and qualification buffers. Given the moderate market concentration, lock-step single-supplier strategies increase business continuity risk; dual-source critical ICs and pre-qualify alternatives during design freeze.
- Invest in on-chip security and authentication integration. Standards like Qi2/MPP make security a gating item; early alignment with suppliers that provide robust authentication primitives reduces retrofit cost and certification delay.
- Build partnerships for system-level differentiation. Winning in automotive and premium consumer segments will depend as much on software/firmware and thermal/mechanical integration as on raw silicon performance—pursue co-development for faster, lower-risk launches.
Use cases and go-to-market playbooks
We provide playbooks tailored to four go-to-market archetypes in the report: fast follower consumer OEMs, tier-1 automotive suppliers, medical-device OEMs with stringent verification requirements, and consumer-electronics innovators targeting form-factor innovation. Each playbook contains qualification milestones, recommended vendor shortlists, sample procurement calendars, and a risk-weighted NPI budget template to translate the report’s insights into executable plans.
Methodology and data integrity
Our market model synthesizes primary interviews with OEMs, Tier-1 suppliers, and semiconductor vendors, combined with bottom-up BOM and shipment analysis and scenario stress-testing against standardization and adoption drivers. The report’s nominal market values are stated in USD (Million), using 2025 as the base year for normalization. Historical coverage spans 2020–2025 and our forecast extends through 2032 under multiple adoption scenarios; the central forecast yields a 20.54% CAGR across 2026–2032.
Next steps — where to get the detailed intelligence
This release is intentionally high-level: it highlights strategic inflection points and vendor movements without disclosing the full, actionable segment-level tables that enterprise decision-making requires. The full report contains granular segmentation (by power class, application, and region), downloadable datasets, vendor scorecards with detailed criteria, patent landscaping, and a regulatory compliance calendar that practitioners can use to construct 12–36 month workplans.
- For licensing the full report, custom data extracts, or a tailored executive briefing for your leadership team, contact PW Consulting’s Market Intelligence desk.
- For product teams and procurement, request the supplier shortlists and the NPI qualification templates to accelerate 2026 launches.
Wireless charging ICs are no longer a niche add-on — they are a strategic component of future-connected devices. The decisions made in 2026 about vendors, standards alignment, and integration strategy will determine not just first-mover advantage but the ability to scale reliably as the market grows at an anticipated 20.54% CAGR through 2032. PW Consulting’s report provides the evidence base and playbooks to turn that growth into sustainable competitive advantage.
— PW Consulting, Senior Strategic Advisory & Industry Analysis Team
For detailed analysis of this topic, please visit the official page: Wireless Charging IC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Clinical Trial Market to Reach USD 149.6 Billion by 2032 on 7.7% CAGR as North America Commands 43.96% Share
By pmarketresearch, 2026-06-29

PW Consulting Releases 2026 Clinical Trial Market Report: Strategic Playbook for Sponsors, CROs and Investors
PW Consulting today publishes its definitive market study on the Clinical Trial Market, providing executives with the actionable intelligence they need to make high‑stakes decisions in 2026 and beyond. Built on a 2025 base year, five years of historical tracking (2020–2025) and an 2026–2032 forecast horizon, our model projects continued expansion at a 7.7% compound annual growth rate, with the global market rising from approximately USD 89.0 Billion in 2025 to an anticipated USD 149.6 Billion by 2032. This research brief summarizes the report’s strategic value, highlights immediate implications for market participants, and explains how the full deliverable equips leadership teams to convert insight into measurable competitive advantage.
Clinical Trial Market
Why 2026 is a Strategic Inflection Point
Several converging forces make 2026 a turning point for clinical-trial strategy. Regulatory frameworks are tightening and harmonizing—most notably regulatory updates that came into force in the UK and renewed enforcement activity around trial reporting in the United States—while leading regulators are piloting real‑time trials and AI‑enabled optimization initiatives. At the same time, market dynamics continue to evolve: industry‑sponsored activity remains a major economic engine for communities and health systems, and biopharmaceutical sponsors continue to run thousands of trials across therapeutic areas.
Clinical Trial Market
For organizations that rely on predictable development timelines and efficient patient recruitment, the implication is stark: the operational model that delivered value in 2022–2024 will not be sufficient. The winners in 2026 will be those that translate regulatory change, digital advances, and shifting competitive behaviors into redesigned trial architectures and sourcing strategies that reduce cycle time, lower attrition, and strengthen regulatory resilience.
Clinical Trial Market
Core Strategic Levers Identified in the Report
-
Portfolio Prioritization and Adaptive Design: The report provides an investment framework to prioritize pipeline assets that deliver the greatest strategic optionality under multiple regulatory and reimbursement scenarios. We include decision rules for adaptive designs that preserve statistical rigor while accelerating go/no‑go decisions.
-
Decentralized and Hybrid Trials: We assess operational trade‑offs for virtual site models, patient engagement platforms, and home‑visit logistics—showing how to balance recruitment velocity against data integrity risk and site relationships.
-
Data & Analytics as Differentiators: The study demonstrates how analytics—real‑time enrollment dashboards, synthetic control arms, and eSource integration—shave months from development timelines when deployed with governance and validation protocols aligned to regulators’ emerging guidance.
-
Vendor Strategy & Outsourcing Mix: Our vendor selection playbook articulates when to insource, when to partner with full‑service CROs, and when to buy modular capabilities—backed by tools for total cost of ownership and SLA‑driven performance forecasting.
-
Regulatory & Ethics Readiness: With recent regulatory steps on trial transparency and participant protection, the report maps compliance vectors and offers practical checklists to mitigate audit risk and disclosure penalties.
-
Site & Patient Network Optimization: We deliver a method for scoring site feasibility, estimating dropout risk, and structuring community partnerships to sustain recruitment in rare and specialty indications.
-
M&A and Strategic Partnerships: Given the market’s moderate concentration and continuing fragmentation in specialty services, the report defines acquisition archetypes and partnership blueprints that maximize capability uplift while controlling integration risk.
Competitive Landscape — Sponsors and Service Providers
The Clinical Trial Market remains a two‑handed ecosystem: global sponsors (large pharmaceutical and biotech companies) set strategic demand, while Contract Research Organizations (CROs), technology vendors and specialist service providers supply execution capabilities. Our competitive analysis profiles leading sponsors and service providers and distills the playbooks they are deploying to protect timelines and margins.
-
Large Sponsors: Industry leaders continue to run global Phase I–IV portfolios across oncology, rare diseases and chronic indications. These organizations are investing in integrated capabilities—real‑world evidence units, in‑house analytics, and direct patient engagement—to reduce dependency on outsourced timelines and to accelerate regulatory filings.
-
Full‑Service CROs and Data Leaders: Major service providers are competing on two fronts: scale and digital differentiation. Firms that combine trial management with advanced analytics and end‑to‑end data platforms are winning deals where speed and predictability are prerequisites. Our provider scorecards assess operational depth, therapeutic expertise, regional footprint and digital maturity for due‑diligence and procurement use.
-
Specialist and Niche Players: A robust ecosystem of specialists—ethics & regulatory consultancies, site management organizations, patient recruitment platforms, and quality/regulatory advisors—offers acquisition targets for sponsors seeking capability infill. The market’s current CR3 and CR5 metrics indicate moderate top‑end concentration, leaving room for specialists to capture incremental share through differentiation.
Executive teams will find in the report actionable profiles for each major industry actor—covering strategic intent, recent moves, capability gaps and potential partnership archetypes—enabling decision makers to sharpen procurement strategies, alliance roadmaps and M&A hypotheses.
Report Deliverables: What Practitioners Will Use Tomorrow
-
Proprietary market model (2020–2032) with scenario engines and sensitivity testing.
-
Vendor scorecards and procurement playbooks tied to measurable KPIs and pricing benchmarks.
-
Regulatory tracker and compliance playbooks updated to reflect 2026 regulatory actions and enforcement patterns.
-
Site feasibility index, patient engagement templates, and real‑world evidence integration guidelines.
-
Investment and M&A decision framework, including target prioritization matrices and integration checklists.
-
Case studies and primary‑research highlights derived from interviews with sponsors, CROs, regulators and payers.
Each module is designed for direct operational use: procurement teams can apply cost benchmarks in vendor negotiations; clinical operations can deploy site indices in feasibility assessments; strategy teams can stress‑test portfolios against regulatory and reimbursement scenarios.
How to Apply the Intelligence in 2026
We recommend a five‑step adoption path for executives who need to convert the report into decisions this year:
-
Assess: Run the PW Consulting scenario engine against your pipeline to quantify time‑to‑market and probabilistic value under alternative regulatory outcomes.
-
Prioritize: Use our portfolio prioritization matrix to allocate trial budgets to programs with the highest risk‑adjusted returns.
-
Pilot: Deploy one decentralized/hybrid trial with predefined success metrics and a validated technology stack to de‑risk scale.
-
Scale: Roll successful pilots into a sourcing and governance model that centralizes analytics and decentralizes patient access.
-
Measure: Embed our KPI set into quarterly reviews to monitor recruitment velocity, protocol amendments, and disclosure compliance.
Methodology, Confidence and the Limits of the Preview
The report synthesizes multiple data sources: regulatory announcements, trial registries, primary interviews with sponsors and service providers, company disclosures, and PW Consulting’s proprietary models. Forecasts were generated using a bottom‑up market model reconciled with top‑down macro drivers, and every major estimate is accompanied by sensitivity and scenario analyses to reflect regulatory and technological uncertainty.
Importantly, this press release intentionally refrains from publishing granular segment‑level shares and detailed regional splits contained in the full report. The “preview” is designed to demonstrate analytical depth and practical relevance while protecting the proprietary segment-level intelligence that subscribers rely upon for transactional and strategic decisions. The full report contains breakouts by phase, indication and region, plus downloadable datasets and interactive model access for subscribers.
Next Steps and Where to Get the Full Intelligence
For executive teams preparing budgets, negotiating CRO contracts, evaluating acquisitions, or designing next‑generation trial architectures in 2026, PW Consulting’s Clinical Trial Market Report is a practical playbook. The full report—complete with the market model, vendor scorecards, scenario engines and company profiles—is available through PW Consulting’s research portal. Access includes periodic updates reflecting regulatory developments and rolling data refreshes through 2027.
Contact PW Consulting’s Life Sciences practice for a briefing, a tailored workshop, or a demo of the report’s interactive models. The decisions you make in 2026 will set the development tempo for the next decade—our analysis shows a clear path to faster, more predictable clinical development, but execution must be guided by disciplined scenario planning and targeted capability investment.
For detailed analysis of this topic, please visit the official page: Clinical Trial Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wound Cleanser Products Market Hits USD 215.0 Million in 2025 — Momentum Builds for Further Growth
By pmarketresearch, 2026-06-29

Wound Cleanser Products Market 2026: Strategic Intelligence for Decision-Makers
Executive Snapshot
PW Consulting’s newest market research brief on the Wound Cleanser Products Market delivers an actionable intelligence package designed to inform executive decisions in 2026. Grounded in five years of historical analysis (2020–2025) with a base year of 2025 and forward-looking forecasts to 2032, our study quantifies a steady growth trajectory—driven by clinical adoption, regulatory clarification, and cost-efficiency pressures. The global market expanded from approximately USD 163 million in 2020 to roughly USD 215 million in 2025 and is forecast to continue expanding at a compound annual growth rate (CAGR) of 4.97% into the 2026–2032 horizon, reaching about USD 293 million by 2032.
Wound Cleanser Products Market
Why This Report Matters to 2026 Strategies
-
Timing and resource allocation. The report translates market momentum into a timeline for product launches, regulatory filings, and commercialization investments tailored to 2026 windows of opportunity.
Wound Cleanser Products Market -
Commercial playbooks. We provide channel-specific go-to-market guidance for hospitals, outpatient clinics, home care and distribution partners—prioritizing moves that preserve margin while accelerating uptake.
Wound Cleanser Products Market -
Regulatory and payer readiness. With an environment where wound cleansers are marketed as unclassified devices or cleared via 510(k) for mechanical cleansing and irrigation, the study outlines the precise evidence and labeling strategies that accelerate clearance and reimbursement conversations.
-
Cost-efficiency and procurement decisions. Comparative material-cost analysis—such as the clear per-patient savings potential demonstrated by pure hypochlorous acid formulations versus some legacy alternatives—grounds budgetary decisions for providers and payers.
Market Dynamics & Growth Drivers
The market’s mid-single-digit CAGR reflects several converging forces. First, clinical preference is shifting toward wound cleansers that combine mechanical cleansing with favorable safety profiles; HOCl-based formulations are being positioned as pH-balanced, non-cytotoxic options suitable across chronic and surgical indications. Second, regulatory clarity—and in several cases new 510(k) clearances—lowers the barrier for certain novel delivery formats and chemistries. Third, health systems and home-health providers are increasingly sensitive to total cost of care, creating room for products that demonstrably lower treatment costs without compromising outcomes.
Our analysis maps each driver to near-term decision levers: R&D prioritization, evidence generation investments (clinical and real-world), pricing and contracting strategies, and supply-chain resilience planning. The result is a set of tactical recommendations for C-suite and commercial leaders to execute in 2026 to capture disproportionate share of growth.
Risk Factors & Mitigations
-
Regulatory variability: While many products follow 510(k) pathways, classification ambiguity remains in some markets. Mitigation: invest in early regulatory engagement and modular submissions to reduce time-to-market risk.
-
Payer dynamics: Single HCPCS assignments exist for wound cleansers in some jurisdictions, which compresses reimbursement levers. Mitigation: build strong health-economic dossiers and pursue value-based contracting pilots.
-
Material-price pressure and supply constraints: Raw material sourcing can affect margins. Mitigation: diversify suppliers, insource critical reagents where feasible, and adopt lean manufacturing setups aligned with ISO 13485 practices.
Competitive Landscape: Profiles and Strategic Postures
Competition remains fragmented—market concentration metrics show a landscape where the top three and top five firms account for modest shares, signaling plenty of white space for innovation and consolidation. Our report profiles incumbent and emerging players and translates their strategic postures into implications for partnerships, market entry, and defensive moves.
-
Kane Biotech Inc. (Winnipeg, Canada): With FDA-cleared antimicrobial cleansing solutions now positioned for expanded U.S. commercialization, Kane’s revyve® offering is an example of how regulatory milestones materially alter commercial trajectories. Their clearance in early 2026 underscores an accelerated go-to-market opportunity.
-
Medline Industries, LP (Northfield, IL): A major distributor with broad hospital and home-care reach; their portfolio includes HOCl-based and other branded cleansers. Their channel strength makes Medline a pivotal partner or competitor in procurement negotiations.
-
Urgo Medical North America / Vashe®: Leveraging a reputation for HOCl solutions, products like Vashe® highlight clinician preference for non-cytotoxic, pH-balanced alternatives and the commercial advantage conferred by clinical familiarity.
-
Spectrum Antimicrobials, Inc. (Petaluma, CA): Their FDA 510(k)-cleared combination chemistries demonstrate a strategy of differentiation through formulation science and regulatory clearance.
-
Century Pharmaceuticals, Inc. (U.S.): An ISO 13485-certified manufacturer with long-standing sodium-hypochlorite products; their profile shows how manufacturing credentials and certs underpin procurement confidence.
-
Huizhou Foryou Medical Devices Co., Ltd. (China): The company’s 510(k) clearance for multi-format delivery illustrates the commercial value of flexible delivery formats in both acute and outpatient care.
-
Innovacyn, Inc. and Bravida Medical: Both illustrate market niches—emphasizing infection management and isotonic cleansing respectively—where focused product positioning can win clinical preference.
Notable Recent Developments
-
Product launches and OEM partnerships are reshaping distribution networks—e.g., a 2025 launch of a new HOCl wound cleanser manufactured for a major distributor expanded hospital penetration in late 2025.
-
Several firms secured or refreshed FDA 510(k) clearances between late 2025 and early 2026, unlocking expanded commercial activity in the U.S. market.
-
Certification and quality standards (FDA registration, ISO 13485) remain differentiators that tilt procurement decisions in favor of compliant manufacturers.
Actionable Insights: What Executives Should Do in 2026
-
Prioritize regulatory milestones that unlock distribution channels. A cleared label that explicitly covers mechanical cleansing, irrigation, and non-cytotoxic claims materially shortens sales cycles in hospital tenders.
-
Invest in health-economic evidence that demonstrates per-patient cost savings—our sector analysis shows clear per-patient savings opportunities with certain HOCl regimens versus legacy options—this is persuasive in payer and procurement negotiations.
-
Adopt a modular commercialization playbook: pilot in focused health systems, capture real-world outcomes, then scale through distribution partners. This staging reduces upfront market-development spend while generating defensible adoption metrics.
-
Evaluate M&A and partnership opportunities not only for market share, but for critical manufacturing capabilities, regulatory dossiers, and channel access. Given the modest concentration at the top of the market, well-executed acquisitions can deliver rapid scale.
-
Optimize SKU and delivery-format strategies for home care and outpatient settings; convenience and ease-of-use are increasingly decisive in procurement and patient adherence.
About the Report: What’s Inside (and What We’re Reserving)
Our full report is intentionally practical. It includes:
-
Comprehensive market sizing and forecast model (2020–2032) with scenario variants and sensitivity analyses calibrated for 2026 decision timelines.
-
Commercial playbooks for channel segmentation, pricing, tendering, and contracting tailored to hospitals, home care, and retail distribution.
-
Regulatory pathway templates for primary markets, a sample 510(k) evidence map, and templates for labeling and clinical claims substantiation.
-
Health-economics templates and payer pitch decks that quantify cost-per-patient impacts and ROI for procurement stakeholders.
-
Supplier and manufacturing assessment tools, including CAPEX vs. contract-manufacturing decision matrices and a risk heat map for raw-material exposure.
In the interest of constructive engagement, this press release highlights strategic takeaways and high-level metrics while withholding granular regional and application-level splits—these are available in the full report and interactive dataset on our website.
How PW Consulting Helps Executives Execute
Beyond market intelligence, we partner with clients to convert insights into results: bespoke due-diligence for M&A, rapid-market-entry programs, payer engagement pilots, and operational playbooks for scaling manufacturing under ISO 13485. Our 2026 advisory engagements prioritize interventions that de-risk commercialization and accelerate revenue capture within the forecast window.
Call to Action
For executives preparing budgets, prioritizing R&D pipelines, or structuring commercial rollouts in 2026, PW Consulting’s full Wound Cleanser Products Market report is the tactical guidebook. Access the complete dataset, regional and application breakdowns, and downloadable playbooks on our report page to move from insight to execution.
For detailed analysis of this topic, please visit the official page: Wound Cleanser Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dried Fruit Market to Expand from USD 215 Million in 2025 to USD 344.8 Million by 2032 at a 6.98% CAGR
By pmarketresearch, 2026-06-29

Dried Fruit Market 2026: Strategic Playbook for Growth, Resilience, and Value Creation
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise yet rigorous preview of our latest Dried Fruit Market report — an executive-grade briefing designed to inform board-level decisions and sharpen 2026 strategic plans. The global dried fruit market has demonstrated steady recovery and expansion since 2020, with total market value rising from the mid‑hundreds of millions at the start of the decade to a 2025 base of USD 215.0 Million. Our forecast points to a sustained expansion through the coming decade, reaching roughly USD 345 Million by 2032 at a compound annual growth rate (CAGR) of about 6.98%. This trajectory reflects accelerating demand for convenient, shelf‑stable natural ingredients and consumer willingness to pay premiums for health-forward and premiumized snack formats.
Dried Fruit Market
Why this report matters for 2026 decision-making
- Actionable foresight: We translate macro growth into discrete implications for product portfolios, sourcing contracts, and channel strategies that should be resolved in 1–3 planning cycles.
- Risk‑calibrated playbooks: Our models quantify supply and regulatory risk vectors so procurement, QA, and legal teams can prioritize mitigation investments and contracts.
- Transaction intelligence: The report is built to support M&A screening and JV negotiations by highlighting which capability gaps and commodity exposures deliver the most value per dollar deployed.
Market snapshot — what the headline numbers tell us
The industry has moved from recovery into a structurally stronger growth phase. Between 2020 and 2025 the market expanded meaningfully, with intermittent volatility driven by weather‑related supply shocks and shifting retail demand. From a 2025 base of USD 215.0 Million we forecast the market to grow at ~7% CAGR through 2032, reaching close to USD 345 Million. This growth is not uniform: premium snack formats, ingredient supply for food manufacturing, and freeze‑dried ingredient demand are evolving at different paces, amplifying strategic opportunity for firms that act decisively.
Dried Fruit Market
Key dynamics shaping 2026 strategies
- Supply-side volatility and sourcing concentration. Raw material flows are increasingly exposed to climate and geopolitical shocks. Global dried fruit production reached approximately 3.25 million metric tons in 2024/25, and certain origin markets experienced severe supply disruptions in 2025 that pushed farmgate prices and procurement risk higher. Strategic buyers must build origin diversification, multi-year contracts, and local aggregation capabilities into sourcing plans.
- Regulatory tightening and quality assurance. Regulatory changes in key markets are raising compliance and testing costs. Recent EU limits on mycotoxin levels in dried vine fruits and extension proposals for related commodities increase the cost of non‑compliant lots and heighten the importance of upstream testing and traceability. High‑visibility recalls in 2025 due to contamination have also elevated reputational risk and buyer diligence.
- Shifts in end‑market demand composition. Consumer preference for on‑the‑go, high‑protein, and better‑for‑you snacks is reshaping SKU mixes and packaging expectations. Retail collaborations and co‑branded SKUs are becoming a faster route to market than traditional co‑packing alone, particularly for organic and value‑added formats.
- Consolidation and capability‑seeking M&A. Strategic acquisitions and partnerships are being used to secure supply chains and add processing capabilities. Recent transactions and partnerships underscore the logic: firms are acquiring capacity that provides both raw supply security and higher‑margin ingredient capabilities.
- Public procurement and demand buffers. Government purchasing programs in some markets (announced procurements for processed dried fruits) create near‑term demand cushions and can be factored into capacity planning, particularly for processors that participate in public‑sector supply chains.
Competitive landscape — who’s setting the pace
The market remains fragmented: the top three players account for roughly one quarter of industry sales, leaving ample room for agile mid‑market firms to capture share through focused execution. Leading players demonstrate distinct strategic postures:
Dried Fruit Market
- Dole plc: Leveraging brand strength to accelerate organic and snack‑centric product lines targeted at mainstream retail.
- Ocean Spray Cranberries, Inc.: Investing in flavor innovation and retailer partnerships to expand snack occasions and seasonal programs.
- Sun‑Maid Growers of California: Using strategic partnerships to enter adjacent snack formats and capture on‑the‑go demand.
- Sunsweet, AGRANA, Chaucer Foods, Olam Group, and Döhler: Each pursues combinations of ingredient supply, value‑add processing, and B2B channel depth — from prunes and bakery ingredients to freeze‑dried functionality for foodservice and industrial customers.
Notable 2025–2026 moves to watch: a high‑impact acquisition aimed at strengthening processing and packing capacity; branded product launches focused on premium organic and adventurous flavors; and a high‑profile recall that has sharpened consumer and buyer attention to quality systems. Together these developments create both threats and points of entry for incumbent and challenger firms.
Strategic implications and recommended actions for 2026
- Prioritize supply‑chain sovereignty: Build layered sourcing strategies (direct sourcing, tolling agreements, and partnership farms) to reduce spot exposure. Targeted investments in origin aggregation hubs will lower landed cost volatility and improve traceability for regulatory compliance.
- Elevate food‑safety and traceability as a competitive moat: Post‑recall buyer behavior rewards demonstrable QA systems. Accelerate adoption of batch‑level digital traceability, third‑party auditing, and rapid in‑market testing to shorten time‑to‑detect and to reduce liability.
- Product portfolio reshaping: Rebalance portfolios toward higher‑margin snack formations and ingredient solutions for bakery and confectionery customers. Consider co‑development agreements with CPG brands to accelerate shelf presence and risk‑share promotional programs.
- Invest in processing flexibility: Multi‑technology drying capacity (air‑dried, drum‑dried, freeze‑dried) allows firms to pivot across value chains and capture premium price points. Investments in packaging innovation for single‑serve and lightweight retail formats increase per‑SKU margins.
- M&A and partnership playbook: Seek acquisitions that deliver both capacity and capability (e.g., dehydration expertise, organic certifications, cold‑chain logistics). Use minority stakes and offtake agreements to secure supply from high‑risk origins without overcapitalizing.
- Scenario planning for climate and origin shock: Create operational scenarios that map price, availability, and quality under defined climate stressors and trade disruptions. Embed these scenarios into quarterly procurement and hedging decision rules.
Priorities by planning horizon
- Immediate (0–12 months): Lock in multi‑year supply contracts for critical SKUs, implement mandatory traceability upgrades, and launch one pilot co‑branded snack SKU with an anchor retail partner.
- Medium term (12–36 months): Expand processing flexibility, complete one bolt‑on acquisition or strategic JV to secure origin capacity, and roll out standardized QA playbooks across facilities.
- Long term (36+ months): Build branded, direct‑to‑consumer premium lines and integrate vertically in at least one high‑value origin to control quality and margin over the cycle.
How PW Consulting supports executive teams
Our full report is designed to be directly operational for strategy teams. Deliverables include:
- Forward‑looking revenue models and scenario matrices calibrated to supplier, regulatory, and demand shocks.
- A prioritized capability investment framework (capital, people, and processes) tied to payback timing under multiple price and supply scenarios.
- A transaction playbook for acquisitions and partnerships that identifies target capability gaps, model thresholds for valuation, and integration risk mitigations.
- Regulatory compliance checklists and audit templates aligned with recent EU and US developments, plus an early warning dashboard for origin risk indicators.
What we intentionally omit here — and why
This briefing follows a “trailer” approach: its purpose is to convey the strategic contours and to catalyze action. To preserve the commercial value of the underlying analysis and ensure our clients receive competitive advantage, detailed segmented tables (regional and application splits, granular pricing ladders, and proprietary scenario datasets) are reserved for the full report and client workshops. If your team needs the exact regional and application breakdowns, price elasticities by SKU, or the underlying transaction models used to generate our M&A screens, those are available through our report portal and consulting engagements.
Next steps for executive teams
- Request a tailored briefing: schedule a 60‑minute executive synthesis with our sector leads to map these insights to your portfolio.
- Run a rapid 72‑hour sourcing stress test using our origin‑risk overlay to identify the top three procurement vulnerabilities to address in Q1 2026.
- Commission a two‑week acquisition readiness assessment if you are considering buy‑side moves in 2026; our templates accelerate diligence and integration planning.
In a market characterized by steady overall growth but punctuated by uneven supply shocks and accelerated regulatory scrutiny, the firms that win in 2026 will be those that combine operational rigor with selective product and channel innovation. PW Consulting’s Dried Fruit Market report offers the empirical foundation and decision tools needed to convert macro trends into resilient, value‑creating strategies. For access to the full dataset, segmentation breakouts, and our bespoke scenario models, please visit our report page or contact our industry practice lead to arrange a confidential briefing.
For detailed analysis of this topic, please visit the official page: Dried Fruit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Escape Tools Market Poised to Grow at a 6.98% CAGR
By pmarketresearch, 2026-06-29
Automotive Escape Tools Market: Strategic Imperatives for 2026 — PW Consulting Insight
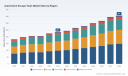
As automotive safety remains a boardroom-level priority, purchasers and suppliers of emergency escape tools face a market in transition. PW Consulting’s latest Automotive Escape Tools Market report (base year 2025, historic series 2020–2025, forecast 2026–2032) synthesizes commercial, regulatory, and product innovation forces into an actionable roadmap for executives planning investments and partnerships in 2026. Our analysis shows a clear, sustained expansion trajectory—the global addressable market grows from roughly USD 182.2 million in 2020 to an estimated USD 235.0 million in 2025, and is projected to reach approximately USD 357.0 million by 2032 at a compound annual growth rate (CAGR) of 6.98% over the forecast period—creating both predictable demand and distinctive windows for strategic moves.
Automotive Escape Tools Market
Why this matters for 2026 decision-makers
- Regulatory momentum is structural. U.S. and international regulatory activity is tightening the safety envelope around passenger protection; agencies continue to press manufacturers on occupant safety and post-crash survivability. This elevates the importance of complementary escape tools across OEM, fleet, and aftermarket channels.
- Channel dynamics are shifting. E-commerce, specialty retailers, and fleet procurement platforms are accelerating adoption cycles—creating contrast between commodity low-cost suppliers and premium, feature-differentiated brands that command margin.
- Product convergence is creating new competitive frontiers. Innovations that combine mechanical reliability with electronic functionality (e.g., integrated chargers, spring-loaded mechanisms, modular mounting systems) are redefining product defensibility and creating adjacent market opportunities.
Market trajectory and concentration — what the headline numbers tell us
The market’s steady expansion, underpinned by a mid-single-digit CAGR (6.98%), indicates robust, demand-side fundamentals rather than a short-term cyclical spike. This predictability matters: it supports capital allocation for mid-term capacity investments, targeted product development budgets, and M&A strategies focused on bolt-on competencies.
Automotive Escape Tools Market
Competitive concentration is modest. The three-largest competitors account for just over 30% of market revenue, while the top five represent roughly 43%. That positioning yields a competitive landscape where established brands retain influence, but nimble entrants and regional specialists can still capture meaningful share through targeted innovation, channel depth, or cost advantage.
Automotive Escape Tools Market
Competitive landscape: established brands, differentiated playbooks
We examined market leaders and innovators to map strategic positioning and near-term threats. Three illustrative players highlight the breadth of approaches in the market:
- resqme, Inc. — A U.S.-based brand with a long-standing, high-recognition product portfolio focused on compact, dual-function car escape tools. Their emphasis on “Made in USA” manufacturing and a history of significant unit sales underscore a classic branded-defensive strategy: trust, distribution reach, and incremental product line extensions.
- Lifehammer Brand Safety Tools — A European-origin player that leverages a heritage product platform: robust mechanical hammers with integrated cutters designed for professional and consumer use. Its strength is product reliability and channel relationships in safety-focused retail and institutional procurement.
- Ztylus Stinger Tools / Dong Guan Bao Xin Hang — A cross-border product/player blend that typifies modern product convergence: an escape tool with spring-loaded breaking mechanisms, integrated seatbelt cutters, and electronic add-ons such as USB charging. Their model represents the “feature-led” challenger, targeting tech-savvy consumers and value-engineered manufacturing pathways.
Each profile in our full report includes go-to-market models, pricing architectures, distribution maps, and identified integration risks—critical inputs for anyone evaluating partnerships, private equity investments, or supply agreements in 2026.
Key dynamics shaping vendor and buyer strategies
- Regulatory acceleration: Public agencies have intensified oversight and rulemaking. Manufacturers and distributors must embed regulatory intelligence into product roadmaps and test protocols to avoid product disruptions and to capture first-mover compliance advantages.
- Customer segmentation is converging and fragmenting simultaneously: fleet operators and institutional buyers prioritize reliability and compliance; retail consumers are increasingly drawn to multi-function products and convenience features; OEM partnerships require harmonized specifications and predictable supply chains.
- Innovation is modular: small engineering investments in materials, actuation mechanisms, and ergonomics yield outsized gains in user perception and product differentiation. Integration of low-cost electronics presents opportunity but introduces new product safety and warranty considerations.
- Channel economics: Direct-to-consumer e-commerce and subscription-based fleet provisioning alter margin structures; manufacturers must balance channel margin pressures with investments in brand-building and post-sale services.
- Supply resilience and localization: Geopolitical tensions and logistics volatility make near-shore manufacturing and supplier diversification strategic priorities for firms seeking to protect lead times and margin.
What’s inside PW Consulting’s report — pragmatic, executable content
We designed the report to be executable. Highlights include:
- Macro and micro demand modeling through 2032, with scenario overlays that stress-test regulatory and channel-shift outcomes.
- Market sizing that reconciles bottom-up SKU-level models with observed retail and aftermarket shipment data (base year 2025, historic series 2020–2025).
- Product segmentation frameworks that prioritize investible features and delineate where value accrues across the product life cycle.
- Full competitive profiles for leading and challenger firms, including commercialization roadmaps, pricing bands, and patent/technology assessments.
- Supply chain maps, cost-to-serve models, and a sourcing playbook to help procurement leaders optimize cost, lead time, and resilience.
- Regulatory impact assessment and compliance checklist tied to near-term agency activity and safety research that affect product claims and labeling.
- Go-to-market playbooks for OEM partnership, fleet sales, retail rollouts, and digital-first consumer strategies.
- M&A and investor watchlist with criteria-based target scoring and integration risk matrices.
To preserve the strategic value of the report as a proprietary decision tool, detailed tables, SKU-level breakdowns, and regional/application-specific revenue slices are reserved for the full report and associated datasets. This approach ensures that our model outputs and confidential company profiles remain usable by clients to drive commercial advantage.
Regulatory and safety context — immediate implications
Recent regulatory activity and safety research materially affect demand and product design. Agencies have increased investigatory and rulemaking efforts, while independent safety research has highlighted consumer perceptions of emerging driver assistance systems—both trends that recalibrate where and how escape tools are marketed and specified. For 2026, executives should treat regulatory monitoring as a strategic input rather than a compliance afterthought: early alignment with proposed standards can become a durable competitive moat.
Strategic recommendations for 2026
- Embed regulatory forecasting into product development sprints. Create a small cross-functional team that translates proposed rules into product requirements and test protocols—this reduces time-to-market risk and positions firms to capture OEM and institutional contracts.
- Prioritize modular product architectures. Invest in interoperable modules that allow product families to be tailored for fleet, retail, and OEM channels without end-to-end re-engineering.
- Differentiate on reliability and proof points. Publish independently verified safety tests and consumable replacement programs to justify premium positioning and reduce churn.
- Balance channel investments. Use a segmented channel playbook: pursue premium margins via specialty retail and OEM, while leveraging marketplace and subscription models for volume and recurring revenue.
- Prepare for strategic consolidation. With market concentration moderate, 2026 is ripe for bolt-on acquisitions that add distribution, IP, or localized manufacturing capacity—particularly for buyers seeking rapid scale without greenfield expansion.
- Operationalize supply resilience. Re-assess supplier single points of failure, and model near-shore vs. offshore cost scenarios under multiple logistics-stress scenarios.
How to use this report for 2026 planning
For boards, investors, and commercial leaders, the report serves three practical uses in 2026: (1) a validated market sizing and forward-looking revenue model that supports capital allocation; (2) a competitive playbook that informs pricing, channel, and product strategy; and (3) a regulatory and operational risk set that feeds into procurement, R&D, and M&A decisions. We provide both a strategic executive summary and granular appendices so that leaders can move from insight to action in weeks—not quarters.
Next steps
PW Consulting offers tailored briefings and scenario workshops that translate report findings into investment cases, product roadmaps, and acquisition screens. For executives preparing 2026 budgets or evaluating entry/expansion strategies in the Automotive Escape Tools space, our clients find immediate value in a 90‑minute strategic session that pairs the public report with bespoke modeling.
To access the full dataset, detailed segment tables, and company-level review (including the full competitive profiles and scorecards), visit PW Consulting’s report page or contact our Automotive Practice for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Automotive Escape Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Door Sensing Devices Market to Climb from USD 179.5 Million in 2025 to USD 247.2 Million by 2032, Posting a 4.8% CAGR (2026–2032)
By pmarketresearch, 2026-06-29
Industrial Door Sensing Devices Market — Strategic Imperatives for 2026
Executive snapshot
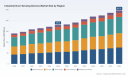
PW Consulting today releases a forward-looking briefing built from our latest Industrial Door Sensing Devices Market study (base year 2025, historical 2020–2025, forecast 2026–2032). The market has expanded steadily from a clearly defined 2020 baseline and reached an estimated USD 179.5 million in 2025. Under our central scenario the market progresses to roughly USD 247.2 million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 4.8% across the 2026–2032 forecast window.
Industrial Door Sensing Devices Market
For executives calibrating product investments, procurement strategies, or M&A activity in 2026, the report is designed as a practical decision-support toolkit: it combines rigorous, auditable macro-sizing with scenario-led strategic options, supplier scorecards, implementation checklists and regulatory impact mapping. This release note highlights the report’s unique strategic value while intentionally reserving granular split data to the full report — a focused preview that shows what matters and directs readers to the source for the detailed KPIs that power execution.
Industrial Door Sensing Devices Market
Why this market matters in 2026
-
Risk and regulation are converging with automation. Global and regional safety standards (including long-standing references such as UL 325 and recent regulatory clarifications used in North America and elsewhere) continue to push owners and integrators toward certified sensing solutions and continuous monitoring architectures.
Industrial Door Sensing Devices Market -
Warehousing and logistics modernization — accelerated by e-commerce and shoring-up supply chains — is increasing the aftermarket and retrofit opportunity for industrial door sensing systems. Facilities investing in throughput and worker safety see sensing devices as low-friction, high-ROI control points.
-
Technology shift: the unit is not just a sensor. Buyers increasingly expect connectivity, diagnostic telemetry, OTA firmware, and secure interfaces with building automation and access control. This is opening margin pools for suppliers that can pair hardware with subscription services.
-
Market structure is meaningful. The market is concentrated among a handful of established specialists, creating both barriers and platforms for new entrants. Our concentration analysis shows that the top three and top five suppliers command a materially large share of revenues — a factor that informs competitive and partnership strategies.
What the PW Consulting report delivers (practical content)
-
Rigorous market sizing and validated forecasts across 2026–2032, with sensitivity and scenario pathways (base, accelerated adoption, and conservative investment scenarios) so leaders can stress-test capital plans.
-
Actionable demand-driver analysis — mapping how regulatory timelines, retrofit cycles, and distribution center expansion translate to near-term (12–24 month) purchase windows.
-
Supplier scorecards and capability maps — independently assessed on technical performance, compliance maturity, channel reach, and service model. These are complemented by RFP templates and negotiation playbooks.
-
Technology & integration playbook — comparison of sensing modalities (active infrared, LiDAR-like scanning, radar, ultrasonic, mechanical contact edges, etc.) by use-case suitability, installation complexity, and total cost of ownership (TCO) implications.
-
Regulatory impact matrix and implementation checklist that aligns standards (UL 325, CPSC rules relevant to entrapment mitigation, occupational safety norms such as ISO 45001) to procurement and test procedures.
-
Commercial benchmarks — pricing guidance, warranty and service models, upgrade paths and suggested bundling strategies for hardware + software revenue capture.
-
M&A and partnership playbook focused on three archetypes: capability acquisition (edge compute, analytics), channel expansion (regional distributors and integrators), and product-line bolt-ons (retrofit kits and modular sensors).
Competitive landscape — who matters and why
The industry remains populated by a mix of specialist sensor manufacturers and broader industrial automation firms. Our competitive analysis highlights five firms that shape product direction, channel behavior and standards interpretation:
-
Hotron (Japan) — a focused automatic-door sensor specialist known for compact activation and safety devices tailored to sliding and swing door use-cases. Recent product activity through late 2025 and into 2026 underscores Hotron’s strategy of incremental, installer-friendly innovation: multi-function activation/safety sensors and targeted upgrades that accelerate installation time and reduce labor costs.
-
BEA Sensors (United States) — established for motion, presence and safety scanners and curtain sensors for high-speed doors and loading-dock scenarios. BEA’s product family — including scanning and presence detection models — positions it strongly with warehouse and logistics integrators where throughput and pedestrian protection are priorities.
-
OP TEX (Japan) — emphasizes high-performance detection and pedestrian safety in commercial and industrial contexts. Their engineering focus on reliability and precision detection under variable environmental conditions is an anchor for customers prioritizing uptime.
-
Telco Sensors (Germany) — a European presence manufacturing presence and safety devices, with strengths in meeting local installation practices and distributor relationships across industrial markets.
-
ifm electronic (Germany) — broader industrial automation portfolio with fail-safe inductive sensors and RFID-coded safety switches that frequently serve integrators seeking turnkey reliability and compatibility with factory automation systems.
PW Consulting’s supplier assessments combine objective lab performance tests, channel checks and commercial interviews. The full report contains comparative scorecards and procurement-ready evaluations designed for CIOs, CTOs, procurement heads and M&A teams. In the spirit of this preview, we highlight patterns rather than granular ranks: large, specialized vendors retain advantages in product certification and distribution; mid-tier players are competing on integration and service models; and niche entrants win by delivering software-enabled value propositions.
Near-term strategic plays for 2026
-
Prioritize retrofit-friendly product lines. For owners of aging door fleets the fastest path to risk reduction and compliance is modular sensor solutions with minimal structural work. Allocate CapEx to kits that reduce installation labor.
-
Invest in connected diagnostics. Even modest telemetry that reduces site visits can move a sensing-device purchase from a commodity buy to a recurring-service revenue stream. For manufacturers, build secure, standards-aligned APIs from day one.
-
Use regulatory timelines as a sales lever. Buyers respond to compliance requirements; procurement and channel teams should align marketing, training and certification support with the most relevant standards in target regions.
-
Adopt a portfolio approach to supplier selection. Combine incumbent-certified vendors for critical safety devices with niche partners for advanced sensing or analytics — this reduces single-vendor risk without sacrificing performance.
-
Prepare supply continuity plans for critical components. Component concentration in sensing (for example, certain optoelectronic modules) can create pinch points. Design products with component flexibility and qualify alternate suppliers in 2026.
-
Pursue tuck-in M&A to accelerate software and connectivity capabilities. Targets that enable remote diagnostics, predictive maintenance or firmware management materially lift margins and create cross-sell opportunities.
How to use this report for immediate impact
-
Run 90-day vendor audits using our supplier checklist to identify certification and service gaps that elevate near-term safety risk.
-
Apply the included scenario models to board-level capital planning to see how different adoption speeds alter ROI and payback timelines.
-
Leverage the RFP templates and scoring matrices in supplier negotiations to secure performance guarantees and post-sale service credits.
-
Integrate the regulatory impact matrix into procurement and project specifications so that safety and compliance are contractual deliverables, not afterthoughts.
Closing — why PW Consulting’s insight matters for 2026
Between 2026 and 2032 the industrial door sensing devices market is expected to follow a steady, predictable growth path. That predictability masks complexity: growth is uneven by use-case and distribution channel, influenced by regulatory cycles, retrofit economics and technology transitions from basic sensing to connected, software-rich systems. PW Consulting’s report synthesizes these forces into decision-ready guidance for executives who need to convert market forecasts into procurement plans, product roadmaps and M&A pipelines in 2026.
If your organization is preparing to invest, partner, or compete in this space, the full report delivers the granular split tables, vendor scorecards, pricing benchmarks and downloadable tools required to operationalize strategy. PW Consulting invites procurement teams, product leaders and corporate development groups to review the complete study and use our templates to accelerate decision velocity in 2026.
For detailed analysis of this topic, please visit the official page: Industrial Door Sensing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com