

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Welded Bellows Market to Hit $505.26M by 2032, CAGR 5.81%
Global Welded Bellows Market Outlook 2026: Strategic Intelligence for Enterprise Decision-Making
The worldwide welded bellows industry stands at a critical inflection point as global manufacturing infrastructure shifts toward higher precision, stricter contamination control, and more demanding operational environments. For executives navigating capital allocation, supply chain resilience, and product portfolio strategy in 2026, accurate market intelligence is no longer a luxury. It is a prerequisite for informed decision-making. Our latest Worldwide Welded Bellows Market research delivers a comprehensive, data-grounded assessment of the sector, designed to equip leadership teams with the clarity required to position operations ahead of structural shifts rather than react to them after the fact.
Why 2026 Demands a Fresh Strategic View
Market trajectories in precision-engineered components rarely follow linear paths. They are shaped by capital cycles, technology adoption curves, regulatory tightening, and regional capacity investments that compound over time. The welded bellows segment reflects this complexity. Drawing on historical performance from 2020 through 2025 and extending a forward-looking projection window from 2026 to 2032, our analysis establishes a baseline that helps organizations separate cyclical noise from durable growth signals.
The overall market, measured in millions of U.S. dollars, expanded from approximately 258.42 million in 2020 to an estimated 340.5 million in 2025. That progression underscores sustained demand across multiple industrial ecosystems, even as macroeconomic conditions fluctuated. Looking ahead, the forecast period frames a compound annual growth rate of 5.81 percent, with projected revenue reaching roughly 370.73 million in 2026 and continuing its upward arc toward the 505.26 million range by 2032. These figures are not merely retrospective statistics. They form the quantitative foundation for evaluating capacity planning, R&D prioritization, and go-to-market timing.
For enterprise strategists, the most valuable insight is not the destination number alone, but the pattern of expansion. Growth is not distributed uniformly across all end-use environments or all engineering materials. Some application fields are absorbing more displacement capacity, some regions are consolidating supply networks faster than others, and certain material grades are being pulled into service by extreme operating conditions that stainless steel alone cannot satisfy. Understanding where momentum concentrates allows decision-makers to align internal capabilities with external demand rather than diluting resources across low-yield avenues.
What This Research Delivers: Actionable Intelligence Beyond headlines
A market report only earns its strategic weight if it translates into operational choices. Our study is structured to provide exactly that bridge between high-level industry positioning and practical execution. Instead of offering a generic overview, the analysis dissects the welded bellows landscape through lenses that matter to procurement leaders, engineering directors, and corporate planners.
Market Sizing and Forward Trajectory
The research quantifies historical revenue performance, then maps projected expansion across the full forecast horizon. This dual view supports scenario planning, allowing organizations to test internal growth assumptions against external benchmarks. Whether a company is evaluating whether to scale production, enter a new region, or invest in specialized manufacturing lines, the directional framework helps calibrate ambition against realistic market absorption.
Segmentation That Reveals Where Value Is Concentrated
The report examines the market through multiple segmentation dimensions, including geography, material composition, and application categories. These breakdowns illuminate which clusters command the largest revenue volumes and which are gaining relative share. Executives can use this information to assess whether their current product mix aligns with high-volume end markets or whether strategic repositioning may be warranted. The segmentation discussion also highlights the interplay between material selection and end-use performance requirements, giving engineering and procurement teams a structured way to evaluate trade-offs between cost, durability, and operating environment demands.
Machine Tool Protection Bellows Market
Competitive Landscape and Structural Positioning
Market concentration data reveals the degree of consolidation within the industry, an essential factor for companies assessing competitive threats, partnership strategies, and potential acquisition targets. By mapping the structure of the market rather than merely listing participants, the study helps organizations understand where scale advantages matter, where specialization creates barriers, and where fragmented supply can be leveraged or disrupted.
Manufacturing Standards, Compliance, and Operational Readiness
In high-performance bellows production, specifications often define competitive viability as much as price or throughput. The research addresses how cleanroom assembly requirements, quality certification expectations, and application-specific validation influence sourcing decisions. For enterprises operating in semiconductor, medical, aerospace, or ultra-high vacuum environments, alignment with stringent production standards is not optional. This section provides the context needed to evaluate supplier readiness, internal compliance roadmaps, and the operational cost of meeting contamination-sensitive specifications.
Strategic Drivers and Restraints Shaping the Next Cycle
Market expansion is supported by durable forces, including the proliferation of advanced semiconductor fabrication, the intensification of aerospace and defense programs, and the ongoing need for leak-tight, high-cycle-life sealing solutions in vacuum and precision fluid systems. At the same time, cost pressures, raw material variability, and certification burdens shape the pace at which suppliers can scale. By characterizing these forces together, the report gives leaders a balanced framework for forecasting both opportunity and constraint.
Market Dynamics Shaping Competitive Advantage
The welded bellows market does not evolve in a vacuum. It is pulled by application demand, constrained by manufacturing complexity, and reshaped by procurement expectations that increasingly reward reliability over mere availability. Several dynamics warrant particular attention for 2026 planning.
PW Consulting
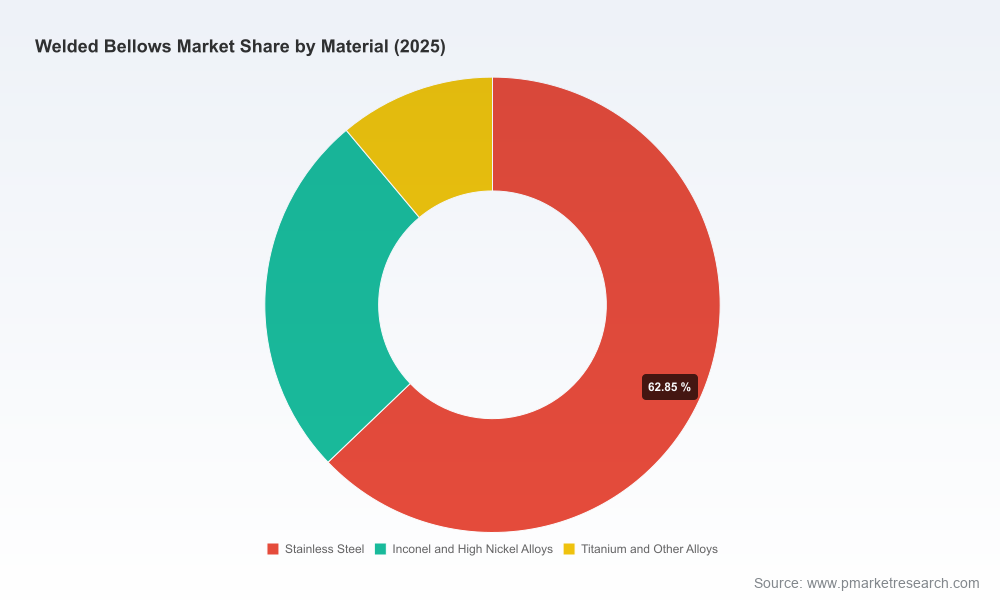
- Material performance requirements are becoming more application-specific. While stainless steel alloys remain a dominant choice for many pressure and vacuum environments due to their corrosion resistance, cost profile, and suitability across low-temperature and high-pressure conditions, high nickel alloys are gaining traction in extreme-temperature service, particularly within aerospace and defense applications.
- End-use sectors with the most demanding sealing and vibration compensation requirements are driving adoption of bellows engineered for long cycle life, dimensional stability, and contamination control. This shifts competitive emphasis from generic supply toward specialized engineering capability.
- In semiconductor-related applications, cleanroom assembly conditions and certification expectations have become decisive factors in supplier qualification. Organizations that cannot meet these standards face structural disadvantages in high-value equipment supply chains.
- Regional supply networks are increasingly evaluated through the lens of resilience and proximity. As procurement strategies lean toward reduced disruption risk, geographic positioning and manufacturing footprint can influence sourcing decisions as much as unit economics.
Taken together, these dynamics suggest that competitive advantage in the coming years will depend less on volume alone and more on the ability to match material selection, manufacturing discipline, and application-specific engineering to the most demanding buyers.
Competitive Landscape: Who Is Shaping the Market and How
The industry features a set of specialized manufacturers whose capabilities, geographic footprints, and application focus define the current competitive architecture. Several players stand out for their long-standing production heritage, material breadth, and emphasis on mission-critical service environments.
Senior Metal Bellows, based in Sharon, Massachusetts, has built its reputation around custom-engineered edge-welded metal bellows for aerospace, defense, energy, semiconductor, and medical applications, leveraging stainless steel, high nickel alloys, and titanium. Its nearly seventy-year operating history and continued investment in capabilities signal a positioning centered on bespoke engineering rather than commodity supply. In February 2026, a procurement opportunity surfaced through the U.S. Government and Fermi National Accelerator Laboratory for edge-welded bellows sub-assemblies related to the PIP-II SSR2 Cryomodule project, illustrating how defense and advanced research programs continue to generate high-specification demand. More recently, in March 2026, Senior plc reported strong performance in its aerospace segment, including edge-welded bellows activities, with revenue growth and a positive book-to-bill ratio, reinforcing the link between high-value end markets and sustained commercial momentum.
KSM, operating across Japan and the United States, positions itself as a leading global supplier of edge-welded metal bellows with a strong emphasis on dynamic seals and ultra-high vacuum solutions. Its scale claims and application focus reflect the growing importance of vacuum integrity and precision sealing in advanced manufacturing and scientific instrumentation.
Technetics Group, part of EnPro Industries and headquartered in Columbia, South Carolina, brings more than sixty years of experience to its BELFAB edge-welded metal bellows portfolio. Its service coverage spans semiconductors, aerospace, energy, and life sciences, with cleanroom assembly capabilities that align directly with contamination-sensitive procurement requirements.
Metal-Flex Welded Bellows Inc., located in Newport, Vermont, produces both standard and custom edge-welded bellows for pressure and vacuum applications across semiconductor, aerospace, food processing, chemical, and medical sectors, and maintains ISO 9001 and ITAR registration, underscoring its orientation toward regulated and defense-adjacent supply chains.
Duraflex, Inc., based in Cary, Illinois, manufactures custom and standard edge-welded metal bellows alongside hydroformed bellows and expansion joints for piping systems, with AS9100D and ISO 9001:2015 certifications that reflect aerospace and industrial quality expectations.
BOA Group, based in Germany, is recognized as a major producer of high-quality welded metal bellows for automotive, aerospace, and industrial applications, with a stated emphasis on innovation. Belman A/S, operating from Denmark with UK operations, specializes in metal expansion bellows and joints designed to handle thermal expansion, vibration, and movement in piping systems. VAT Group, headquartered in Switzerland, manufactures high-performance edge-welded metal bellows in cleanrooms spanning ISO class 5 through 8, targeting vacuum applications, vibration compensation, and flexible sealing.
Eagle Industry Co., Ltd., also known as EKK, operates from Japan and manufactures nesting-type welded metal bellows using precision forming and welding for mechanical seals, vacuum, semiconductor, and nuclear applications. BellowsTech, part of MW Components and based in Ormond Beach, Florida, offers custom and stock edge-welded metal bellows with high stroke length capabilities for critical applications. Flex-A-Seal, Inc., in Essex Junction, Vermont, manufactures welded metal bellows seals, while Hyspan Precision Products, Inc., supplies welded metal bellows and related precision products in the United States. Mera Bellows, a German manufacturer, has been a leading producer of hydroformed metal bellows, expansion joints, and deep-drawn tubes since 1956.
Metal Bellows Market
This diversified field matters strategically. The presence of both broad-capability suppliers and application-focused specialists means that procurement teams must evaluate candidates not just by price, but by certification alignment, material expertise, cleanroom readiness, and the ability to support demanding end-use cycles. For competitors, it also means that differentiation increasingly comes from engineering reliability and process control rather than basic product availability.
What Leaders Should Do With This Intelligence in 2026
The strategic value of a market study lies in how it changes decisions. The welded bellows sector is expanding, but expansion alone does not guarantee profitable participation. Organizations that treat the market as a single homogeneous opportunity risk misallocating capital and missing the segments where purchasing criteria are most stringent and switching costs are highest.
Leaders should use this research to answer several practical questions. Which application areas in their portfolio map most closely to the highest-revenue end markets, and which are exposed to more volatile demand? Where do material and certification requirements create barriers that can be converted into competitive moats? Are internal manufacturing capabilities aligned with cleanroom expectations, quality system standards, and the tolerance levels demanded by advanced vacuum and semiconductor supply chains? Do regional supply strategies reflect both cost considerations and resilience priorities? And, perhaps most importantly, does the organization’s growth plan assume broad market tailwinds, or does it target the specific drivers that are actually pulling demand forward?
The answers to those questions determine whether a company merely participates in the market or shapes its position within it.
Closing Perspective
The worldwide welded bellows market is entering a phase in which demand, performance standards, and competitive specialization are increasingly intertwined. For executives planning in 2026, that environment rewards informed precision. Our complete Worldwide Welded Bellows Market research assembles the full market sizing framework, segmentation detail, competitive analysis, and operational context needed to make those decisions with confidence. The executive summary presented here provides the strategic direction; the full report delivers the comprehensive intelligence required to act on it.
For detailed analysis of this topic, please visit the official page: Worldwide Welded Bellows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com