

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Self‑Healing Gel Market Poised to Grow at 9.85% CAGR (2026–2032), Topping USD 551.15 Million by 2032

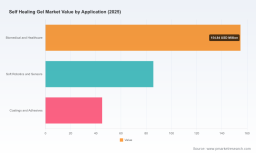
Self‑Healing Gel Market 2026 Strategic Brief — PW Consulting Insight Preview
Executive summary
As the self‑healing gel market transitions from niche lab breakthroughs to accelerating commercial adoption, 2026 is shaping up as a decisive year for corporate strategy. PW Consulting’s latest market study (base year 2025; historical window 2020–2025; forecast 2026–2032) shows the market is on a sustained growth path — a nearly 10% compound annual growth rate (CAGR) across the forecast horizon. Mid‑decade inflection points in regulation, reimbursement and materials supply chains will create windows of asymmetric opportunity for companies that align R&D, regulatory strategy and go‑to‑market execution.
Self Healing Gel Market
Why this matters to corporate decision‑makers in 2026
- Scale and velocity: The market more than doubles from the 2025 base across the forecast period, reflecting both expanding clinical adoption and cross‑industry spillover into soft robotics, coatings and adhesives.
- Fragmented competitive structure: Market concentration remains relatively low (CR3 ~22.4%; CR5 ~35.8%), indicating room for consolidation, niche leadership and disruptive entrants backed by differentiated IP or manufacturing scale.
- Regulatory bifurcation: Accelerated pathways in some jurisdictions speed commercialization for certain clinical claims, but simultaneous tightening of global standards raises compliance complexity and costs.
- Operational sensitivity: Raw material volatility — particularly in specialty polymers and biomaterials — will materially affect margins and time‑to‑market unless mitigated through supply chain hedging or vertical integration.
Market trajectory and strategic implications (high level)
PW Consulting’s modeled trajectory demonstrates robust expansion driven by converging factors: validated clinical outcomes in advanced wound care, published materials science breakthroughs enabling tougher and faster self‑repair, and cross‑sector demand from soft robotics and intelligent coatings. The nearly 10% CAGR is not uniform; our scenario analysis anticipates pockets of hypergrowth where regulatory clarity, reimbursement recognition and scalable manufacturing coalesce.
Self Healing Gel Market
For 2026 strategy, this translates into three primary implications:
Self Healing Gel Market
- Prioritize regulatory and reimbursement pathways for clinical applications where accelerated approval routes are viable and cost‑effectiveness evidence can be generated with targeted real‑world studies.
- Invest selectively in modular manufacturing capacity and raw material partnerships to reduce time‑to‑scale and insulate margins from input price shocks.
- Adopt a dual‑track commercialization model: defend and expand core biomedical applications while piloting non‑medical adjacent markets (e.g., soft robotics) that can subsidize R&D and factory utilization.
What PW Consulting’s report delivers (practical, actionable content)
We designed the full report as a decision‑centric playbook for 2026 corporate leaders. Key deliverables include:
- Market sizing and validated growth scenarios (base year 2025; forecast 2026–2032) with sensitivity testing around regulation, raw material volatility and reimbursement uptake.
- Go‑to‑market frameworks segmented by value chain role (innovator, contract manufacturer, platform licensor, integrated medtech) — each with tailored KPIs and go/no‑go triggers for 12–36 month horizons.
- Regulatory and reimbursement pathway maps for major jurisdictions, including recommended evidence generation strategies to shorten commercialization timelines while controlling study budgets.
- Supply chain risk matrix and mitigation playbook: supplier scorecards, alternative material substitutions, strategic inventory sizing and contract terms to stabilize margin exposure to polymer price swings.
- M&A and partnership playbook built from a bottom‑up valuation model: acquisition targets by capability (IP, manufacturing, regulatory dossiers, clinical networks) and integration checklists to preserve innovation velocity post‑deal.
- Commercial pilots & evidence roadmaps: pragmatic protocols for real‑world evidence and small randomized studies that can produce payer‑relevant outcomes in under 18 months.
Note: the full report contains granular segment tables and regional breakdowns that underpin these recommendations. This preview intentionally omits those detailed tables to guide readers to the full dataset on our site.
Competitive landscape — who matters and how they are positioning
The supplier ecosystem combines established medtech players, specialized hydrogel innovators and emerging biotech start‑ups. Notable players covered in depth in the report include:
- Advanced Medical Solutions Group PLC (UK) — long‑standing wound care specialist with productized hydrogel platforms; strategic strength in clinical distribution networks.
- Axelgaard Manufacturing Co. Ltd. (Fallbrook, CA) — developer of AmGel hydrogels, notable for combining medical and sensing applications, a model we classify as ‘application convergent’.
- Cardinal Health (Dublin, OH) — large healthcare distributor and product supplier with breadth in hydrogel dressings; leverages channel reach to accelerate adoption.
- Hydromer Inc. (Branchburg, NJ) — specialized in hydrophilic coatings and device interfaces with an emphasis on material science that enables self‑healing properties.
- Gel4Med Inc. (USA) — emerging biomimetic hydrogel innovator with recent clinical evidence and regulatory clearances; represents a case study in rapid translation from FDA 510(k) to real‑world evidence.
- Alliqua Biomedical, Contura International, Smith & Nephew, 3M — incumbents and diversified players that create competitive pressure through scale, channel access and cross‑portfolio bundling.
Market concentration metrics indicate a fragmented landscape, which favors both specialist innovators (fast, clinically driven launches) and larger players (scale and channel). The competitive ledger in 2026 will reward firms that convert IP into repeatable manufacturing and payer‑accepted clinical value.
Recent developments to watch (signal vs. noise)
- Gel4Med’s FDA 510(k) clearance and subsequent real‑world case series (including leading academic centers) demonstrate a reproducible route from regulatory clearance to adoption when supported by focused clinical evidence.
- University‑led materials breakthroughs — notably work on mechanically robust, self‑healing skin‑like hydrogels — expand the addressable use cases and raise the bar for product performance.
- Research on stimuli‑responsive polysaccharide hydrogels shows promise for smart release applications, indicating potential product differentiation in wound care and beyond.
- At the policy level, jurisdictions with accelerated approval pathways can shorten commercialization lead times, but global commercialization still requires navigating divergent requirements and reimbursement frameworks.
Regulatory, reimbursement and supply chain dynamics — tactical guidance
Regulation is a double‑edged sword: accelerated pathways provide first‑mover advantages, but harmonizing dossiers across markets increases upfront investment. Reimbursement remains uneven; even clinically superior products can struggle without carefully crafted health economic evidence. Raw material price volatility is a persistent operational risk.
Recommended tactical moves for 2026:
- Establish a regulatory steering committee dedicated to parallel filings and early engagement with regulators in priority markets.
- Design clinical programs with embedded health economics endpoints and early payer engagement to shorten reimbursement negotiations.
- Negotiate multi‑year supply agreements for critical polymers, include passthrough clauses, and qualify secondary suppliers to prevent production interruptions.
Strategic playbook for 2026 — prioritized actions by role
- Innovators / SMEs: Focus on narrow, high‑value clinical claims with robust but streamlined evidence generation; seek non‑dilutive financing and licensing offers before large scale manufacturing investments.
- Large Medtech / Industrials: Pursue bolt‑on acquisitions to acquire differentiated materials or regulatory dossiers; use channel strength to accelerate clinician adoption and scale manufacturing.
- CMOs / Manufacturers: Invest in modular, flexible production lines to capture demand from multiple clients and shorten ramp time for novel formulations.
- Payers / Hospital Systems: Pilot value‑based contracts that tie reimbursement to healing outcomes, thereby de‑risking adoption of premium self‑healing products.
Methodology, confidence and what’s behind the headline numbers
Our market sizing blends top‑down demand modeling with bottom‑up supply analysis, validated by primary interviews and a proprietary database of clinical adoption rates. The reported CAGR (~9.85%) and market trajectory reflect consensus and alternative scenarios ranging from conservative to aggressive uptake. We attach high confidence to the market direction; timing and segmentation granularity are subject to regulatory and macroeconomic shocks — items for which the full report provides contingency playbooks.
Conclusion — the strategic window in 2026
2026 is less about whether self‑healing gels will matter and more about who will own the structural advantages in the space. Our analysis shows a large, fast‑growing market where first movers with integrated strategies (evidence, regulatory, manufacturing and payer alignment) will secure disproportionate returns. The full PW Consulting report—built for executive decision‑makers—provides the data tables, segment matrices and operational toolkits needed to convert this strategic insight into executable plans. For the detailed segment breakdowns, company profiles and model downloads, visit our report page to access the full intelligence package.
For detailed analysis of this topic, please visit the official page: Self Healing Gel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com