

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Saline Nasal Mist Market to Rise from USD 788.68 Million in 2025 to USD 1,325.59 Million by 2032 on a 7.7% CAGR

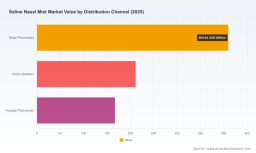
Saline Nasal Mist Market 2026 Strategic Outlook — PW Consulting Preview
As the global healthcare landscape prioritizes non-pharmaceutical, low-barrier interventions for upper respiratory wellness, the saline nasal mist market has emerged as a durable growth niche. Our PW Consulting Saline Nasal Mist Market report — with a 2025 base year and a 2026–2032 forecast horizon — found the market at approximately USD 788.7 Million in 2025 and projecting robust growth at a 7.7% compound annual growth rate through 2032, reaching roughly USD 1.33 Billion by the end of the forecast period. This industry brief outlines why these macro dynamics matter to boardrooms and investment committees preparing plans for 2026, what practical outputs our full report delivers, and the high-conviction strategic moves that will separate winners from followers in the next 18 months.
Saline Nasal Mist Market
Why this market merits attention in 2026
-
Resilient demand drivers — Saline nasal products play a dual role as daily hygiene tools and symptomatic relief options. Their low regulatory friction in many markets, combined with rising consumer focus on respiratory wellness, supports steady end-user adoption across age cohorts.
Saline Nasal Mist Market -
Channel evolution — Retail and digital channels are evolving in parallel: omnichannel distribution and subscription models are creating opportunities to capture recurring revenue and deepen customer lifetime value.
Saline Nasal Mist Market -
Regulatory inflection points — Updated device-performance expectations and sterility requirements in key jurisdictions are raising the bar on manufacturing and quality systems, creating a differentiation axis for manufacturers that can reliably demonstrate compliance and product safety.
-
Outsourcing and supply resilience — Demand for contract development and manufacturing services is accelerating as brands look to shorten time-to-market and de-risk supply chains following high-profile contamination events in the category.
What PW Consulting’s report delivers — practical, transaction-ready intelligence
Our full market study is built for decision-makers who need actionable outputs, not just high-level narratives. Highlights include:
-
A validated market-sizing model (2020–2025 historical; 2026–2032 forecast) with sensitivity scenarios to stress-test volume and price assumptions.
-
Commercial playbooks for manufacturers and retailers: product positioning frameworks, SKU rationalization heuristics, and channel-specific go-to-market templates (including D2C subscription and pharmacy chain partnerships).
-
Regulatory & compliance toolkits: step-by-step checklists for FDA device classification and performance testing, EU MDR preparedness for substance‑based devices, and USP sterility considerations for sterile claims.
-
M&A and partnership screening: a short‑list of target profiles, valuation benchmarks, and integration risk matrices for strategic buyers and private equity sponsors.
-
Supply-chain playbook: raw-material sourcing maps, favored CDMO partners by capability, and contingency planning templates designed for rapid supplier substitution without disrupting market supply.
-
Commercial financial models and dashboards that allow investors and business leaders to run “what‑if” scenarios on pricing, channel mix, and new product introductions.
To preserve competitive value and drive direct engagement, the report intentionally previews strategic findings while withholding granular segment-by-segment data in this release. Subscribers and purchasers will receive the complete tables, interactive models, and downloadable assets.
Competitive landscape — who matters and why
The market is moderately consolidated; top three players collectively hold a meaningful portion of the market, while the top five increase that concentration further. For incumbents and entrants alike, a nuanced approach to brand, distribution, and capability is essential.
-
NeilMed Pharmaceuticals Inc. — Recognized leader in nasal irrigation systems and sterile saline sprays; strong product breadth, including pediatric formulations, gives it category credibility and a durable retail presence.
-
Church & Dwight (Arm & Hammer) — Consumer-brand strength and shopper marketing expertise make it effective at driving category penetration through retail pharmacy channels.
-
Ayr (Prestige Consumer Healthcare) — Niche positioning around daily moisturization and allergy-related relief supports consistent demand across seasons.
-
Haleon — Global OTC footprint and established nasal-care brands enable large-scale distribution relationships and promotional leverage.
-
Reckitt — Recent product launches indicate strategic use of established respiratory brands to introduce drug-free saline variants to mass-market consumers.
-
AdvaCare Pharma — GMP-certified manufacturer with multi-market distribution; represents the type of vertically integrated supplier emerging as a reliable OEM/ODM partner.
-
Bayer, Sterimar, Laboratoires URGO, Little Remedies, Zarbee’s — These firms collectively illustrate diverse approaches: multinational scale, seawater‑based niche formulations, pediatric specialization, and ‘natural ingredient’ brand narratives.
-
Catalent & Renaissance Pharma — Critical CDMO partners enabling formulation development, commercial-scale fills, and quality systems compliance for brands looking to outsource manufacturing.
Recent category events underscore the market’s opportunity and risk profile: product launches by established respiratory brands demonstrate continued commercial confidence, while contamination-related recalls elsewhere in nasal sprays are a stark reminder that sterility and quality controls are now a top strategic priority.
Regulatory & reimbursement context — practical implications
-
United States: Many non-sterile saline nasal sprays are regulated as Class I ENT drug administration devices and can be 510(k)-exempt, but product claims (sterile labeling, therapeutic claims) change regulatory pathways and testing obligations.
-
European Union: Saline sprays positioned as substance‑based medical devices typically fall under MDR Rule 21 and often require Class IIa conformity — manufacturers must prioritize technical documentation and clinical evaluation plans.
-
Sterility and testing: Sterile claims invoke USP <71> sterility testing and related procedural controls. The FDA’s 2025 guidance updates on nasal spray performance emphasize robustness testing after handling — a non-trivial compliance step for device design and packaging.
-
Reimbursement mechanics: Saline nasal mist products may qualify as eligible expenses under FSA/HSA/HRA arrangements in several jurisdictions, supporting employer-channel sales and targeted benefit-driven consumer outreach.
Strategic plays for 2026 — prioritized actions
-
Manufacturers — Invest in demonstrable quality and sterility credentials; prioritize product differentiation through device ergonomics and preservative‑free sterile lines. Use CDMO partnerships to accelerate capacity while insulating core quality systems.
-
Retailers & E‑commerce players — Expand subscription and bundle offerings; integrate self-care education into checkout flows; pilot tele‑triage partnerships with allergy and ENT clinics to up-sell higher-margin portfolios.
-
Private equity & strategic acquirers — Target mid‑sized brands with strong retail relationships or patented device features; prefer targets with validated GMP and clean inspection histories to reduce integration risk.
-
CDMOs & suppliers — Differentiate through rapid turnaround clinical batches, sterility validation support, and regulatory dossier co-development services.
-
Public health & hospitals — Adopt saline-based nasal hygiene programs as adjuncts to respiratory infection mitigation protocols, while ensuring product sourcing is traceable and sterility-validated.
Risk matrix — what to watch
-
Product contamination and recalls: high impact; requires immediate investment in QC/QA and lot‑release testing.
-
Regulatory tightening: changes in device classification or evidence expectations could elevate development costs for sterile or therapeutic claims.
-
Channel disruption: shifting consumer shopping behavior could redistribute sales between retail and online faster than firms can optimize supply chains.
-
Raw-material constraints: packaging components (valves, pumps) and pharmacopeial-grade salts can become pinch points during demand surges.
90‑day playbook for leadership teams
-
Conduct a rapid audit of sterility testing and supplier certification; remediate gaps within 60 days.
-
Run our interactive scenario model to evaluate the impact of accelerating a D2C channel vs. expanding pharmacy listings; prioritize the highest-return pilot.
-
Engage 2–3 CDMO partners with demonstrated sterility capabilities and request pilot runs tied to performance KPIs.
-
Initiate one cross-functional project to convert a legacy product into a preservative‑free sterile variant, aligned with marketing and reimbursement strategies.
Next steps
PW Consulting’s full report includes the complete datasets, granular segmentation tables, interactive financial models, and a proprietary shortlist of M&A and partnership targets — all designed to support evidence‑based decisions in 2026. This preview is intended to surface the strategic contours and operational imperatives; the full intelligence package provides the actionable granularity required to execute.
For access to the full report, model access, and bespoke consulting engagements tailored to your role in the value chain — manufacturer, retailer, CDMO, or investor — contact our Saline Nasal Mist Market team at PW Consulting.
For detailed analysis of this topic, please visit the official page: Saline Nasal Mist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com