

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metal Powder Atomizer Market to Reach USD 1,070.07 Million by 2032, Growing at a 6.84% CAGR

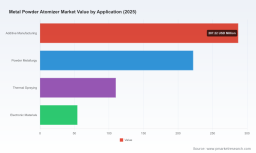
PW Consulting: Strategic Outlook — Metal Powder Atomizer Market (Base Year 2025) and the Imperatives for 2026 Decision-Making
PW Consulting today releases a forward-looking industry brief accompanying our full Metal Powder Atomizer Market study. Using 2025 as the reference point, our modelling shows a global atomizer equipment and services market of USD 673.4 Million (Revenue Unit: Million USD) in the base year, with expected expansion to approximately USD 1,070.07 Million by 2032 at a compound annual growth rate (CAGR) of 6.84% across the 2026–2032 forecast window. For executives planning capital deployment, technology sourcing, or partnerships in 2026, this trajectory crystallizes both the scale of opportunity and the timing of capacity and capability decisions.
Metal Powder Atomizer Market
Why this briefing matters for 2026 strategic choices
-
Timing of capacity investments: The market growth profile indicates steady expansion rather than a short-term spike. Organizations that delay CAPEX until 2027+ risk paying a premium for accelerated build-out or missing first-mover supply agreements with AM and powder metallurgy customers.
Metal Powder Atomizer Market -
Cost-structure levers are actionable now: Consumables and utilities — notably inert gases for gas atomization and ultra-high pressure water in water atomizers — are material contributors to unit economics. Operational choices made at the procurement and engineering stages in 2026 will materially affect long-run cost curves.
Metal Powder Atomizer Market -
Regulatory and safety compliance is non-negotiable: Requirements such as ATEX-rated equipment for reactive-metal processing and strict atmosphere control for high-performance spherical powders demand early integration of compliance design into procurement and plant layout.
-
Supply-chain and partnership decisions will determine market access: Direct-to-printer logistics, inert atmosphere handling, and closed-loop powder transport are emerging differentiators for downstream AM customers.
What PW Consulting’s full report delivers (practical, workbench-focused)
-
Integrated market sizing and forecasts: Top-line market size by year (historical 2020–2025, base year 2025) and modeled scenarios through 2032 with sensitivity analysis tied to demand shocks and raw-material price volatility.
-
Segment frameworks: A repeatable taxonomy across atomizer types, end-use applications, and regional demand footprints — designed to support go/no-go decisions without compromising confidentiality of proprietary client models. (Note: detailed sub-segment tables and exact regional/application shares are available in the full report.)
-
Vendor benchmarking and shortlists: Comparative capability maps that rate OEMs across technology maturity, scale, after-sales, and R&D pedigree — enabling a rapid shortlist for trials or procurement RFPs.
-
CapEx/Opex playbooks: Build-versus-buy decision matrices, plant-layout checklists for inert handling, and life-cycle cost models that isolate the most impactful operational levers (gas recirculation, water recycling, automation and ATEX compliance).
-
Risk and regulatory matrix: Practical mitigation steps for process safety, export controls, and materials compliance accompanied by an implementation timeline suitable for 12–24 month programs.
-
M&A and partnership radar: Early-warning indicators and criteria to evaluate targets — from IP-rich niche atomizer developers to capacity-oriented producers — aligned to CR/IRR thresholds that corporate development teams can apply.
Macro trends that will shape supplier and buyer strategy
-
Demand pull from additive manufacturing and advanced powder metallurgy continues to be the primary growth engine. However, growth is heterogeneous: premium spherical powders for aerospace and critical defense applications require vacuum and inert-atmosphere atomization, while larger-volume industries tolerate water-atomized or irregular powders for sintering and MIM.
-
Operating-cost pressure centers on consumables and utilities. Inert gases (argon and nitrogen) account for a meaningful share of runtime cost in gas-atomization setups; large facilities that implement recirculation and gas recovery systems drive step-change improvements in economics.
-
Water atomization remains relevant for high-throughput, lower-cost powder needs; ultra-high pressure water systems with closed-loop recycling are increasingly viewed as an environmental and cost-differentiating feature.
-
Safety and atmospheric control: Vacuum/inert melting and atomization are necessary to meet oxygen- and hydrogen-spec targets for high-performance alloys. ATEX-compliant design and explosion-risk mitigation are preconditions for commercial-scale reactive metal processing.
-
Integration points are becoming strategic: Closed-loop powder handling (from atomizer to sealed transport to AM printer hoppers) and direct-fill innovations are shortening supply chains and creating lock-in for suppliers that can certify inert logistics.
Competitive landscape — how to read incumbent and emerging players
The atomizer OEM ecosystem is a mix of deep-technology incumbents, specialized niche equipment suppliers, and vertically integrated material producers. Market structure shows moderate concentration: our analysis measures the top-three suppliers’ combined share at a mid-30s percentage and the top-five near the high-40s. This implies opportunity for scale players, but also room for specialized vendors to capture premium segments.
-
ALD Vacuum Technologies (Germany): Leader in vacuum induction melting and inert gas atomization (VIGA). Strategically positioned for high-purity, spherical powders demanded by aerospace and critical AM supply chains. Competitive advantage: proven VIGA platforms and process control for ultra-low interstitials.
-
SMS group and large European OEMs: Offer integrated plant solutions and strong engineering services for full-line plant builds — attractive to buyers seeking turn-key, tightly controlled production environments.
-
Retech, Arcast, and specialist U.S. suppliers: Offer diverse atomization technologies (plasma, rotating-electrode, centrifugal, ceramic induction), which makes them well suited for reactive and refractory metals. Their modular technology suites support custom alloy development and research-to-production scaling.
-
BluePower, TOPCAST, Atomising Systems, and several Asian vendors: Serve small- to medium-batch producers with a focus on cost-efficient gas/water/ultrasonic systems. Attractive for localized supply and rapid turn-up of powder lines.
-
Laboratory-scale and R&D OEMs (AMAZEMET, Phoenix Scientific): Provide smaller, highly controllable atomizers ideal for alloy development and qualification work — a strategic partner class for OEMs planning new-material roadmaps.
-
Chinese equipment makers (Hasung, SuperbMelt, Taeantech, CDOCAST): Offer cost-competitive solutions for high-volume, commodity powders and are increasingly active in export markets and downstream aftermarket services.
Signals from recent deal and capacity moves (2024–mid–2025)
-
Supply-chain innovation: A 2025 partnership enabling direct filling from atomizer to AM printer hopper illustrates how logistics and inert handling are becoming commercial differentiators.
-
Capacity ramping for strategic alloys: Announced expansions of EIGA capacity for titanium and refractory alloys signal accelerating supply-side investments aligned to anticipated demand from aerospace and high-performance manufacturing.
-
Commercial deployments for defense and industrial use-cases reinforce that mid-scale inert gas atomizers hit a sweet spot between R&D proof-of-concept and full production volumes.
-
Rapid production scaling examples — including multi-hundred-percent increases in nickel powder output following atomizer commissioning — highlight that equipment upgrades can unlock substantial volume increases, stressing the importance of modular, scalable plant design.
Strategic recommendations for executives in 2026
-
Prioritize plant designs that reduce consumables intensity: Invest in gas-recovery and water-recycling subsystems where payback meets your cost-of-capital thresholds.
-
Embed regulatory design early: Integrate ATEX and atmosphere-control requirements into procurement specs to avoid retrofit delays and cost overruns.
-
Build modular capacity with upgrade paths: Opt for atomizer technologies that allow staged uptime (R&D → pilot → commercial) to match demand without overcommitting capital.
-
Use vendor scorecards to shortlist based on long-term serviceability, spare-parts strategy, and digital monitoring capabilities — not only on purchase price.
-
Consider strategic partnerships for closed-loop logistics: Direct-fill and inert storage arrangements are emerging as client expectations for high-purity powders.
-
Adopt a differentiated materials roadmap: Hedge between commodity powders and specialty alloys; prioritize in-house qualification capability or secure exclusives with specialist atomizer OEMs for alloy IP protection.
How PW Consulting’s report supports your 2026 playbook
Our full study supplies the granular analytics and execution tools necessary to move from strategy to contract: proprietary CAPEX/OPEX templates, supplier comparative matrices, process-safety checklists, and scenario-based demand modelling. We deliberately present a “teaser” level of insights here to demonstrate analytical depth while reserving the complete sub-segment tables, regional splits, and vendor-level financials for the full report and client briefings.
For procurement directors, plant engineers, and corporate development teams preparing decisions in 2026, the questions are not whether the market grows — the macro trajectory is clear — but how you position capacity, protect margin against consumables inflation, and tie atomizer selection to long-term materials strategy. PW Consulting’s Metal Powder Atomizer Market report converts that strategic thesis into a pragmatic implementation roadmap.
Contact PW Consulting to obtain the full report, request the executive dataset, or arrange a tailored briefing that maps our findings directly to your 2026 investment and sourcing calendar.
For detailed analysis of this topic, please visit the official page: Metal Powder Atomizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com