

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Image Signal & Vision Processor Market Poised for 9.16% CAGR Through 2032

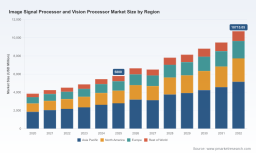
Image Signal Processor and Vision Processor Market — Strategic Outlook for 2026
PW Consulting’s latest market brief on Image Signal Processors (ISPs) and Vision Processors provides an executive-grade, actionable perspective for leadership teams planning capital allocation, product roadmaps, and go-to-market (GTM) moves in 2026. The market has transitioned from early commoditization to a differentiated, software-enabled battleground: total industry revenue grew materially through the early-2020s and, using 2025 as a base year, is forecast to expand at a mid-to-high single‑digit CAGR over the 2026–2032 forecast horizon. That growth trajectory creates both opportunity and operational complexity for semiconductor suppliers, OEMs, Tier‑1 integrators, and systems companies building vision-enabled products.
Image Signal Processor And Vision Processor Market
Why this report matters for 2026 decisions
Executives face three simultaneous forces in 2026: accelerating edge AI capabilities that reframe the value of on-chip ISPs and vision accelerators; evolving supply‑chain and trade risks that change sourcing economics; and shifting buyer expectations that favor software-defined imaging and data‑centric value propositions. Our analysis synthesizes these forces into prioritized, time‑bound recommendations designed for commercial, product, and procurement leaders. The report translates macro market momentum — which sees the industry moving from multi‑billion dollar scale in 2025 into a substantially larger market through the forecast period — into practical decision points that should influence budgets, partner selection, and M&A thinking this year.
Image Signal Processor And Vision Processor Market
What the report contains (practical deliverables)
- Market sizing and five‑way forecast model (base year 2025; forecast period 2026–2032) with scenario outputs to stress-test policy, lead‑time, and price‑pressure variables.
- Technology and product map that explains where integrated ISPs, dedicated vision processors, and sensor‑level intelligence deliver differentiated ROI across use cases.
- Vendor scorecards and capability matrices focused on silicon architecture, software stacks, ecosystem support, and manufacturability risks.
- Go‑to‑market playbooks for suppliers and OEMs — including channel strategies, certification roadmaps for safety‑critical markets, and pricing benchmarks.
- Supply‑chain risk matrix with mitigation options (multi-geography sourcing, life‑of‑part planning, and inventory hedging) aligned to procurement lead‑times.
- Strategic M&A and partnership scenarios with valuation sensitivity for technology tuck‑ins versus scale acquisitions.
Core market dynamics shaping 2026 strategy
Three technology and market trends are decisive for 2026 planning:
Image Signal Processor And Vision Processor Market
- Edge AI integration: Suppliers are moving beyond raw ISP performance to combine imaging pipelines with on‑chip AI accelerators. This enables real‑time multi‑stream processing, dynamic HDR, and software‑driven image enhancement at the edge — capabilities that increasingly determine system‑level differentiation.
- Software‑defined imaging: The emergence of AI‑first ISPs and software pipelines lets manufacturers deliver continuous image quality improvements post‑shipment. This raises the strategic value of firmware, toolchains, and cloud‑assisted update mechanisms as revenue drivers and retention levers.
- Regulation and supply friction: New trade and tariff actions, expanded export controls, and constraints on processed critical minerals have moved from risk scenarios to operational realities in early 2026. Coupled with semiconductor lead times that have expanded for certain device families, these factors require near‑term procurement and product planning adjustments.
Taken together, these dynamics compress design cycles and increase the premium paid for validated, software‑rich platforms that shorten time‑to‑market for vision applications.
Competitive landscape — strategic postures and tactical implications
The market’s competitive topology includes diversified semiconductor houses, specialty ISP IP suppliers, and sensor vendors embedding intelligence at the focal plane. Key strategic observations from our vendor analysis:
- Ambarella is executing a classic edge‑AI play: advanced process nodes, integrated AI accelerators, and multi‑stream 8K capabilities position it as a preferred partner where compute‑per‑watt and video throughput are decisive (e.g., security, high‑end robotics, select automotive functions).
- Large mixed‑signal and systems suppliers (e.g., manufacturers with established MCU/MPU lines) emphasize ecosystem breadth and safety/functional‑safety credentials — strategic assets for automotive and industrial customers who prioritize long product lifecycles and certification support.
- Connectivity and mobile‑centric SoC vendors differentiate through integrated AI subsystems and developer tooling that reduce integration overhead for consumer and IoT use cases.
- Sensor vendors are accelerating sensor‑level intelligence (smart sensors) to capture value earlier in the imaging chain; this shifts bargaining power in some product segments toward combined sensor+ISP offerings.
- IP vendors and niche specialists are commercializing AI‑based ISP pipelines that can be licensed to OEMs; this creates an alternative to platform dependency and can accelerate differentiation via algorithmic innovation.
Recent product moves underscore the pace of innovation: high‑performance edge SoC launches and the debut of full AI‑based ISP pipelines at major industry events signal that 2026 will be a pivotal year for platform standardization versus bespoke differentiation.
Strategic actions for 2026: three priority plays
- Secure multi‑vector supplier relationships. Assume longer and more variable lead times for some IC families and factor tariff/exemption scenarios into sourcing decisions. Qualify secondary suppliers and pursue long‑lead buys for safety‑critical programs.
- Invest in software and IP layers. Hardware alone will not sustain premium pricing. Prioritize middleware, image‑quality toolchains, and cloud/OTA mechanisms that turn ISPs into subscription and services anchors.
- Adopt a segmented GTM: differentiate between fast‑moving consumer/IoT segments (where time‑to‑market and developer ecosystem win) and regulated segments (automotive/industrial), where safety, qualification, and lifecycle support command higher total contract value and longer sales cycles.
Supply‑chain, policy, and risk considerations
Policy decisions and raw‑material constraints in early 2026 materially affect cost structure and procurement risk. Import tariffs on advanced computing chips and expanded export control regimes can increase landed costs and introduce licensing complexity for cross‑border projects. Processed critical‑mineral import actions add volatility to input pricing and supplier availability. In parallel, certain semiconductor lead times have trended higher, requiring program managers to re‑baseline BOM timelines and safety stock policies. The report provides decision trees to help teams quantify tradeoffs between localizing production, redesigning for alternative nodes, or using IP licensing to reduce dependence on contested supply paths.
How to use the full PW Consulting report
Our full report is designed as a working tool for 2026 planning cycles. It contains:
- Extensible financial models you can adapt to company‑specific volume and pricing assumptions.
- Vendor scorecards that translate product claims into operational metrics (toolchain maturity, reference designs, lifecycle commitments, and warranty/certification posture).
- Scenario playbooks that quantify outcomes under tariff, export‑control, and lead‑time stress paths — enabling procurement and product teams to set contingency thresholds in Q1 and Q2 of 2026.
- Actionable M&A and partnership frameworks to help corporate development teams prioritize targets and structure earnouts tied to IP and software delivery milestones.
We intentionally present this executive summary as a strategic “trailer”: it demonstrates the depth of our analysis and the practical angles we take, while reserving granular segment breakdowns, regional and application‑level share tables, and vendor financial comparatives for the full report and accompanying datasets. That level of detail is necessary for transaction diligence, supplier audits, and program‑level pricing — and is available through PW Consulting’s full deliverable.
Final recommendations for leadership teams
For 2026, treat the ISP and vision processor market as both a technology race and a supply‑chain contest. Prioritize decisions that (1) lock in validated silicon and software platforms for your priority use cases, (2) de‑risk supply through multi‑sourcing and inventory strategies keyed to lead‑time signals, and (3) build software/IP assets that convert one‑time silicon sales into recurring value streams. Companies that align procurement, product, and commercial teams around these imperatives will convert the market’s projected growth into defensible, margin‑accretive positions.
To access the full report, detailed vendor benchmarking, and the interactive forecast model that supports these recommendations, visit our official PW Consulting report page and request the complete dataset and executive briefing.
For detailed analysis of this topic, please visit the official page: Image Signal Processor And Vision Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com