

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Heavy Equipment Monitoring System Market to Reach USD 8,888.96 Million by 2032

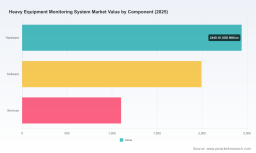
Heavy Equipment Monitoring Systems: A Strategic Preview for 2026 Decision-Makers
Executive summary
As capital expenditure cycles restart and digital transformation pressures intensify across construction, mining, agriculture and related industries, heavy equipment monitoring systems are moving from optional to mission-critical. PW Consulting’s latest market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—finds the global market reaching approximately USD 5,535.6 Million in 2025 and projected to approach USD 8,888.96 Million by 2032, growing at a compound annual growth rate of 7.0% across the forecast period. This growth reflects rising fleet electrification and automation, tighter health-and-safety and emissions regulations, and an expanding appetite for operational intelligence that converts machine telemetry into predictable uptime and lower total cost of ownership.
Heavy Equipment Monitoring System Market
Why this matters for 2026 strategic choices
-
Investment timing: Buyers and asset owners must balance immediate uptime gains from retrofit telematics against longer-term platform bets embedded by OEMs in next‑generation equipment.
Heavy Equipment Monitoring System Market -
Vendor selection: Platform openness, data standards compliance, and multi‑OEM interoperability will determine which solutions scale across mixed fleets.
Heavy Equipment Monitoring System Market -
Regulatory compliance as a revenue driver: New and evolving mandates on occupational exposures and cabin air quality create near‑term demand for integrated environmental monitoring.
Market trajectory and practical implications
The market’s steady rise—evident in the recent baseline and forecast figures—signals a maturing category in which hardware reliability, software analytics and service delivery converge. For enterprise decision-makers, the implications are operational and financial. Projects that deploy robust monitoring frameworks will see measurable reductions in unscheduled downtime, fuel consumption and unsanctioned idling. Financial models embedded in the PW Consulting report demonstrate payback horizons that vary by use case and deployment approach; however, a consistent finding is that flexible architectures which decouple sensor hardware from analytics subscriptions unlock the most attractive mid‑term ROI.
Key industry dynamics shaping 2026 strategies
-
Standards and regulation: ISO 23725 (2024) and related standardization work are lowering the integration cost of heterogeneous fleets by defining interoperability for autonomous systems and fleet management. In parallel, occupational safety updates—such as revised silica exposure limits phased in across mining jurisdictions—are translating into procurement requirements for environmental and exposure monitoring capabilities embedded within equipment telemetry.
-
Hardware dependencies: The category remains dependent on core components—GPS receivers, vibration/temperature/pressure sensors, and telematics control units (TCUs)—where supply chain continuity and ruggedization standards (IP ratings, EMC robustness) are critical selection criteria for jobsite longevity.
-
Service evolution: Buyers are shifting from transactional device purchases to outcome-centric contracts that pair sensors with predictive maintenance, utilization analytics, and integrated field service networks.
Strategic playbook for corporate leaders in 2026
-
For OEMs: Prioritize modular telematics stacks that allow customers to choose between OEM-hosted suites and third‑party analytics marketplaces. Retain data ownership and establish clear, commercially viable APIs—doing so preserves aftermarket revenues while enabling ecosystem growth.
-
For fleet owners/operators: Define a three‑year interoperability roadmap. Start with a proof-of-value on high‑impact equipment classes, validate predictive alerts against maintenance records, then scale via a device-agnostic platform to avoid vendor lock‑in.
-
For systems integrators and software vendors: Differentiate through verticalized analytics—mining, dredging, forestry and precision agriculture require distinct telemetry-to-action mappings and compliance workflows.
-
For financiers and insurers: Leverage operational telematics as collateral enhancement—verified uptime and preventative maintenance logs materially reduce risk and support innovative insurance products tied to equipment health.
What the PW Consulting report delivers (practical toolkit)
The report is intentionally operational. It moves beyond high‑level forecasts to give practitioners tools they can use immediately in vendor selection, procurement and deployment. Key inclusions:
-
A transparent market-sizing methodology and scenario modeling engine for sensitivity to adoption rates, hardware cascade effects, and service pricing.
-
A vendor evaluation framework combining technical fit, commercial terms, cybersecurity posture and field service coverage.
-
Implementation playbooks: stepwise deployment checklists, data governance templates, and example SLAs for uptime, data latency and support response times.
-
Use-case playbooks: prescriptive KPIs and dashboard examples for maintenance optimization, utilization-based asset deployment, and emissions/compliance monitoring.
-
ROI calculators and total cost of ownership templates tailored to major equipment categories and retrofit vs. OEM‑integrated pathways.
-
Regulatory mapping: actionable guidance on aligning system capabilities with ISO and occupational health standards, including recommended sensor configurations to support compliance reporting.
Competitive landscape—practical takeaways
The market is characterized by a mix of global OEM platform plays, telematics specialists and agile software-first entrants. Below are strategic profiles and what each archetype signals for buyers and partners.
-
Caterpillar Inc. (Peoria, Illinois, USA — https://www.cat.com)
With Cat Product Link and VisionLink, Caterpillar emphasizes deep integration between hardware and fleet analytics. Strengths include large installed base and service networks. Strategic implication: customers seeking one-stop lifecycle support will find value in OEM‑integrated systems, but should contract explicitly on data access and exportability to avoid integration friction with third‑party analytics. -
Komatsu Ltd. (Tokyo, Japan — https://www.komatsu.com)
Komatsu’s KOMTRAX remains a robust choice for OEM‑grade telemetry focused on operating hours, fuel and machine condition. Strategic implication: Komatsu buyers benefit from OEM-aligned warranty and parts optimization—consider hybrid strategies that layer neutral analytics over OEM feeds for cross‑fleet visibility. -
John Deere (Moline, Illinois, USA — https://www.deere.com)
JDLink’s integration with the John Deere Operations Center provides strong data continuity across precision agriculture and construction equipment. Strategic implication: vertical specialization is Deere’s advantage—partners in agriculture and fieldwork should prioritize Deere’s ecosystem where precision and agronomic data fusion matter. -
Volvo Construction Equipment (Gothenburg, Sweden — https://www.volvoce.com)
Volvo’s CareTrack emphasizes fuel efficiency and service planning. Strategic implication: operators optimizing sustainability metrics should evaluate Volvo’s telemetry for emissions and fuel analytics, while negotiating multi‑OEM data strategies. -
ORBCOMM, Trimble, Hexagon, Topcon, Samsara, Teletrac Navman
These providers span rugged telematics hardware to site productivity and fleet management platforms. Strategic implication: choose specialists for mixed-fleet, harsh-environment needs (ORBCOMM, Nova Mobile Systems), and software players (Samsara, Trimble) when rapid deployment and cloud-first analytics are priorities. -
Nova Mobile Systems, HCSS, Geotab
Nova Mobile and HCSS offer construction-focused telematics with ruggedized hardware or purpose-built analytics; Geotab adds cross‑OEM aggregation expertise via standards like AEMP 2.0. Strategic implication: integrators and contractors should use these vendors to bridge data from legacy fleets into modern analytics stacks.
Near-term catalysts and watchlist for 2026
-
Trade-show product releases: Recent new machine‑control and safety innovations announced at CONEXPO‑CON/AGG 2026—including 3D machine control features and AI‑based awareness systems—will accelerate expectations for integrated monitoring and onsite automation.
-
Regulatory enforcement: Phased occupational exposure limits and cabin air quality standards will push buyers toward devices capable of environmental monitoring and long‑term logging.
-
Interoperability standards: Widespread adoption of ISO 23725 and related protocols will be a structural enabler for multi‑vendor solutions and, over time, compress margins on closed, proprietary offerings.
-
Supply chain resilience: Availability and sourcing of specialized sensors and TCUs will affect rollout schedules; procurement teams should pre‑qualify multiple suppliers and build inventory buffers for critical components.
How to use this intelligence in 2026 planning
PW Consulting’s report is designed as a decision support asset rather than a static market map. Use it to:
-
Build a procurement RFP that enforces data portability, uptime SLAs and measurable business outcomes.
-
Prioritize pilot deployments on equipment classes with the highest downtime cost per hour and the clearest maintenance signal from telemetry streams.
-
Negotiate lifecycle contracts with tiered pricing that align vendor incentives with reduced failure rates and fuel consumption.
Next steps and where to get the full intelligence
This briefing highlights the strategic contours and operational levers that matter for 2026. For the detailed segmentation tables, regional and end‑use breakouts, vendor scorecards, full scenario models and downloadable ROI calculators that underpin our recommendations, access the full PW Consulting Heavy Equipment Monitoring System Market report on our website. The full report contains the granular evidence and executable artifacts that procurement teams, CIOs, and fleet managers will need to convert market insight into measurable performance gains.
PW Consulting stands ready to support custom workshops, vendor due diligence, and deployment roadmaps informed by the report’s data and practical toolset—contact us to operationalize your 2026 heavy equipment monitoring strategy.
For detailed analysis of this topic, please visit the official page: Heavy Equipment Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com