

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ocean Wave Energy Technology Market Poised to Surge at a 16.52% CAGR in 2026–2032 Forecast

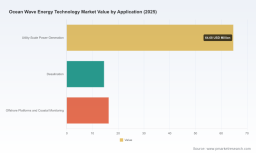
Ocean Wave Energy Technology Market — Strategic Brief for 2026 Decisions
Executive summary
PW Consulting’s new market study on Ocean Wave Energy Technology maps a maturing but still early commercial sector at a decisive inflection point. Between 2020 and 2025 the global market more than doubled from a modest base, reaching USD 95.5 Million in 2025. Our forecast shows continued rapid expansion through the coming decade, with an expected market value of USD 112.26 Million in 2026 and a compound annual growth rate (CAGR) of 16.52% for the 2026–2032 forecast window, culminating in a projected USD 278.49 Million by 2032.
Ocean Wave Energy Technology Market
This brief highlights the parts of our analysis most material for executive decisions in 2026: where to allocate capital, which technology pathways mitigate first-of-kind risks, how policy and procurement mechanisms are beginning to change commercial timelines, and which competitive playbooks are proving most effective in advancing grid-connected deployments. In keeping with the “trailer” principle, we present high-value strategic insights while reserving device-level economics, region-by-region demand matrices, and proprietary LCOE models for the full report.
Ocean Wave Energy Technology Market
Why 2026 is a strategic hinge year
-
Public funding and procurement are shifting from R&D to deployment-readiness. Large grants and utility procurement pilots that were once theoretical are now producing offtake pathways that can anchor early commercial rollouts.
Ocean Wave Energy Technology Market -
Project demonstrators are moving from single-unit pilots to array-level trials. This changes the unit economics dynamics (economies of scale in installation, O&M, and electrical balance of plant) and shortens the path to bankable revenue streams.
-
Material and manufacturing advances — notably wider adoption of filament-wound GFRP composites and modularized power take-off systems — are lowering capital intensity and improving survivability, which together compress capital deployment risk.
What our report delivers (practical, decision-grade content)
The full PW Consulting report is structured to support board-level and transaction teams during 2026 planning cycles. It contains:
-
Market sizing and scenario modeling — multi-horizon forecasts with downside and upside pathways that stress-test sensitivity to CAPEX declines, deployment rates, and offtake terms.
-
Technology readiness and pathway maps — device-level technology readiness assessments (TRLs), failure-mode analyses from field programs, and conversion-efficiency benchmarks to compare device classes without revealing proprietary device economics in this brief.
-
Practical procurement and contracting templates — model power purchase agreement (PPA) clauses, force majeure and survivability warranties, and O&M contract structures tailored to marine environments.
-
Levelized cost and cashflow models — modular Excel models that capture CAPEX/OPEX schedules, availability assumptions, and debt-equity finance structures; these are provided with sensitivity toggles in the paid deliverable.
-
Supply chain and manufacturing playbooks — sourcing strategies for composites, PTO components, and mooring/installation services, plus time-to-scale maps for supply chain ramp.
-
Regulatory and incentives atlas — jurisdictional snapshots of permitting timelines, grid interconnection bottlenecks, and public funding instruments critical to 2026 deployment decisions.
-
Commercial due-diligence dossiers — vendor profiles, technology comparison matrices, and a shortlist of investment-graded prospects based on survivability, O&M intensity, and IP defensibility.
Competitive landscape — what matters for partners, investors and buyers
The industry remains fragmented, with concentration metrics indicating a modest leading cohort: the top three vendors account for approximately 31.4% of identifiable market activity, and the top five about 42.85%. That distribution suggests room for consolidation and scale advantages but also meaningful opportunity for specialized technology leaders.
-
Eco Wave Power (Sweden / Tel Aviv ops) — A commercial pioneer in onshore floaters integrated with existing marine structures. Recent milestones include the successful completion of a Port of Los Angeles pilot (April 2026) and operation of a U.S. onshore project launched in 2025. Their demonstrated OPEX discipline — operational expenditures below the 4% of CAPEX threshold in an Israeli project — signals that onshore-integrated designs can achieve competitive operating profiles when coupled with automation and land-based conversion units.
-
CorPower Ocean (Sweden) — Focused on compact point absorbers (C4/C5 family) with bio-inspired hydraulic PTO systems. The deployment of a commercial-scale unit at Aguçadoura (Portugal) and survivability validation through intense storm events position CorPower as a candidate for arrays in exposed, high-energy sites. Their use of spherical hull geometries and advanced composites points to a route for high power-density devices.
-
Carnegie Clean Energy (Australia) — A technology-first player combining wave conversion with desalination capabilities. The hybrid value proposition reduces merchant power exposure for projects targeting remote or water-stressed markets and should be considered by developers pursuing multi-revenue streams.
-
Ocean Power Technologies (United States) — With a legacy of PowerBuoy deployments and PTO innovations, OPT’s playbook emphasizes reliability for both utility-connected and remote power markets. Their trajectory underscores the importance of mature PTO architectures in de-risking merchant deployments.
-
AW-Energy, Mocean Energy, Oscilla Power, CalWave, ORPC, Seabased, NoviOcean, Marine Power Systems — Collectively, these firms represent the diverse technical approaches in the market: oscillating surge devices, large utility machines, advanced drivetrains, submerged multi-DOF systems, cross-flow turbines adaptable across currents and waves, seabed linear generators, and hybrid platforms. Each brings differentiated IP and project specialization that will determine partnership value in 2026 procurement rounds.
Regulatory, procurement and testing inflection points
-
Public funding is being reallocated toward deployment-readiness. The U.S. Department of Energy’s Oceans of Opportunity program (multi-year funding envelope) and the PacWave test-facility initiatives are converting early-stage R&D into real-world procurement pathways.
-
Notable procurement momentum: the Bonneville Power Administration signed a pioneering PPA with the PacWave facility (administered by Oregon State University) to purchase up to 20 MWh per hour for 2026–2030. This kind of utility-level commitment materially increases the bankability of nearby projects and establishes reference pricing for future tenders.
-
Test-site availability is a gating factor. PacWave South’s scheduled prototype hosting in summer 2026 and other instrumented testbeds create a limited window for firms to validate array-level operations and secure early offtake or joint-development agreements.
Key strategic implications for 2026 corporate planning
For executives and investors, the pathways to capture value in 2026 fall into three priority areas:
-
Secure credible offtake and test-site access now. Utility agreements and test-facility allocations will be constrained through 2026. Developers and OEMs should prioritize pipeline contracts and instrumented deployments that produce the operating data investors require.
-
Design for cost-reduction and survivability together. Material choices (e.g., filament-wound GFRP), modular PTO elements, and automation of control/diagnostics are the most effective levers to compress both CAPEX and OPEX. Our casework shows that automation and improved data fidelity materially reduce O&M uncertainty and insurer reluctance.
-
Layer revenue streams to shorten payback. Co-located desalination, hybridized marine platforms, and grid-backed capacity payments materially improve project bankability versus stand-alone merchant power in early markets.
-
Establish strategic alliances across the value chain. Partnerships with heavy lift and subsea cable providers, composite manufacturers, and local port authorities can shave months from permitting and mobilization timelines in 2026 procurement cycles.
-
Prepare for an acceleration of M&A and consolidation. Given the current concentration metrics and the forecast growth trajectory, expect selective consolidation: buyers will target firms with field-proven units, IP in PTOs, or unique route-to-market advantages (for example, onshore integration or desalination hybrids).
An actionable playbook — five pragmatic moves for 2026
-
Run a two-track pilot plan: one grid-connected test targeting array behavior and one commercial demonstration that secures early revenue via a utility PPA or municipal desalination contract.
-
Negotiate staged procurement agreements with suppliers that include price and delivery triggers tied to cumulative deployed capacity.
-
Mandate survivability and recovery drills as part of any acceptance test to reduce insurance and lender conditions precedent.
-
Prioritize deployments that create reusable learning — instrument systems to capture O&M, fatigue, and electrical performance data to accelerate subsequent deployments and reduce risk premia.
-
Build regulatory engagement plans in parallel with technical pilots—early engagement materially shortens permitting tails and can unlock local incentives.
Concluding perspective and call to action
Ocean wave energy is transitioning from pioneering pilots to structured commercial pathways. Our 2026 view is clear: the sector’s growth trajectory is robust (16.52% CAGR, 2026–2032) but success will hinge on carefully sequenced actions that derisk deployments and monetize early demonstrations. Companies that align technology choices with procurement realities, secure offtake or hybrid revenue, and pursue disciplined supply-chain scale will be the natural winners in the coming cycle.
For boards and strategy teams preparing 2026 capital allocation and M&A decisions, PW Consulting’s full report provides the device-level economics, jurisdictional maps, and transaction templates necessary to move from intent to investable project. To access the complete dataset, sensitivity models, and proprietary vendor dossiers, contact PW Consulting or visit our report page for the Market Research: Ocean Wave Energy Technology Market — the detailed intelligence that will inform bankable decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ocean Wave Energy Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com