

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bluetooth Audio IC Market Poised for Rapid Growth with 11.85% CAGR Through 2032

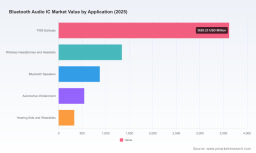
Bluetooth Audio IC Market — Strategic Outlook for 2026: PW Consulting Market Brief
As companies map product roadmaps, supply chains and M&A pipelines for 2026, the Bluetooth audio IC market is moving from incremental evolution to strategic inflection. PW Consulting’s new market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes commercial, technical and geopolitical forces to deliver decision-grade guidance. Our top-line view: the market has more than doubled in scale over the past half-decade and is projected to continue expanding at a high single-digit to low double-digit pace — a compounded annual growth rate of 11.85% through 2032 — creating both margin expansion opportunities and competitive risk for OEMs, chipset vendors and system integrators.
Bluetooth Audio Ic Market
Executive snapshot
Key macro trajectory: the market grew from roughly USD 3.8 billion (2020) to USD 6.72 billion (2025) and is forecast to reach approximately USD 7.76 billion in 2026 on its path toward roughly USD 14.72 billion by 2032. That trajectory implies a sustained investment runway for audio silicon, firmware ecosystems and services that support feature-rich hearables, speakers and automotive gateways. Importantly, concentration metrics show a market where the top three vendors control the majority share and the top five consolidate further — a structure that shapes negotiation leverage across the value chain.
Bluetooth Audio Ic Market
What the report delivers — actionable, board-ready intelligence
- Integrated market sizing and growth scenarios (conservative, base, upside) from 2026–2032, with sensitivity to adoption curves for LE Audio and other key technologies.
- Vendor scorecards and capability matrices that assess RF performance, low-power architectures, codec support, AI/ANC enablement, software ecosystems and time-to-market readiness.
- Supply chain and manufacturing risk maps covering wafer process lead times, packaging dependencies, OSAT capacity and the impact of export controls on RF IC sourcing.
- Commercial playbooks for OEM procurement teams — supplier selection frameworks, contract clauses for supply continuity, and inventory hedging strategies tailored to medium-term demand volatility.
- Technology adoption roadmaps that map codec/standard transitions (including LE Audio and LC3), interoperability bottlenecks, and recommended migration strategies for incumbent product lines.
- Investment decision support — M&A screening criteria, JV models, and payback simulations for new product platforms and software-as-a-service extensions.
- Regulatory and tariff scenario analysis quantifying potential margin and cost-to-serve impacts under differing trade-policy and export-control environments.
Competitive landscape — who matters and why
The market is best understood as a contest between silicon incumbents with deep RF and audio-software IP, agile system-on-chip specialists and diversified analog/microcontroller players. PW Consulting profiles the strategic positioning of the critical vendors that will shape supplier choices in 2026:
Bluetooth Audio Ic Market
- Qualcomm (San Diego, CA, USA) — A market leader offering high-performance audio SoCs (QCC series) with integrated Snapdragon Sound stack, premium codecs and broad ecosystem partnerships. Their focus on premium TWS and CE segments continues to set a performance bar for latency, multi-device support and differentiated audio processing.
- Realtek Semiconductor (Hsinchu, Taiwan) — Noted for cost-optimized, power-efficient SoCs tailored to high-volume TWS and consumer audio products. Strength lies in price/performance balance and high-yield manufacturing partnerships.
- Airoha Technology (Zhubei City, Taiwan) — Focused on premium TWS silicon with strong AI-based noise-cancellation and low-latency solutions. Recent certification milestones underscore a push toward premium hearables.
- BES Technic (Shanghai, China) — Known for high-fidelity audio solutions and rapid product sampling cycles, BES has positioned itself as an audio-first silicon vendor with aggressive time-to-market strategies.
- Nordic Semiconductor (Trondheim, Norway) — A leader in Bluetooth LE-enabled SoCs with early adoption of LE Audio and LC3 codec support, targeting hearables and connected speaker markets with robust software stacks.
- Espressif Systems (Shanghai, China) — Offers integrated Wi‑Fi/Bluetooth platforms commonly used in IoT speakers and audio-enabled appliances; strong in developer ecosystems and module-level integration.
- Texas Instruments (Dallas, TX, USA) — Provides low-power audio-capable SoCs with strong analog front-end expertise and long-term reliability focus for industrial and automotive segments.
- STMicroelectronics (Geneva, Switzerland) — Positions Bluetooth-capable microcontroller platforms for audio gateway and embedded headphone applications, emphasizing system integration and safety-qualified variants.
Recent vendor moves reinforce market dynamics: new Bluetooth LE Audio product introductions, ultra-low-power sampling programs, and certification progress are accelerating feature parity while creating differentiation through software and ecosystem partnerships. Our report contains side-by-side benchmarking and a vendor-roadmap heatmap that boards and product leaders can use to prioritize partners.
Structural forces that will determine winners in 2026
- Standards and codecs: LE Audio and the LC3 codec are now baseline requirements for many next-generation designs. The timing and cost of migrating legacy platforms will shape vendor selection and R&D budgets.
- Geopolitics and regulatory friction: Export controls on advanced manufacturing equipment and tariff regimes have tangible supply-chain consequences. Companies must evaluate sourcing geographies and dual-sourcing strategies to maintain continuity and margin.
- Foundry and process realities: Supply-side stability for mature CMOS nodes used in Bluetooth audio ICs has improved but lead times for key process nodes remain material — our analysis notes stabilized lead times in the mid‑teens of weeks for prevalent nodes, creating procurement constraints that require disciplined component forecasting.
- Consolidation dynamics: With the top-three and top-five concentration levels indicating significant market power among incumbents, smaller vendors must compete on niche capabilities (latency, ANC, price) while larger vendors wield negotiation leverage with OEMs.
- Software-centric differentiation: As hardware parity narrows, firmware, codecs, and cloud-enabled audio services become primary profit levers. The ability to deliver post-sale feature upgrades and ecosystem interoperability will be decisive.
Strategic implications for 2026 executive decisions
PW Consulting translates market facts into concrete, prioritized actions for leaders planning 2026 strategies:
- R&D and product roadmaps — Prioritize LC3/LE Audio capability and robust software update pathways. Allocate capex to modular reference designs that shorten time to market while protecting IP portability across foundries.
- Sourcing and procurement — Implement a dual-axis sourcing strategy: one axis focused on mitigating geopolitical/tariff risk, the other on securing lead-time guarantees for critical components. Our report provides supplier-tiering and procurement playbooks that reduce supply surprise risk.
- M&A and partnership moves — Use vendor scorecards and gap analyses to determine whether inorganic growth or strategic partnerships better accelerate capabilities in ANC, AI audio processing and platform software.
- Commercial and pricing — Reassess ASP and bundling strategies in markets where software features (spatial audio, developer SDKs) command premium pricing; include tariff sensitivity in margin models.
- Regulatory compliance and tax planning — Build scenario models for export controls and tariffs into product-costing systems. Our regulatory scenarios quantify potential margin erosion and provide mitigation pathways.
- Risk management and inventory — Translate forecast volatility into safety-stock policies and rolling three- to six-month procurement commitments for critical silicon families; the report includes worked examples for common product architectures.
How to use this brief in the boardroom
- CEOs and strategy leads — Use the report’s market scenarios to stress-test portfolio choices and prioritize investment across premium vs. volume playbooks for 2026 launches.
- CPOs and procurement heads — Adopt the supplier scorecard and risk matrix to reconfigure sourcing lanes and negotiate contingent supply agreements ahead of new product ramps.
- CTOs and product leaders — Leverage the technology adoption roadmap to set 18–36 month migration targets for codec support, latency budgets and power envelopes.
- CFOs and corporate development teams — Use the provided valuation and payback models to evaluate potential acquisitions, licensing deals and strategic partnerships that accelerate software-enabled monetization.
What we deliberately withhold here — and where to find it
In this brief we present the strategic arcs and decision-relevant synthesis that executives need to frame 2026 initiatives. To maintain its role as a practical acquisition tool and to ensure readers obtain the contract-grade inputs they require, PW Consulting intentionally withholds the granular segment-level tables, region-by-region revenue breakdowns, application-specific percent shares and detailed vendor revenue-by-product models from this public summary. These items — along with downloadable vendor scorecards, BOM-level cost models, and scenario spreadsheets — are included exclusively in the full report package accessible from our report portal.
If your 2026 planning requires negotiation-ready supplier scorecards, supplier-by-feature comparison matrices, or scenario models tailored to your product mix, PW Consulting’s full Bluetooth Audio IC Market report delivers them with the data provenance, assumptions and sensitivity analyses procurement, product and corporate development teams need.
For immediate access to the full report and the supporting analytical toolset, please visit our report page on the PW Consulting website. The full deliverable will equip your team to convert the market’s growth trajectory and structural dynamics into defensible, executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Bluetooth Audio Ic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com