

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Palm Kernel Shells Biomass Market to Reach USD 2,318.88 Million by 2032, Growing at an 8.5% CAGR

Palm Kernel Shells Biomass Market: Strategic Imperatives for Corporate Decision‑Making in 2026
PW Consulting today releases an executive briefing drawn from our forthcoming Palm Kernel Shells (PKS) Biomass Market Report — a tactical guide for executives, traders, and project sponsors preparing decisions across 2026. The PKS market is no longer a niche by‑product story; it has become a commercially material biomass supply chain with clear growth momentum, consolidation dynamics, and regulatory complexity that together will determine commercial outcomes for power generators, industrial heat users, and commodity traders this year.
Palm Kernel Shells Biomass Market
High‑level market trajectory: what the numbers tell you
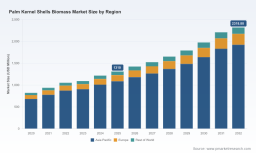
Our topline market model — built on a transparent methodology covering historical years 2020–2025, with a base year of 2025 and a forecast window from 2026–2032 — shows the PKS market more than doubling in scale since 2020 and continuing robust growth through the next decade. Measured in USD (Million), the market grew from a modest baseline in 2020 to an estimated USD 1,310.0 Million in 2025. Under the central scenario, the sector expands at a compound annual growth rate (CAGR) of 8.5% across the 2026–2032 forecast period, reaching a projected market size in the order of USD 2,318.88 Million by 2032.
Palm Kernel Shells Biomass Market
These macro metrics carry three immediate implications for 2026 planning:
Palm Kernel Shells Biomass Market
- Scale matters: growing volumes require re‑thinking logistics, storage, and quality control as a strategic capability rather than an operational afterthought.
- Contract design becomes a competitive advantage: with market growth and periodic supply shocks, firms that secure flexible, sustainability‑certified supply contracts will hold meaningful risk arbitrage.
- Regulatory sensitivity: export levies and service tariff shifts materially alter landed cost at the mill gate — 2026 procurement strategies must explicitly scenario‑test for tax and tariff moves.
Why 2026 is a pivot year for enterprise strategy
Three converging dynamics make this year particularly decisive: persistent demand growth from power generation and industrial heat applications, increased policy attention to bioenergy traceability and sustainability, and rapid capacity moves by strategic suppliers. Our market concentration analysis shows a moderately concentrated supplier base (CR3 ~32.4%, CR5 ~45.8%), indicating that a handful of players already shape traded flows and that scale investments by those players will have outsized influence on spot and contract markets.
Consequence for decision‑makers: 2026 is the optimal window to convert short‑term buying habits into medium‑term supply partnerships and to price in infrastructure options (receival, storage, drying) that protect against seasonal and policy volatility.
Competitive landscape — who to watch
Our competitive analysis maps capacity, certification footprint, and go‑to‑market models across active suppliers and integrated palm groups. Notable market participants and recent moves that should influence sourcing and partnership choices:
- BIO ENECO Sdn Bhd (Eldridge Energy subgroup) — advancing export‑grade PKS capacity and certified supply. Recent capacity expansion and multi‑year offtake align this supplier with large utility and merchant markets that require traceable biomass for co‑firing or dedicated biomass boilers.
- Iwatani Corporation — a long‑standing buyer and distributor that leverages multi‑origin supply links across Southeast Asia and flexible delivery models to power customers in Japan; their approach underscores the utility of diversified shipping points and long‑term supplier relationships.
- Nissin Bio Energy and PT Dharma Satya Nusantara (DSN) — exemplars of integrated mill‑to‑export supply strategies: they offer continuity of feedstock through vertically linked operations, which matters when mills enforce sustainability certification and mill gate allocation.
- CM Biomass and regional specialists — focus on value‑added specifications (size uniformity, low ash, consistent NCV) and product interoperability for co‑firing and downstream carbon products, signaling an adjacent market for PKS beyond direct combustion.
Understanding each supplier’s business model — whether merchant exporter, integrated producer, or value‑added processor — is essential to structuring 2026 contracts. Our full report contains supplier scorecards and negotiation playbooks designed to convert those qualitative differences into commercial terms.
Regulatory and trade dynamics that will shape landed cost
Policy shifts in supplier jurisdictions are already filtering through to global pricing and will be a live factor in 2026 procurement: Indonesian export tax policy continues to link levies to CPO reference prices, with adjustments that directly affect PKS sourcing economics; Malaysia has revised export service tariffs in early 2026. Such adjustments, even when modest on a per‑tonne basis, can change the calculus for sourcing hubs and shipping routing when volumes scale into the hundreds of thousands of tonnes.
Recommended 2026 actions:
- Incorporate tax and tariff stress tests into every supply model — build alternative supply scenarios and pass‑through clauses into contracts.
- Prioritize suppliers with recognized sustainability certifications where offtake destination requires traceability (e.g., Green Gold Label), because certification can be a gatekeeper to premium markets.
- Negotiate flexible delivery windows and shared storage options to smooth price and availability shocks tied to export control changes.
Technical and quality considerations — what buyers must account for
PKS is a by‑product and therefore exhibits variability in calorific value, moisture and ash. Typical specifications that buyers should model into conversion and boiler performance studies include net calorific values in the neighborhood of 15–16 GJ/MT, an ash baseline around 3.5%, and total moisture frequently in the 10–15% band. These parameters are not academic: they determine boiler efficiency, emissions profiles, and handling costs. Our supply and thermal performance overlays translate these technical ranges into impact metrics for LCOE (levelized cost of energy) and industrial heat unit economics.
Actionable 2026 strategic playbook (executive checklist)
- Rebalance procurement mix: secure at least one certified long‑term supplier and maintain short‑term merchant access for flexibility.
- Invest in quality assurance at intake: allocate CapEx for drying or screening if blending target NCV or ash limits are tight for your plant.
- Embed regulatory triggers in contracts: automatic renegotiation or pass‑through mechanisms tied to export levy movements and certification status.
- Pursue co‑investment in logistics where volumes exceed scale thresholds — shared jetties, bonded yards, or rail spurs materially lower landed cost per tonne.
- Plan for circular value: evaluate downstream uses (activated carbon, charcoal) where higher specification PKS can command premium pricing or de‑risk oversupply to combustion markets.
Report contents — what PW Consulting delivers (practical, transaction‑ready)
The full Palm Kernel Shells Biomass Market Report is structured to move readers from insight to action. Core modules include:
- Transparent market sizing and forecast model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario analysis and sensitivity to regulatory levers.
- Supply chain maps and logistics cost curves that convert volume flows into landed cost by port cluster and typical shipping windows.
- Contract and procurement playbooks with redlines, pass‑through clauses, and certification checklists for GGL and other sustainability schemes.
- Thermal performance and co‑firing engineering annexes that translate feedstock spec variability into plant performance and emissions outcomes.
- Competitive intelligence dossiers and supplier scorecards, including recent capacity additions and long‑term offtake arrangements impacting 2026 availability.
- Regulatory tracker and decision trees for major supplier jurisdictions to support active monitoring and rapid scenario re‑pricing.
Note: this briefing intentionally omits granular regional and application split figures and specific per‑region or per‑application revenue amounts; these detailed segmentations and the underlying data tables are available exclusively in the full report and interactive data package.
How corporate leaders should use this report in 2026
Our clients use the PW Consulting PKS report for three immediate use cases:
- Transaction support — due diligence for purchasing contracts, asset acquisitions, and offtake underwriting.
- Operational planning — sizing storage, drying capacity, and KPI thresholds for thermal assets and co‑firing retrofits.
- Policy and risk management — embedding dynamic tax/tariff scenarios into budgeting and hedging strategies.
For executives deciding on investments or contract terms this year, the combination of projected market scale (from an estimated USD 1,310.0 Million in 2025 to a forecasted USD ~2,318.88 Million by 2032 under an 8.5% CAGR) and the current concentration profile means first‑mover advantages in downstream logistics and supplier partnerships are both attainable and consequential.
Recent developments to factor into 2026 negotiations
- BIO ENECO’s capacity expansions and long‑term offtake agreements in 2025–2026 highlight the importance of certified, large‑volume suppliers for long‑term utility contracts.
- High‑visibility awards for co‑firing projects and ongoing port/tariff adjustments across producer countries underline the twin forces of market opportunity and policy vulnerability.
- Technical specifications and product differentiation from processors who target low‑ash, uniform‑size PKS bring potential premium segments into play.
Next steps
PW Consulting has prepared the full analyst package to support transaction teams, procurement leads, and power/industrial plant operators executing in 2026. The complete report contains the segmented data tables, regional flows, supplier scorecards, and contract playbooks referenced above. For executives seeking an expedited advisory engagement (procurement term negotiation, origin due diligence, or techno‑economic modelling for co‑firing retrofits), PW Consulting offers tailored sprints that integrate the report’s datasets into client systems and board‑level decision materials.
To access the full report and interactive datasets, or to schedule a briefing with our lead industry analysts, visit the PW Consulting research portal or contact our biomass markets desk. The 2026 window for durable sourcing advantages is short; firms that align procurement design, certification, and logistical investments this year will capture the majority of upside as the PKS market expands.
For detailed analysis of this topic, please visit the official page: Palm Kernel Shells Biomass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com