

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: IoT UTM Market to Reach USD 25,501.94 Million by 2032 at 22.15% CAGR — Hardware Appliances ($3,268.3M) and North America ($2,451.23M) Lead

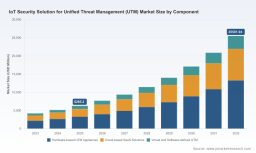
IoT Security Solution for Unified Threat Management (UTM) Market — Strategic Preview for 2026 Decision‑Making
PW Consulting is pleased to present a strategic preview of our new market research report, "IoT Security Solution For Unified Threat Management (UTM) Market." This briefing synthesizes the report’s most consequential insights for enterprise leaders planning security architecture, procurement, and compliance strategies in 2026. It is designed as a high‑signal, low‑noise executive compass: we demonstrate the analytic depth and practical frameworks contained in the full study while intentionally withholding granular subsegment tables and vendor scorecards to direct readers to the original report for complete intelligence.
Iot Security Solution For Unified Threat Management Utm Market
Market Trajectory: A Macro Lens for Strategic Planning
The market for IoT‑centric UTM solutions is accelerating rapidly. Using 2025 as the base year, PW Consulting’s topline model projects the global market to move from an estimated USD 6,285.2 Million in 2025 to USD 25,501.9 Million by 2032 — a compound annual growth rate (CAGR) of approximately 22.15% across the 2026–2032 forecast horizon. This trajectory reflects a confluence of forces: the proliferation and criticality of connected devices, declining tolerance for insecure endpoints, and steady enterprise migration toward unified, policy‑driven security stacks that span hardware, virtualized appliances, and cloud‑native controls.
Iot Security Solution For Unified Threat Management Utm Market
For practical decision‑making in 2026, enterprises should interpret these macro figures as directional: rapid market expansion implies both heightened vendor innovation and the emergence of new integration risk. Procurement timelines, vendor evaluation cycles, and internal capability ramps must accelerate accordingly to avoid technology debt.
Iot Security Solution For Unified Threat Management Utm Market
Why 2026 Is a Strategic Inflection Point
-
Regulatory pressure is materializing into enforceable obligations. Key pieces of legislation — notably the EU Cyber Resilience Act and the EU Data Act — have moved from proposal to enforcement phases, placing product liability, lifecycle update obligations, and data portability at the center of supplier risk assessments. Parallel regulatory developments in major markets (including new rules for cross‑border data and bulk data controls) are elevating compliance as a primary procurement criterion.
-
Architecture convergence is accelerating. The industry is seeing consolidation of capabilities (firewall, intrusion prevention, device profiling, and endpoint telemetry) into unified management planes; at the same time, SASE, ZTNA, and AI‑driven threat orchestration are reshaping how UTM capabilities are consumed.
-
Cost and infrastructure constraints matter. Rising data center construction and operating costs are shifting deployment economics — pushing more workloads and security controls toward SaaS and virtualized options while creating new tradeoffs around latency, sovereignty, and total cost of ownership.
What the Report Delivers — Practical, Actionable Content
PW Consulting’s full report is built for practitioners and decision makers. Key deliverables include:
-
Executive decision frameworks for selecting among hardware appliances, cloud‑native UTM services, and virtualized/software‑defined UTM — including risk maps that tie architecture choices to regulatory exposure, operational complexity, and cost drivers.
-
Procurement templates and RFP language tailored for IoT‑heavy deployments — designed to extract guarantees on device lifecycle updates, data portability, and third‑party component transparency.
-
Vendor evaluation matrices and use‑case alignment playbooks (scored against technical capabilities, compliance posture, integration ease, and managed services support). Note: detailed scorecards and numeric subsegment breakdowns are reserved for the full report.
-
Technical integration blueprints for hybrid deployments — including device discovery, segmentation patterns for mixed‑trust environments, orchestration of threat intelligence feeds, and staged migration roadmaps to minimize business disruption.
-
Financial tools: TCO and ROI models that compare capex‑heavy appliances versus consumption‑based SaaS/managed options, with sensitivity analyses for data egress costs and compliance remediation expenses.
-
Operational playbooks for security operations centers (SOCs) and managed service providers (MSPs) on runbooks, escalation paths, and SLAs aligned to IoT‑specific incident scenarios.
Competitive Landscape: Strategic Profiles and Implications
The UTM market for IoT security is multi‑dimensional. A set of established vendors anchors the market while new entrants and adjacent networking players expand capabilities through integrations and platform bundling. The report assesses market participants across technology, go‑to‑market, and ecosystem dimensions. High‑level observations:
-
Fortinet brings a platform‑centric strategy: its NGFW platforms with integrated UTM capabilities are positioned for enterprises that prioritize consolidated management and deterministic performance for IoT segmentation and threat containment.
-
Cisco leverages broad portfolio integration and channel depth. Secure Firewall and Meraki MX offerings are attractive to organizations seeking end‑to‑end visibility combined with existing networking investments and extensive partner ecosystems.
-
Check Point and Palo Alto Networks emphasize prevention efficacy and policy control, with strong investments in device‑aware security policies and Zero Trust enforcement aimed at critical infrastructure and high‑risk verticals.
-
Sophos, WatchGuard, SonicWall, and Barracuda target SMB and midmarket segments with streamlined management and co‑managed models, increasingly incorporating ZTNA and AI‑assisted analytics for IoT use cases.
-
Juniper and Huawei position through performance optimization and integrated networking/security stacks — important for telco and carrier‑grade deployments and service providers scaling IoT connectivity services.
Recent vendor activity underscores the pace of innovation and the competition for platform leadership. Examples include new product launches integrating Zero Trust Network Access and co‑managed services, AI‑enhanced SASE platforms, and frequent firmware and software updates that expand UTM feature sets. These moves signal that vendor selection in 2026 must include cadence‑of‑innovation and roadmap alignment as explicit evaluation criteria.
Market Structure and Competitive Dynamics
The market shows moderate concentration: the top three players account for a meaningful but not overwhelming share, while the top five represent a majority position. This structure fosters both competitive pricing pressure and differentiated specialization — incumbents compete on integration and global reach while challengers win contracts through niche capabilities, price agility, or superior managed services.
For enterprise buyers, this implies an opportunity to negotiate through multi‑vendor architectures: combine best‑of‑breed capabilities (for example, advanced device telemetry from one vendor with scalable cloud enforcement from another) while maintaining a single pane for policy orchestration.
Practical Recommendations for 2026 Procurement and Architecture
-
Adopt a hybrid consumption model: balance on‑premises appliances for latency‑sensitive control with cloud‑native UTM for analytics, updates, and scale to minimize vendor lock‑in.
-
Make regulatory compliance a gating criterion: require suppliers to document EU CRA and Data Act adherence, software update cadence, and data portability mechanisms before shortlist selection.
-
Prioritize device‑aware visibility and automated segmentation: a continuous inventory of IoT endpoints plus policy automation materially reduces lateral risk.
-
Extract SLAs for lifecycle support and cyber warranty where available, especially for mission‑critical IoT deployments in healthcare, industrial manufacturing, and critical infrastructure.
-
Stress‑test vendor roadmaps against scenario‑based threat simulations and supply‑chain failure modes; retain exit options and interoperability through open APIs and documented integration patterns.
-
Consider managed or co‑managed service models to accelerate maturity while building internal SOC capabilities incrementally.
Next Steps & How to Access the Full Report
PW Consulting’s full report contains the complete quantitative datasets, segment‑level modeling, vendor scorecards, and downloadable artifacts (RFP templates, TCO spreadsheets, and deployment blueprints) that underpin the insights summarized above. In keeping with our preview approach, we have intentionally omitted granular region, vertical, and component line‑items from this public briefing so that enterprise teams and procurement committees will consult the full report and its raw datasets when making binding decisions.
For enterprises preparing procurement cycles, roadmap updates, or compliance programs in 2026, the report functions as a decision‑grade resource that converts market growth signals and regulatory imperatives into actionable procurement, architecture, and operational playbooks.
To request access to the complete study, vendor scorecards, and the datasets that support our modeling, please visit PW Consulting’s research portal. Our analysts are available for briefings and custom workshops to translate the findings into organization‑specific roadmaps.
— PW Consulting, Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: Iot Security Solution For Unified Threat Management Utm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com