

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Release Paper Market Set to Expand at a 5.45% CAGR During 2026–2032

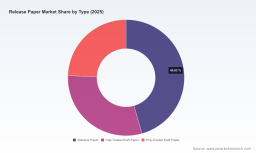
Release Paper Market 2026: Strategic Imperatives from PW Consulting’s Release Paper Market Report
Executive preview
PW Consulting’s Release Paper Market Release Paper Market Report (base year 2025) translates market complexity into executive-grade intelligence designed to inform boardroom decisions in 2026. The global release paper market — estimated at approximately USD 4,850.0 Million in 2025 — is projected to expand at a compound annual growth rate (CAGR) of 5.45% through our forecast window (2026–2032), reaching roughly USD 7,031.0 Million by 2032. This Release Paper Market Report combines forward-looking scenario analysis, supplier and technology due diligence, and practical playbooks so leadership teams can move from analysis to confident action.
Release Paper Market
Why this report matters for 2026 decisions
-
Strategic timing: 2026 is a pivot year for many downstream users (packaging, labeling, industrial tapes) as regulatory, sustainability, and input-cost pressures converge. Our report maps these inflection points to near-term investment and operational choices.
Release Paper Market -
Risk-to-return clarity: We quantify how cost inflation, supply concentration and recycling constraints impact margins and working capital under multiple scenarios — enabling procurement and FP&A teams to stress-test budgets.
Release Paper Market -
Actionable roadmaps: The report does not stop at insight. It prescribes specific pilots, supplier scorecards, and product-reengineering steps that Commercial and R&D leaders can deploy within 90–180 days.
What’s inside — practical content that drives decisions
-
Market sizing and growth trajectories (historical 2020–2025 context and a detailed forecast through 2032), with sensitivity runs around raw material price shocks and policy shifts.
-
Segment-level strategic frameworks (by substrate type, by end-use application, and by geography) that translate into portfolio prioritization matrices for product and sales leaders. Note: the executive preview intentionally omits the granular segment tables; full segmentation and downloadable datasets are available on our site.
-
Supply-chain heatmaps and supplier concentration analytics, including a three- and five-firm concentration assessment, to help procurement teams design diversification or hedging strategies.
-
Regulatory and circularity playbook: compliance checklists (EPR-ready packaging designs, recyclability disclosure templates), a decision tree for paperization vs. film strategies, and a short-list of pilot partners for closed-loop initiatives.
-
Unit-cost and pass-through models that link pulp and kraft paper price scenarios to finished-product margins and recommended commercial tactics (indexing clauses, dynamic pricing triggers, and contractual buffers).
-
M&A and partnership scorecards: targets defined by capability gaps (e.g., silicone-coating expertise, barrier coatings, recycled feedstock integration) and quick valuation heuristics tailored to 2026 market dynamics.
-
Case studies and implementation templates: blueprint for a circularity pilot, a nearshore supply-accelerator, and a label-conversion program with sample KPIs and a 12-month project plan.
Key industry dynamics shaping 2026 strategy
-
Input-cost volatility — wood pulp and kraft spreads: The US Producer Price Index for wood pulp registered near 197.184 in March 2026, and kraft paper has continued to show regional price divergence during early 2026. These dynamics create asymmetric margin pressure across supply chains and favor firms with vertical integration or robust hedging approaches.
-
Regulatory acceleration — EPR and recyclability: Extended Producer Responsibility frameworks are now a tangible operational constraint in multiple jurisdictions. EU-level EPR systems and evolving state-level guidelines (e.g., California) are forcing manufacturers and brand owners to account for minor components such as release liners in lifecycle and compliance plans.
-
Circularity complexity: Despite a strong push toward paperization of flexible packaging and labels, coated and siliconized release liners still pose recycling challenges. Industry initiatives are scaling (including projects targeting high recovery rates of coated-paper residues), but effective circularity requires coordination across coating formulators, converters and recycling processors.
-
Fragmented competitive structure: Market concentration metrics show a sector that is not heavily consolidated — the top three and top five firm shares indicate segmentation and significant opportunity for regional leaders, niche innovators, or consolidation plays. This structure supports both partnership-led scale-ups and targeted acquisitions.
-
Active industry momentum: Recent moves underscore strategic priorities. In April 2026, Mondi opened a new facility in the U.S. to support eCommerce and industrial packaging demand; prior collaborations in Europe have targeted high reuse of siliconized and coated paper waste. Suppliers and chemical partners are increasingly visible at trade platforms showcasing barrier coatings and paperization technologies.
Competitive landscape — what to watch and how to engage
The Release Paper Market Report assesses leading global and regional participants across capability, sustainability roadmap, and commercial model. Highlights include:
-
Loparex LLC (USA): A leader in specialty release liners with deep direct-coated and poly-coated capabilities; attractive as a partner for label and graphics converters seeking performance consistency.
-
Ahlstrom (Finland): Strong in fiber-based release bases and sustainability-oriented product development — well-suited for brand owners prioritizing circularity credentials.
-
Mondi Group (Austria/UK): Emphasizes recycled content and circular projects; recent facility investments signal a focus on eCommerce and industrial packaging demand.
-
UPM Raflatac / UPM (Finland): Combining release liner capabilities with labelstock innovation — relevant for customers seeking integrated recyclable label solutions.
-
Avery Dennison and 3M (USA): Offering scale, integrated labeling systems, and broad distribution networks — strategic for global rollouts and long-tail industrial uses.
-
Regional and specialty players (e.g., Gascogne, Sappi, LINTEC, Polyplex, and other regional producers): Provide niche technical strengths in coating, filmic liners, or cost-advantaged supply; excellent targets for M&A or supplier diversification strategies.
Each company profile in the full report includes capability matrices, recent strategic moves, and an engagement checklist to help buyers and investors prioritize interactions and pilots. URLs and primary-source references are provided for due-diligence follow-up.
Recommendations for executive teams in 2026
-
Prioritize supply resilience with optionality: Build a three-tier supplier map (preferred, contingency, innovation partner) and redefine contracts to include dynamic pricing triggers and capacity reservations for peak seasons.
-
Invest in circular pilots with measurable ROI: Start with high-impact applications (labelstock and tapes) where recycling pathways are tractable; track cost-to-collect and net-material substitution benefits as primary KPIs.
-
Target selective vertical integration or long-term offtake agreements: Where pulp and coating cost volatility compress margins, consider strategic stakes or multi-year agreements with key upstream suppliers to stabilize input flows.
-
Redesign products for compliance: Reassess substrate choice and coating architecture to meet EPR and recyclability requirements. Simple changes in liner grammage or silicone formulations can materially ease downstream recycling burdens.
-
Use price discipline and commercial segmentation: Implement differentiated pricing strategies by application and channel, anchoring contracts to transparent cost indices and offering value-added services (technical support, design-for-recycling consulting) at premium pricing.
-
Prepare an M&A playbook: Identify small-to-mid sized targets that provide either geographic scale in fast-growing corridors or specialised technologies (e.g., low-silicone coatings, recycled feedstock integration) for bolt-on acquisitions.
How to use the full Release Paper Market Report
-
Download the full datasets and interactive dashboards to run bespoke scenarios for your P&L and supply chain.
-
Adopt our supplier scorecard templates and pilot-planning toolkit to convert strategic intent into executable 90–180 day projects.
-
Engage PW Consulting for a tailored workshop where we apply the report’s models to your product mix, enabling prioritized investment decisions tied to quantified ROI paths.
This release serves as a strategic “trailer”: it exposes our analytical rigor and the report’s practical utility while withholding detailed segment tables and proprietary model outputs to preserve client value. For full segmentation, downloadable Excel models, supplier-level data and our scenario engine, please visit the Release Paper Market Report page on PW Consulting’s website.
About PW Consulting
PW Consulting is a strategy advisory firm specializing in materials, packaging and industrial ecosystems. Our analysts combine primary-sourced market intelligence, financial modelling and implementation-grade toolkits to help clients make decisive moves in complex, regulated markets. The Release Paper Market Report is the latest in our series of market-translation products designed for leadership teams that must act fast and with conviction in 2026.
For detailed analysis of this topic, please visit the official page: Release Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com