

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Advanced Insulation Materials Market to Expand at 9.24% CAGR, Rising from USD 15.25 Billion in 2025 to USD 28.32 Billion by 2032

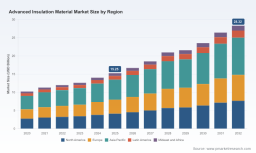
Advanced Insulation Material Market — PW Consulting Releases Strategic 2026 Playbook
Executive snapshot
PW Consulting today publishes its Advanced Insulation Material Market Research — a focused, decision‑grade study designed to orient corporate strategy for 2026 and the 2026–2032 planning window. Drawing on a five‑year historical series and a seven‑year forecast, the report traces a sustained upswing in the sector: the global advanced insulation market rose from approximately USD 10.2 billion in 2020 to USD 15.25 billion in 2025 (base year), and is projected to expand at a compound annual growth rate of 9.24% over the 2026–2032 forecast period, reaching roughly USD 28.3 billion by 2032. These headline figures mask important structural shifts — the subjects of this report — that will determine winners and losers in the coming 18–36 months.
Advanced Insulation Material Market Research
Why this report matters for 2026 decision cycles
-
Actionable timing: 2026 will be the first full year in which multiple regulatory, trade and supply‑chain shocks converge. The research distills near‑term triggers (policy enforcement, tariff regimes, shipping cost resets, raw material volatility) into precise inflection points for procurement, product roadmap and capital allocation decisions.
Advanced Insulation Material Market Research -
Commercial levers, not just forecasts: Beyond topline projections, the report provides practical tools — supplier scorecards, unit‑cost models under alternative raw‑material scenarios, and commercial playbooks — enabling procurement and business‑unit leaders to convert market intelligence into margin protection and market share gain.
Advanced Insulation Material Market Research -
Risk‑calibrated roadmaps: For R&D and product management teams, the study translates evolving regulatory thresholds and customer adoption curves into staged R&D priorities and go‑to‑market sequencing, so investment dollars are allocated to technologies most likely to scale under near‑term constraints.
Key dynamics shaping 2026 strategy
-
Regulatory tightening: New mandates on thermal performance and environmental profile are tightening product specifications across critical markets. For example, recent updates require lower thermal conductivity thresholds in public construction projects and restrict common high‑GWP blowing agents. Manufacturers must accelerate reformulation roadmaps and validation plans to ensure product eligibility in major tenders starting 2026.
-
Trade and transport friction: Trade interventions and transport cost recalibrations are materially reshaping sourcing economics. Notably, heightened duties on imports from specific offshore suppliers, combined with stricter marine fuel rules, have added a multi‑factor cost premium to trans‑Pacific supplies — a dynamic that favors near‑shoring and inventory redesign for time‑sensitive projects.
-
Raw material price volatility: Key feedstocks experienced marked price inflation entering 2026. Our analysis shows that polyol and related inputs have become a dominant margin pressure point for foam‑based products; companies that deploy dynamic hedging, backward integration options or chemistry substitutions will retain structural cost advantages.
-
Consolidation and fragmentation: The market presents a middle‑ground concentration profile — leading players collectively hold meaningful shares but a large long tail remains. This structure creates opportunities for targeted M&A, bolt‑on capabilities and specialist entrants to capture premium pockets (e.g., high‑temperature, cryogenic, battery‑thermal management applications).
Competitive landscape — what to watch in 2026
Our competitor analysis profiles global incumbents and specialist innovators across material classes and applications, clarifying who competes on scale, who competes on technology, and who is primed to leapfrog via focused investments.
-
BASF SE — A diversified materials producer with broad insulation portfolios, recently expanded capacity in expandable polystyrene at a major European site. Strategic implication: BASF’s scale and feedstock integration give it flexibility to defend volume contracts while selectively investing in higher‑value product variants.
-
Dow Inc. — A leading supplier of PIR foams and construction sealants, showcasing next‑generation PIR systems at industry events. Strategic implication: Dow’s product pipeline targets both performance upgrades and installation efficiency — an attractive combination for large contractors focused on total installed cost.
-
Saint‑Gobain — Strong in both commodity and advanced fibers, with sustainability certifications that enhance project eligibility in green procurement programs. Strategic implication: Certifications and system solutions make Saint‑Gobain a preferred partner for large public and corporate sustainability builds.
-
Rockwool & Knauf Insulation & Owens Corning — Traditional insulation majors that continue to evolve their portfolios with acoustics, fire performance and thermal improvements. Strategic implication: These firms are defensive plays for mainstream construction markets but are also moving selectively into higher‑margin niches.
-
Aspen Aerogels & Cabot Corporation — Technology specialists focused on aerogels and translucent insulation composites; recent product launches explicitly target EV battery thermal management and translucent panel applications. Strategic implication: Specialist technology providers are the primary sources of differentiation for OEMs in energy, aerospace and EV arenas.
-
Armacell & Kingspan — Focused portfolios spanning elastomeric and phenolic foams optimized for HVAC, refrigeration and building envelopes. Strategic implication: Their value proposition centers on installation speed and system compatibility, which will matter more as contractors seek to mitigate labor and compliance risks.
Recent signals that should reframe boardroom debate in 2026
-
Product innovation is accelerating at the intersection of thermal management and electrification — exemplified by aerogel entries tailored for battery systems. Boards should ask whether their R&D and partner ecosystems are aligned to capture these adjacent growth vectors.
-
Capacity moves among large chemical producers change the shape of supply risk for foams. Firms with narrow supplier bases or high exposure to specific feedstock price swings need contingency sourcing and price‑pass‑through mechanisms built into contracting.
-
Regulatory enforcement milestones in 2026 will create winners among suppliers who preemptively validated low‑GWP and high‑performance grades; laggards will face rework costs and tender ineligibility.
What the PW Consulting report contains (practical deliverables)
-
Forecasts at global and segment levels with scenario sensitivity to raw material and trade shocks — designed for CFOs and strategy teams to model top‑line and margin outcomes under alternative assumptions.
-
Supplier and technology scorecards: independent assessments covering commercial scale, technical readiness, regulatory compliance, and supply‑chain resilience.
-
Cost‑to‑serve and landed cost tools that incorporate recent shipping surcharges, tariff permutations and raw‑material trajectories — enabling procurement to quantify near‑term impacts and reoptimize sourcing.
-
Product roadmap templates and validation checklists keyed to emerging regulations and electrification use‑cases, so R&D investments map directly to addressable commercial opportunities.
-
M&A playbook and commercial due diligence checklist for buyers seeking bolt‑on capabilities in aerogels, vacuum panels, PCM systems and cryogenic insulation segments.
-
Market entry and commercialization blueprints for regional prioritization, channel strategies, and performance‑based contracting models.
Immediate recommendations for 2026 planning
-
Reprice and renegotiate: Build clause flexibility into contracts to handle sudden polyol and blowing‑agent cost moves, and quantify threshold triggers for pass‑throughs versus capex conversion.
-
Accelerate low‑GWP transitions: Fast‑track validated formulations that meet the new environmental restrictions to avoid tender exclusions and to capture sustainability premia.
-
Dualize sourcing and near‑shore high‑value SKUs: Reduce exposure to trade duties and trans‑Pacific surcharges by qualifying regional suppliers for time‑sensitive and premium applications.
-
Prioritize partnerships with technology specialists: OEMs in EV, aerospace and cryogenics should formalize co‑development agreements with aerogel and PCM innovators to secure early adopter advantages.
-
Embed scenario finance into capex decisions: Use the report’s scenario outputs to size capex under multiple price and policy trajectories rather than a single baseline.
How to use the report — a simple framework
-
Scan: Board and executive summary to surface the 3–5 strategic actions that require immediate attention in 2026.
-
Stress: Run procurement and margin stress tests using the report’s cost models under your supply profile.
-
Scale: Use the supplier scorecards and M&A playbook to prioritize partnerships, investments and bolt‑on acquisitions aligned to your chosen growth path.
PW Consulting’s Advanced Insulation Material Market Research is a purpose‑built instrument for 2026 planning cycles. The report provides the quantitative backbone and the pragmatic playbooks executives need to move from insight to action — while preserving the confidential, granular datasets essential for transaction work and competitive positioning. For access to the full data tables, supplier rankings and the downloadable modeling toolkit, visit the PW Consulting research portal and request the executive package.
For detailed analysis of this topic, please visit the official page: Advanced Insulation Material Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com