

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
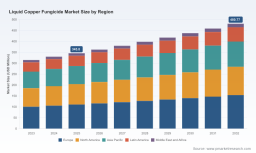
PW Consulting: Liquid Copper Fungicide Market to climb from USD 345.8 Million in 2025 to USD 480.77 Million by 2032 at a 4.82% CAGR — Europe, Copper Octanoate and Fruits & Vegetables take the lead; CR5 51.82%

Liquid Copper Fungicide Market — 2026 Strategic Outlook: Navigating Regulation, Input Volatility, and Consolidation
Executive summary
PW Consulting’s latest market study on the Liquid Copper Fungicide Market (base year: 2025; historical window: 2020–2025; forecast period: 2026–2032) equips senior management and corporate strategy teams with an operationally focused view of where the market is headed and what to do about it in 2026. Our model projects a compound annual growth rate (CAGR) of 4.82% across the 2026–2032 forecast horizon, with the market expanding steadily from a 2025 revenue base and approaching roughly USD 481 Million by 2032 under the central scenario. This release synthesizes the strategic implications of input-cost shocks, tightening regulatory regimes, and competitive moves — while reserving the full segmentation and granular data for subscribers and report licensees.
Liquid Copper Fungicide Market
Why 2026 is a strategic inflection point
Two structural trends converge to make 2026 a critical decision year for players across the value chain. First, regulatory pressure in key markets is intensifying: authorities are re-evaluating the acceptable uses and application limits for copper-based products to mitigate soil accumulation and aquatic toxicity. Second, input-cost dynamics and trade policy uncertainty are materially increasing production risk and narrowing margins for liquid formulators. Together these forces are reshaping sourcing strategies, R&D priorities, and commercial go-to-market playbooks.
Liquid Copper Fungicide Market
-
Regulatory tightening is already operational: recent authorisation frameworks in major European jurisdictions have redefined acceptable uses and imposed stricter worker-protection and environmental safeguards. Separately, EU-level rules continue to limit cumulative copper deployment over multi-year periods, reinforcing the need for product stewardship and alternative-control strategies on farms.
Liquid Copper Fungicide Market -
Input price pressure and trade policy noise are acute: benchmark data show raw copper feedstock prices spiking in 2025, and proposals for elevated import tariffs in large markets could materially raise landed costs for formulators that rely on cross-border supplies.
Market trajectory: disciplined growth, with material downside exposures
Our base-case forecast — a 4.82% CAGR over 2026–2032 — anticipates steady market expansion driven by continued demand for disease control in high-value horticultural crops, targeted adoption in cereals, and persistent usage in regions where copper remains a regulatory-accepted tool. However, downside scenarios tied to accelerated substitution policies or sharp commodity-price inflation point to materially lower upside for incumbent liquid copper suppliers. We model multiple scenarios in the full report, including a regulatory-accelerated path and an input-cost shock path, each with tactical implications for inventory, pricing, and contract strategies.
Competitive landscape: concentrated but active
The market exhibits moderate concentration with the top three firms holding roughly one-third of market revenues and the top five capturing just over half. This structure supports both scale-driven advantages (regulatory navigation, supply agreements, formulation R&D) and tactical openings for focused innovators and regional specialists.
-
UPL Limited (India) leverages broad formulation capability and distribution reach to offer copper products tailored for liquid application, positioning itself to serve diverse cropping systems where copper remains essential.
-
Nufarm (Australia) maintains a portfolio of liquid and flowable copper options; its strength lies in channel relationships and formulation know-how, particularly in markets where growers prioritize tank-mix compatibility.
-
Albaugh LLC and Certis USA (United States) are notable for their targeted liquid offerings and agility in commercializing formulations that meet local user preferences across both conventional and organic segments.
-
Multinationals such as FMC Corporation, Bayer AG, and Corteva Agriscience combine global R&D pipelines with the capacity to pivot formulations (e.g., hydroxychloride variants) and integrate stewardship messaging that aligns with tightening regulatory expectations.
-
Regional specialists and consumer-oriented brands — from Nordox and Sipcam-Oxon to consumer garden product suppliers — create a layered competitive map where scale, regulatory footprint, and channel breadth each determine tactical positioning.
Recent strategic moves illustrate how incumbents are reacting: European distribution consolidations and product launches that emphasize lower-solubility or hydroxy-based copper chemistries are tangible responses to both regulation and grower demand for improved efficacy with lower ecological load. These maneuvers underscore the necessity of monitoring partner networks and distribution ownership as part of any 2026 market-entry or expansion decision.
Regulatory and input risks: what to watch in 2026
Four regulatory and input themes will influence commercial outcomes and should be modeled explicitly in 2026 planning cycles:
-
Regulatory tightening and classification: National agencies are already revisiting approvals and conditions for copper compounds. In some jurisdictions, copper is now treated as a candidate-for-substitution substance, heightening the probability of phased reductions and stricter application limits.
-
Aggregate use limits: EU frameworks that cap cumulative copper application over multi-year windows remain active policy drivers; compliance mechanisms (e.g., record-keeping, stewardship programs) will form part of commercial offerings and can act as market access barriers for smaller suppliers.
-
Trade policy and tariffs: Proposed or enacted tariffs on refined copper imports can materially raise raw-material costs for formulators that lack integrated metal sourcing or long-term offtake agreements. Hedging and upstream partnerships are consequently high-priority strategic levers.
-
Price volatility in copper feeds: Spot and contract prices for copper sulphate and related intermediates spiked in 2025, increasing working-capital requirements and pressuring margins. Procurement strategies should explicitly incorporate scenario-based costing and supplier diversification.
Strategic imperatives for 2026 decision-makers
For boards, corporate development teams, and commercial leadership, our research identifies five practical imperatives to prioritize in 2026:
-
Rebuild sourcing resilience: secure diversified feedstock supply lines and negotiate flexible contracts with built-in pass-throughs for raw-material spikes. Evaluate near-shore and secondary sourcing to insulate manufacturing from tariff shocks.
-
Invest in lower-copper or alternative chemistries and formulation technologies that reduce applied copper per hectare without sacrificing efficacy. Even incremental reductions in copper load per application yield outsized regulatory and reputational benefits.
-
Develop compliance-led commercial propositions: couple product offers with stewardship services (application training, record-keeping tools) to ease customer transition under cumulative-use restrictions.
-
Prioritize channel and distribution assessments in M&A and partnership screening: recent acquisitions and distribution reallocations in Europe show that footprint control materially affects shelf share and grower access.
-
Institute scenario-based P&L stress testing that incorporates regulatory down-side and input-cost up-side. Short-term inventory is no substitute for a strategic hedging and forward-procurement playbook aligned with likely 2026 regulatory trajectories.
Report deliverables: what’s inside (select, operationally focused modules)
The full PW Consulting report is intentionally practical. Key modules include:
-
End-to-end market model (2020–2032) with baseline and scenario variants, expressed in USD Million;
-
Granular segmentation by formulation type, application, and region with demand drivers and sensitivity matrices;
-
Competitive scorecard and capability map for leading suppliers, including product portfolios, channel reach, and strategic initiatives;
-
Regulatory tracker with jurisdictional heat maps and compliance roadmaps for product registration and use limitations;
-
Procurement playbook and supplier-risk heatmap, including contract templates and hedging options for raw copper intermediates;
-
M&A screening tools and target shortlists based on value-creation levers (scale, formulation IP, regional distribution);
-
Implementation checklists and commercial pilots to reduce copper load while maintaining disease control performance.
To honour the report’s “trailer” posture and direct readers to the licensed product, we do not publish the full segmentation tables or the region-and-application revenue splits in this press release. Subscribers to PW Consulting’s report receive the complete datasets, model files, and confidential annexes needed to operationalize the insights above.
How leading firms are adapting — illustrative moves
Market participants are already taking concrete actions that reflect the strategic imperatives described above. Examples observed through 2024–2025 include targeted product launches that emphasize hydroxychloride or low-solubility copper forms; acquisition of regional distribution assets to secure market access; and active engagement with regulators to shape conditions of use and worker-protection requirements. These behaviors are consistent with a competitive environment where scale, formulation differentiation, and regulatory agility determine commercial resilience.
Next steps for executives
For executives making allocation decisions in 2026 — whether capital deployment for R&D, M&A screening, or supply-chain restructuring — PW Consulting recommends three immediate actions:
-
Run a 12-month tactical plan and a 36-month strategic review in parallel, using scenario outputs that reflect both regulatory acceleration and raw-material shocks;
-
Commission a supplier resilience audit focused on tariff exposure and feedstock concentration;
-
Initiate targeted R&D pilots (co-funded with key customers where possible) to validate lower-copper formulations under commercial conditions.
Conclusion and how to obtain the full analysis
The Liquid Copper Fungicide Market sits at the intersection of agronomic necessity and regulatory scrutiny. Our 2026 strategic briefing highlights a moderate-growth market with clear winners and losers driven by regulatory responsiveness, feedstock strategy, and the ability to deliver efficacy with lower environmental load. For teams needing the full dataset, segment-level forecasts, and executable playbooks, the complete report (with model files and confidential annexes) is available from PW Consulting. Accessing the licensed study will provide the granular inputs and proprietary scenarios required to convert the high-level imperatives outlined here into operational programs and board-ready recommendations.
For detailed analysis of this topic, please visit the official page: Liquid Copper Fungicide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com