

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
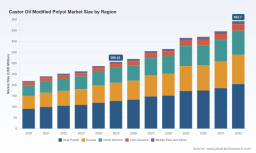
PW Consulting: Castor Oil Modified Polyol Market to Rise from USD 306.43 Million in 2025 to USD 492.7 Million by 2032 at a 7.02% CAGR — Asia‑Pacific Leads with USD 127.23M

Castor Oil Modified Polyol Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting presents an executive preview of our Castor Oil Modified Polyol Market study — a practitioner-oriented intelligence product designed to convert market signals into 2026-ready strategic decisions. The report synthesizes historical performance (2020–2025), a forward-looking forecast window (2026–2032), and operational playbooks for procurement, product development, and commercial structuring. At the macro level, the market expanded from roughly USD 218 million in 2020 to approximately USD 306 million in 2025, and our forecast indicates growth to nearly USD 493 million by 2032 — implying a compound annual growth rate of 7.02% over the 2026–2032 period. Those topline dynamics create a strategic inflection point for suppliers, converters and end users alike.
Castor Oil Modified Polyol Market
Why 2026 Is a Pivotal Planning Year
-
Translating demand into capacity decisions. The sub-10% annual growth profile over the forecast window signals attractive expansion opportunities while preserving room for disciplined capacity buildouts. 2026 is the moment to validate greenfield vs brownfield capex with scenario-tested demand curves.
Castor Oil Modified Polyol Market -
Sustainability is business-critical. Regulatory drivers in major markets are accelerating procurement specifications that favor bio-based chemistries. Buyers and OEMs who want to lock in bio-preferred claims and low-VOC compliance must move from pilot formulations to qualifying supply chains in 2026.
Castor Oil Modified Polyol Market -
Supply chain rebalancing. Castor feedstock and oleochemical cost volatility, plus policy shifts in export tax and rebate regimes in 2026, materially affect landed cost and competitive positioning for polyol producers. Our analysis frames sourcing choices as a strategic lever rather than a tactical burden.
What the Report Delivers — Operational and Strategic Layers
This study is structured to serve both strategy teams and practitioners. It blends market modelling with executable workstreams and includes:
-
Top-down market sizing and demand-driver diagnostics from 2020 through 2032, with a conservative-to-aggressive scenario engine for board-level planning.
-
Segmentation mapping by technology route (polyester vs. polyether castor polyols), by application families (coatings, adhesives, sealants & elastomers; rigid and flexible foam; industrial specialties), and by commercial channel — presented as decision trees rather than raw tables to preserve client advantage.
-
Detailed value-chain view and cost pass-through modelling that isolates feedstock exposure, conversion cost bands, and margin sensitivity to oil-price and policy shocks.
-
Supplier qualification frameworks and scorecards (technical, commercial, ESG), a shortlist of strategic partners, and a procurement playbook for long-term offtakes, toll agreements, and JV options.
-
Formulation & application playbooks: real-world recipes, performance tradeoffs, and compatibility matrices for converting castor-modified polyols into high-value CASE formulations and foam systems.
-
Regulatory impact assessment and compliance pathways tailored to EU REACH, US TSCA/EPA expectations, and upcoming incentives under circularity/Green Deal programs.
-
M&A and licensing opportunity maps, as well as a step-by-step integration checklist to preserve technical know-how and maintain customer continuity post-transaction.
-
Interactive financial model (Excel) with sensitivity levers for pricing, conversion yields, and capex timelines so teams can run enterprise-specific payback scenarios.
Competitive Landscape — What We Observed and What It Means
The market is served by a mix of specialized players, regional castor-centric manufacturers, and global chemical houses. Our qualitative and commercial analysis of leading organizations yields actionable contrasts for partnering, procurement and competitive defense.
-
Alberdingk Boley GmbH (Krefeld, Germany) — Strengths: a technologically mature portfolio of 100% solids, branched polyether-polyester polyols that emphasize low viscosity, hydrophobicity and high biobased content; updated technical documentation (July 2025) underscores their push to make formulation adoption easier for industrial coatings and potting applications. Strategic implication: premium positioning on formulation support and sustainability documentation makes them an attractive partner for high-spec customers seeking fast time-to-market.
-
Stepan Company (USA) — Strengths: product breadth with STEPANPOL® grades targeting controlled reactivity and medium-low viscosities. Strategic implication: suited to converters that require reliable processing windows and predictable downstream performance in polyurethane systems.
-
BASF SE (Germany) — Strengths: leveraging large-scale R&D, global production and established application pipelines for natural-oil polyols. Strategic implication: incumbency advantages in flexible foam and industrial coatings markets mean competitors must differentiate on service, niche technical expertise or cost to win accounts.
-
Eagle Specialty Products (USA) — Strengths: focused castor polyol lines including high-solids, TDI-reacted and waterborne variants plus ancillary services like moisture scavengers. Strategic implication: tactical fit for formulators prioritizing low-acid, low-moisture chemistries and customer-specific processing aids.
-
Jayant Agro / Vithal Castor Polyols (India; Indo-Japanese JV) — Strengths: integration into oleochemical feedstock sourcing and the recent expansion of castor-derivative capacity (site announcements in late 2025) improve supply certainty. Strategic implication: attractive for large converters seeking trade-offs between cost and traceability, or for downstream licensing partnerships.
-
Indian castor specialists (Gokul Overseas, Modi Oil Mill, Vithal / Modi group associates) — Strengths: direct access to feedstock and customized formulation services for foam and coatings markets. Strategic implication: agile partners for regional supply and private-label agreements, but buyers should layer in quality audits and hedging strategies to manage agricultural supply variability.
-
Emirachem — Strengths: regional supplier emphasizing biodegradability and thermal stability; useful where proximity and fast supply are prioritized.
Collectively, the top-tier suppliers do not dominate the market outright; global demand is broad enough to sustain mid-sized specialists while still rewarding scale and technical leadership. For 2026 decisions this means multiple partnering models are viable depending on customer segmentation and value capture objectives.
Raw Material and Regulatory Context — The External Constraints Shaping Strategy
-
Feedstock dynamics: Castor remains a niche vegetable oil with concentrated production geography and an agricultural supply cycle. The broader oleochemical complex is subject to seed yields, planting incentives and competing industrial demand which together create price and availability noise. Executives must treat feedstock as a strategic risk: diversify sourcing, consider tolling agreements, and evaluate vertical integration where margin and security rationales align.
-
Policy and regulation: Regional environmental frameworks are increasingly favorable to bio-based polyols through VOC regulation, renewable content credits and procurement incentives. However, localized policy changes — notably a recent move in a major market to modify export rebate regimes for polyether polyols effective April 1, 2026 — can alter cost competitiveness quickly. Our modelling quantifies the impact of such policy shifts under multiple trade and currency assumptions.
How Executives Should Use This Report in 2026
-
Procurement & sourcing: Use the supplier scorecards and our cost-pass-through model to negotiate medium-term supply contracts that include floor/ceiling clauses and feedstock-linked price mechanisms. Prioritize conditional capacity options (expandable offtake, tolling) over fixed asset exposure when entering new geographies.
-
R&D and product strategy: Align formulation roadmaps to capture both high-margin CASE applications and differentiated foam niches. Accelerate qualification of bio-content claims by securing lifecycle and biobased-certification support from suppliers with verifiable third-party data.
-
Commercial and GTM: For producers, segment go-to-market by customer sophistication: provide turnkey formulation kits and technical service bundles to high-value customers while offering commodity-grade supply to price-sensitive converters. For buyers, cluster purchasing by application to extract scale economies without compromising on technical fit.
-
M&A and partnerships: Use the M&A opportunity map to find bolt-on technologies (catalysts, processing aids, isocyanate compatibilizers) that improve conversion yields and shorten development cycles. For acquirers, the priority is integration risk mitigation — maintain key technical staff and customer-facing formulation experts through earn-outs or retention schemes.
-
Risk & compliance: Implement a regulatory watch for new VOC and bio-preferred standards and run stress-tests against scenarios where export incentives shift or feedstock availability tightens.
Closing — A Strategic “Trailer”
This briefing is a condensed, decision-focused preview of the full PW Consulting Castor Oil Modified Polyol Market report. We have intentionally showcased the depth and practical orientation of the study while preserving the granular regional splits, application-by-application revenue breakdowns, price curve tables, and the interactive Excel modelling that underpin board-level recommendations. Those datasets are included in the full report and are essential for company-specific planning and contract negotiations.
To access the complete intelligence package — including regional and application-level tables, supplier scorecards with quantitative ratings, unit-cost build-ups, and the sensitivity-ready financial model — visit the PW Consulting report page or contact your PW Consulting account lead. Our team can also arrange a tailored briefing that applies the model to your specific P&L and operational parameters.
For detailed analysis of this topic, please visit the official page: Castor Oil Modified Polyol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com