

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Glass Fiber Composites Market Reaches USD 66,450 Million in 2025; Poised for 5.24% CAGR (2026–2032) as Asia Pacific Tops USD 32,323.09 Million

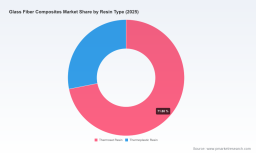
Glass Fiber Composites Market — Strategic Outlook for 2026
PW Consulting’s latest market intelligence on the global Glass Fiber Composites market delivers a forward-looking playbook for executives making 2026 strategic and capital-allocation decisions. Our analysis shows the market reached approximately USD 66.5 billion in 2025 and is positioned to exceed USD 95.0 billion by 2032, underpinned by a 5.24% compound annual growth rate across the 2026–2032 forecast window. These headline metrics capture the scale and steady expansion of an industry that is simultaneously maturing in core uses and innovating into high-growth adjacencies.
Glass Fiber Composites Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is a transitional year in which near-term supply-side shifts and mid-term technology adoption curves intersect. Companies that align procurement, manufacturing footprint, and product roadmaps now can capture share as demand from wind, transportation electrification, and industrial lightweighting ramps.
Glass Fiber Composites Market -
Risk-adjusted investment: The market’s steady CAGR masks pockets of uneven dynamics — regional trade measures, raw-material cost volatility, and capacity additions that will reshape local pricing and lead times. Our report provides scenario-based financial templates built to stress-test investments under those conditions.
Glass Fiber Composites Market -
Commercial leverage: Manufacturers and downstream players face a more concentrated supplier landscape than a fully commoditized market, yielding opportunities for differentiated commercial strategies (preferred-supplier programs, product bundling, and downstream partnerships).
What you get in the report — operationally focused modules
-
Market sizing and outlook: A robust historical series (2020–2025) and a granular forecast (2026–2032) with demand drivers, elasticity assumptions, and a clear decomposition of growth by end use and resin technology. The public summary intentionally preserves segment-level detail to encourage direct engagement with the full dataset.
-
Supply-chain intelligence: Mapping of global capacity, recent and planned expansions, feedstock sourcing pathways, and logistics chokepoints. This includes supplier profiles, utilization trends, and a cost-curve framework for regional production economics.
-
Pricing and margin playbooks: Dynamic pricing models calibrated to raw-material pressure, regional transport costs, and anti-dumping/regulatory impacts. Templates show how contract structures, indexation, and hedging approaches affect margin capture at various points in the value chain.
-
Technology and product roadmaps: Comparative analysis of thermoset vs. thermoplastic composites adoption, opportunities in specialty glass fibers (high-strength and electronic-grade), and manufacturing enablers such as pultrusion and automated layup.
-
Commercial and procurement toolkits: Supplier segmentation matrices, negotiation playbooks, and go-to-market blueprints for OEMs and tier suppliers looking to monetize performance benefits or secure preferred supply.
-
Risk & regulatory matrix: Assessment of tariffs, anti-dumping actions, and environmental-product declarations that could affect product acceptability in key markets — paired with mitigation strategies for sourcing and pricing.
-
Decision support appendices: Investment scorecards, sensitivity analyses, and three scenario paths (baseline, constrained-supply, and accelerated-adoption) to support board-level CAPEX decisions and M&A screening in 2026.
Key industry dynamics to watch in 2026
-
Capacity additions and the geography of scale: Several major producers have announced new lines or plant expansions targeting both commodity E-glass and higher-value specialty grades. These capacity moves will reallocate regional supply balances and create localized pricing differentials that procurement teams must anticipate.
-
Input-cost pressure and pass-through mechanics: Late-2025 trends indicated upward pressure on glass-fiber feedstock costs in multiple regions. Producers with the ability to index supply contracts and deploy automated production to reduce labor intensity will widen nominal margins relative to peers.
-
Trade and regulatory overlay: Ongoing anti-dumping measures and tariff regimes continue to influence sourcing choices and near-shore manufacturing economics. Firms should model the impact of these policy levers on landed cost and time-to-market rather than relying on headline price movements alone.
-
Technology migration: Thermoplastic composites and specialty fibers are attracting incremental R&D and capex, especially where recyclability and cycle-time reduction are critical. Companies that invest in application-specific formulations and automated processing stand to capture premium applications.
Competitive landscape — who matters and why
The market concentration indicates a moderately consolidated supplier base, with the three largest players accounting for a meaningful portion of global capacity and the top five expanding that share further. Key industry participants profiled in the report include:
-
Owens Corning (Toledo, Ohio, USA) — Global leader in glass-fiber reinforcements with deep exposure to construction, wind energy, and automotive end markets; strong portfolio across rovings, chopped strands, and fabrics.
-
Jushi Group (Tongxiang, Zhejiang, China) — One of the world’s largest-volume producers, actively scaling capacity and moving into intelligent, lower-carbon production footprints to serve wind and transport sectors.
-
PPG Industries (Pittsburgh, Pennsylvania, USA) — Supplies reinforcements for marine, aerospace, and industrial composites; notable capability in coating and multi-material integration.
-
Johns Manville (Denver, Colorado, USA) — Focused on nonwovens and filtration-grade microfibers, with recent plant investments in Europe targeting higher-performance applications.
-
Nippon Electric Glass (Otsu, Shiga, Japan) — Specialty E-glass and electronic-grade fiber specialist with strengths in automotive electronics and high-performance composites.
-
Chongqing Polycomp (Chongqing, China), Taishan Fiberglass (Taian, China), 3B-the fibreglass Company (Battice, Belgium), Saint-Gobain Vetrotex (Courbevoie, France), AGY Holding (Aiken, South Carolina, USA), Exel Composites (Mäntyharju, Finland), and Strongwell (Bristol, Virginia, USA) — each occupies strategic niches from high-volume rovings to pultruded structural composite solutions and specialty high-strength fibers.
Recent signals that should be shaping 2026 plans
-
Targeted capacity builds focused on electronic-grade and specialty glass fibers reflect demand growth from electronics and semiconductor packaging applications. Executives should evaluate whether to partner with established producers or capture margin through in-house specialty capacity.
-
European and North American investments in microfiberglass and filtration-grade products underscore a segmentation of value where quality and regulatory compliance command a premium. This is an opportunity for product-differentiated players.
-
Trade policy remains a swing factor. Firms that develop alternative sourcing lanes and flexible manufacturing footprints will convert policy volatility into competitive advantage.
Actionable strategic imperatives for 2026
-
Re-scope procurement KPIs: Move beyond unit price to a landed-cost metric that incorporates tariff exposure, lead-time reliability, and carbon intensity. Use staged contracts with volume-flex clauses tied to clear indexation.
-
Prioritize capacity optionality: When investing in new lines, prefer modular solutions that can be re-tooled between commodity and specialty grades to manage demand cyclicality.
-
Pursue targeted vertical plays: Selective downstream partnerships or bolt-on acquisitions in high-margin applications (e.g., pultruded structural profiles, electronic-grade glass fibers) can materially improve return on invested capital versus competing on commodity volumes.
-
Embed regulatory scenario planning into product development: Early engagement with environmental product declarations and compliance pathways will shorten time-to-revenue for construction and infrastructure tenders.
-
Invest in digital manufacturing: Automation and real-time quality data materially reduce scrap and accelerate ramp-up, particularly in applications where precise fiber orientation and resin control are mission-critical.
How PW Consulting can support your 2026 agenda
Our Glass Fiber Composites Market report is designed as an executable decision-support package rather than a static market summary. For CFOs, heads of supply chain, and business-unit leaders, the report offers the quantitative inputs and qualitative playbooks needed to:
-
Build robust CAPEX cases with integrated sensitivity runs.
-
Design procurement contracts that reflect regional policy and cost volatility.
-
Identify M&A targets and partnership opportunities aligned to high-margin product niches.
-
Operationalize technology migration strategies from lab to production.
To preserve the strategic value of the full dataset and proprietary segmentation work, this release omits the detailed regional and application split tables. Executive teams seeking the complete model, supplier scorecards, and the scenario-ready financial templates should access the full report and datasets on our website.
Contact PW Consulting to schedule a briefing with our senior analysts and industry leads; we will walk your leadership team through tailored implications for your business and provide the custom modeling required for binding 2026 decisions.
For detailed analysis of this topic, please visit the official page: Glass Fiber Composites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com