

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
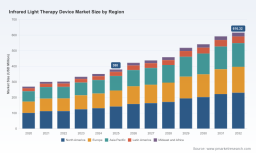
PW Consulting: Infrared Light Therapy Market to Hit USD 616.32 Million by 2032 — 7.15% CAGR Fuels North America’s USD 142.35M Lead

Infrared Light Therapy Device Market: Strategic Imperatives for 2026 — PW Consulting Executive Brief
Executive summary
The infrared light therapy device market reached a pivotal juncture in 2025, with a global market size measured at USD 380.0 Million (base year 2025) and a firmed forecast trajectory into 2026 and beyond. PW Consulting’s latest market research projects the market expanding to an estimated USD 422.56 Million in 2026 and growing at a compound annual growth rate (CAGR) of 7.15% across the 2026–2032 forecast horizon. For corporate leaders and investors planning priorities in 2026, this report translates growth signals into a concise playbook: where to invest in product, evidence, channels, and supply chain resilience to capture disproportionate returns.
Infrared Light Therapy Device Market
Why 2026 is a strategic inflection point
Two dynamics converge in 2026 to make it a decision-critical year. First, near-term demand indicators and clinical adoption momentum have moved overall market sizing materially higher compared with the early-2020s baseline — a trend reflected in our model which uses 2020–2025 as the calibration window and 2026–2032 as the forecast period. Second, regulatory and reimbursement contours have become more operationally deterministic: Class II device pathways (510(k)) in major markets and CPT-based reimbursement frameworks now define the timeline and economics of clinical adoption. Together, these forces compress go-to-market timelines for new entrants and force incumbent pricing and evidence strategies to become more sophisticated.
Infrared Light Therapy Device Market
What the PW Consulting report delivers — practical, actionable intelligence
-
Quantitative modeling: A transparent, reproducible financial model built on historical data (2020–2025) and stress-tested scenarios for 2026–2032. The model includes topline forecasts, sensitivity runs for price and adoption curves, and scenario matrices for regulatory delays or reimbursement shifts.
Infrared Light Therapy Device Market -
Regulatory roadmap: Step-by-step pathways for Class II (510(k)) approvals in the U.S. and equivalent routes in other major jurisdictions, including resource and timeline estimates calibrated against recent approvals and enforcement trends.
-
Clinical evidence strategy: Prioritized study designs (RCTs, pragmatic trials, real-world evidence) mapped to the most impactful indications for payor coverage and clinician adoption. We identify the minimum evidence thresholds that meaningfully increase reimbursement probability and clinician uptake.
-
Commercial playbooks: Channel strategies for direct-to-consumer, clinic/professional, and hospital deployment; pricing frameworks that balance ASP (average selling price) with utilization under typical CPT reimbursement caps; and partnership templates for OEM, distributor, and clinical network agreements.
-
Supply chain and BOM optimization: Analysis of critical components (notably high-power near-infrared LEDs) and sourcing strategies to mitigate cost and lead-time volatility, including alternative component sourcing, vertical integration considerations, and inventory hedging tactics.
-
M&A and partnership scouting: A prioritized list of archetypal targets across tech, clinical evidence, and distribution domains, with indicative valuations derived from our forecast scenarios and concentration metrics.
Market structure and competitive posture
The market remains moderately fragmented with a low-to-moderate level of concentration among leading vendors — a dynamic that creates opportunity for both specialist device makers and convergent platform players. Key players in the landscape illustrate a range of competitive strategies, from portable consumer devices to clinical-grade whole-body systems and wearable targeting solutions. PW Consulting’s report includes qualitative and quantitative profiles of the leading firms and their strategic postures; below is an executive snapshot of the competitive map and recent catalytic events that matter to 2026 planning.
-
Infraredi (USA) — Focuses on portable panels that balance full-body and targeted use cases across wavelengths in the therapeutic near-infrared band. Their product design choices emphasize modularity and consumer ergonomics.
-
Mito Red Light (USA) — Recently introduced an enhanced near-infrared series (MitoPRO+) with increased penetration-focused output. This move signals an R&D escalation in output and wavelength optimization as differentiation vectors.
-
Joovv (USA) — A modular full-body systems player that achieved a notable FDA Class II clearance for a portable OTC device, underscoring the strategic value of regulatory portability between consumer and clinical channels.
-
PlatinumLED Therapy Lights (USA) — Competes on high-power panel performance with product lines blended for both therapeutic and aesthetic uses, prioritizing power density and thermal design.
-
Novaa Lab (USA) — Advances wearable form factors aimed at joint and targeted-pain applications — an important segment for repeat utilization economics.
-
Celluma (USA) — Published clinical results showing substantial efficacy signals in arthritis pain reduction, reinforcing the clinical pathway for professional clinic adoption.
-
NovoTHOR (UK) — A specialist in whole-body beds; recent distribution agreements with hospital chains illustrate hospital-system interest in recovery and performance optimization offerings.
-
THOR Photomedicine (UK), Multi Radiance Medical (USA), Erchonia (USA) — Clinical and laser-combined technologies focused on wound healing, pain, and niche neurological indications; these firms emphasize evidence depth and clinical partner networks.
Recent developments that recalibrate strategy
-
Mito Red Light’s product launch of enhanced near-infrared output (Oct 2025) pushes the competitive bar on device efficacy claims and component sourcing for higher-power LEDs.
-
Joovv’s FDA clearance for a portable OTC pain device (June 2025) has broadened acceptable product architectures for over-the-counter pain indications and set precedents for labeling and clinical claims.
-
Celluma’s clinical study (Mar 2025) demonstrating a high responder rate in arthritis pain has immediate implications for payor engagement and clinician advisory strategies.
-
NovoTHOR’s hospital distribution agreements (Nov 2024) highlight institutional demand for whole-body therapeutic solutions, underscoring the need for implementation science and service models in hospital deployments.
Regulatory, reimbursement and supply-side levers
Understanding non-product levers is as important as device engineering. U.S. regulators classify non-invasive infrared devices for pain relief under a Class II pathway requiring 510(k) considerations, and common reimbursement pathways reference CPT codes that cap session volumes under standard therapy rules. From a supply perspective, high-power near-infrared LEDs are both a technical enabler and a cost driver; these components often represent a material portion of device BOM, therefore procurement strategy and supplier diversification materially influence margin and time-to-market.
Strategic recommendations for 2026
-
Prioritize clinical evidence that directly maps to reimbursement and clinician adoption. Invest in a two-track evidence plan: a high-rigor RCT for payer-facing claims and pragmatic, real-world registry work for commercial adoption momentum.
-
Lock down supply agreements for high-power LEDs and thermal management subsystems now. Consider long-lead contracts, dual-sourcing, or strategic minority investments in LED suppliers as insurance against component scarcity.
-
Differentiate via channel strategy: hybrid models that combine direct-to-consumer brand reach with clinical channel credibility (clinics, sports performance centers, hospital partnerships) will shorten payback and broaden revenue streams.
-
Design product roadmaps with regulatory modularity in mind: building a platform that can be configured for OTC, clinic, or hospital use reduces incremental certification costs and accelerates market coverage.
-
Use scenario-based valuation for M&A decisions. With market concentration metrics indicating room for consolidation, align acquisition criteria with gaps in clinical evidence, distribution reach, or component control rather than headline revenue alone.
How PW Consulting’s report supports 2026 decision-making
Our deliverable is designed as an operational manual for executives: forecast engines, go-to-market checklists, regulatory templates, clinical protocol blueprints, supplier due diligence scorecards, and M&A valuation models. The research is grounded in 2020–2025 historical data, anchored to the 2025 base year, and provides a probabilistic outlook through 2032. For teams preparing budgets, R&D roadmaps, or board-level investment cases in 2026, the report reduces execution risk by converting market growth signals — including our 7.15% CAGR forecast — into prioritized actions and quantified outcomes.
Next steps
PW Consulting’s Infrared Light Therapy Device Market report is intentionally structured to surface executive-level conclusions while protecting granular segment-level forecasts to preserve client value and encourage direct engagement. For organizations ready to operationalize a 2026 plan — whether to launch a new device, pursue clinical partnerships, secure reimbursement, or evaluate M&A — the full report provides the detailed segment data, supplier matrices, and model access required for execution.
Contact PW Consulting to request the full dataset, the reproducible financial model, and a tailored strategy workshop that converts the report’s insights into a 90–180 day operational plan.
For detailed analysis of this topic, please visit the official page: Infrared Light Therapy Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com