

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Flutes Instrument Market to Expand at a 4.31% CAGR Through 2032

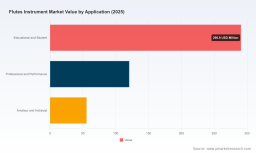
Flutes Instrument Market 2026: Strategic Insights for Decision-Makers
PW Consulting’s latest Flutes Instrument Market report synthesizes six years of observed industry behavior (2020–2025) and delivers a forward-looking forecast through 2032. The global flutes market—measured at approximately USD 467 million in 2025—is projected to follow a steady, structurally driven expansion at a compound annual growth rate (CAGR) of 4.31% over the 2026–2032 forecast period, reaching roughly USD 628 million by 2032. For executives facing procurement cycles, product portfolio choices, M&A decisions, and supply-chain redesigns in 2026, this study provides a compact but practical playbook: what matters, where risk concentrates, and which actions unlock defensible growth.
Flutes Instrument Market
Why this report matters for 2026 strategy
-
Actionable precision at the right level: Our modelling gives reliable market-size and growth trajectories for the whole category (student through professional instruments), enabling budget-setting and top-line planning without overreliance on anecdotal dealer data.
Flutes Instrument Market -
Decision-ready scenarios: Beyond a base-case projection, the study constructs alternative outcomes tied to policy shifts (tariff shocks), education-program investments, and premiumization trends—each mapped to commercial levers you can pull in 2026.
Flutes Instrument Market -
Competitive and operational focus: The report connects market dynamics to supplier strategies and manufacturing footprints, translating industry-level change into supplier selection, sourcing reallocation, and product development priorities.
Core findings you can act on now
-
Market momentum is predictable but nuanced. The category grows at a mid-single-digit rate (CAGR 4.31%), driven by a stable base of music-education demand and a resurging appetite for high-end handcrafted instruments. This combination sustains both volume-led and value-led opportunities—important for firms that sell across student, intermediate, and professional tiers.
-
Concentration and competitive balance. The segment is neither a pure commodity market nor an artisanal oligopoly: the top three players account for a meaningful portion of total value, and the top five extend that share to a clear majority. This concentration creates distinct counterparty risks for buyers and distributors, and creates both acquisition targets and defensible niches for challengers.
-
Regulatory and trade exposure is acute. New tariff layers introduced in 2025 pushed effective import costs higher and contributed to a notable decline in some trade flows. Firms with exposure to cross-border sourcing or those reliant on low-cost imports into tariff-sensitive markets should prioritize tariff-mitigation and near-shoring analyses in 2026.
-
Education policy amplifies demand levers. Government investments in music education—especially across emerging Asian markets—create multi-year OEM pull-through for student- and school-focused instruments. These programs are a primary vector for sustained volume growth and should be central to channel and go-to-market plans.
What the report contains (practical components)
-
Top-down market model: A transparent model covering 2020–2032 with base and scenario forecasts, clearly documented assumptions, and a sensitivity engine you can re-run with your own input assumptions.
-
Risk register and mitigation playbook: A prioritized list of policy, supply-chain, and demand-side shocks—with practical mitigations (tariff hedging, localized assembly, inventory rebalancing, and contractual strategy) and estimated operational impacts.
-
Commercial scorecards: Templates to assess dealers, distributors, and OEM partners across financial health, market access, channel reach, and operational resilience—built to be populated and used in vendor selection meetings.
-
Product and route-to-market playbook: Nine strategic plays—ranging from “education-first market entry” to “artisanal premiumization” and “supply-chain de-risk plus local assembly”—each with execution checklists and KPI recommendations for year 1 and year 2.
-
Granular but protected intelligence: Country- and channel-level signals, dealer interviews, technical trends (headjoint designs, material choices, and packaging sustainability), and a list of near-term catalysts. Note: detailed sub-segment tables and country-level numbers are intentionally reserved for the full report to preserve the commercial value of the data.
Competitive landscape — what incumbents and innovators are doing
The flutes market comprises a spectrum of companies—from diversified global instrument manufacturers to specialist artisan houses. Several archetypes emerge, each with strategic implications for partners and competitors:
-
Global diversified OEMs (e.g., Yamaha Corporation): These firms combine product breadth, global distribution, and brand recognition. Their recent sustainability-led packaging initiatives demonstrate how product presentation and ESG can be leveraged to win institutional procurement and retail placements simultaneously.
-
Mass-market and education-focused manufacturers (e.g., Trevor James, Jupiter, Armstrong/Conn-Selmer): These players optimize cost-to-performance and channel partnerships with schools and retailers—making them natural allies for programs driven by education policy funding.
-
High-end Japanese and European specialists (e.g., Muramatsu, Miyazawa, Sankyo, Altus): Their product innovations and factory-controlled quality command premium pricing and brand loyalty among professional musicians and conservatories. For firms targeting aspirational buyers, alignment with these makers boosts credibility.
-
U.S.-based boutique makers (e.g., Verne Q. Powell, Wm. S. Haynes, Brannen Brothers, Burkart, Di Zhao): These firms represent the artisanal tail of the market. The “Boston cluster” is increasingly recognized as a global hub for premium handmade instruments—an intangible asset that supports price resilience and aftermarket services.
Collectively, these players produce a landscape where the top five firms capture a clear majority of market value, creating both competitive entry barriers and targeted acquisition opportunities for strategic acquirers.
Operational and go-to-market risks to monitor in 2026
-
Tariff volatility and import cost pressure: The effective tariff environment introduced in 2025 has raised landed costs and disrupted price architecture for imports and accessories. Procurement teams should model several tariff-shock scenarios and evaluate near-shoring, alternative sourcing, or price-indexed supply contracts.
-
Channel concentration risk: Heavy reliance on a small number of school-buying agencies, wholesale distributors, or export corridors magnifies downside exposure—especially where regional policies shift or funding pauses.
-
Premium demand vs. supply constraints: Demand for handmade professional instruments is increasing, but artisanal capacity is finite. Firms that can coordinate waitlists, offer upgrade pathways, or provide premium service bundles will capture high-margin opportunities.
Recommendations for executives planning 2026 actions
-
For OEMs and brand owners: Prioritize a dual-track strategy—protect educational-volume channels with cost-optimized models and secure premium positioning through limited-edition artisanal lines and service-based offerings.
-
For distributors and retailers: Re-evaluate supplier mixes against tariff exposure; build localized inventory hubs for high-velocity SKUs; and develop education-program packages that simplify procurement for school systems.
-
For private equity and strategic buyers: Target bolt-on acquisitions in specialized manufacturing and boutique service businesses that can be scaled digitally (e.g., customization workflows, headjoint upgrades, certified repair networks).
-
For conservatories and institutional buyers: Use long-term contracts with staged price mechanisms and delivery clauses to manage supplier costs and secure supply of professional-grade instruments amid capacity constraints.
Recent sector signals — what to watch
-
Product and packaging innovation: Major brands are already implementing sustainability-led packaging changes to improve brand perception and reduce lifecycle cost—an easy win for retailers focused on ESG goals.
-
Cultural and exhibition momentum: High-profile exhibitions and regional recognition (e.g., the Boston artisan cluster) are driving awareness and premium demand, supporting aftermarket services and the second-hand market.
-
Policy catalysts: Government funding for music education in several emerging markets has become a structural tailwind for student instrument volumes and creates a predictable multi-year sales pipeline.
Accessing the full intelligence
This release highlights the strategic value and practical tools embedded in PW Consulting’s Flutes Instrument Market report. To preserve the commercial integrity of the underlying sub-segment tables and country-level forecasts, detailed region/application splits and proprietary model outputs are available exclusively in the full report. For procurement teams, product strategists, M&A advisors, and supply-chain leads preparing plans for 2026, the full study includes downloadable modelling assets, vendor scorecards, and scenario playbooks ready for immediate adoption.
Contact PW Consulting to request the full report and a tailored briefing, where we will walk through bespoke scenario runs with your assumptions and map specific actions to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Flutes Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com