

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: TDI 80/20 Market Poised for 3.8% CAGR in 2026–2032 as Asia‑Pacific Emerges as Market Leader

TDI 80/20 Market: Strategic Imperatives for 2026 — PW Consulting Releases TDI 80/20 Market TDI 80/20 TDI 80/20 TDI 80/20 TDI 80/20
Executive summary
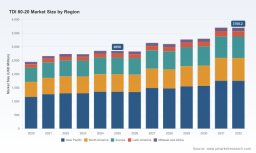
PW Consulting today publishes the TDI 80/20 Market chapter of the TDI 80/20 Market TDI 80/20 Market TDI 80/20 Market TDI 80/20 Market — the TDI 80/20 TDI 80/20 TDI 80/20 TDI 80/20 Market (TDI 80/20 Market) — a focused, decision-grade briefing designed for C-suite leaders, corporate strategy teams, and transaction advisors making capital-allocation and sourcing choices in 2026. The report combines a granular supply-side view, actionable demand scenarios, and a proprietary risk-adjusted forecast across the 2026–2032 horizon. It shows the global TDI 80/20 market reached approximately USD 2,850 Million in our 2025 base year and is projected to grow at a compound annual growth rate (CAGR) of 3.8% over the forecast period to reach roughly USD 3.7 Billion by 2032.
TDI 80/20 Market
Why this report matters for 2026 decisions
Three interlocking forces make 2026 an inflection year for companies that manufacture, purchase, or compete using TDI 80/20: an evolving cost structure driven by raw-material price volatility; tightening regulatory oversight on worker safety and chemical handling; and renewed capacity investments and plant modernizations by large incumbents reshaping regional flows and trade patterns.
TDI 80/20 Market
- Cost and margin sensitivity: Upstream feedstock swings are now a first-order margin driver for TDI producers and foam manufacturers. Procurement teams and CFOs must integrate realistic toluene price scenarios into multi-year sourcing and hedging strategies to protect margins.
- Regulatory and compliance pressure: TDI’s classification as a respiratory sensitizer, coupled with the expanding reach of REACH-like frameworks, is raising compliance and capital costs for both incumbent producers and new entrants. Operational readiness and monitoring systems are no longer optional.
- Supply-side consolidation and strategic investment: Recent capacity expansions and plant modernizations by major producers are accelerating a trend toward concentrated supply, changing negotiating leverage for buyers and opening differentiated strategic options for prospective entrants or consolidators.
What PW Consulting’s TDI 80/20 Market report delivers
This is a practitioner’s report engineered to answer the “so what” for executives. Key deliverables include:
TDI 80/20 Market
- Proprietary market sizing and a risk-weighted 2026–2032 forecast (CAGR 3.8%) with scenario sensitivity to raw-material shocks and demand-side elasticity.
- Supply-chain maps that reconcile plant-level capacities, recent commissioning events, and likely regional export flows — enabling procurement teams to stress-test single-supplier exposures and multi-sourcing options.
- Operational benchmarking and cost-stack analysis that decomposes manufacturing cost by feedstock, energy, utilities, and compliance expenditure, with tailored playbooks to improve EBITDA through feedstock sourcing, process optimization, and energy integration.
- Regulatory playbook outlining worker-safety thresholds, REACH implications, and international trade interventions — with recommended compliance investments and staged implementation timelines.
- M&A and partnership intelligence: a short list of high-priority targets by capability, not-by-number, and a valuation sensitivity matrix reflecting forward cash flows under different policy and price regimes.
- Commercial routes-to-market and product-mix optimization designed to capture higher value in downstream segments (e.g., technical foams, specialty coatings) without compromising supply security for commodity foam customers.
Segmentation and concentration — what the data imply
The TDI 80/20 market remains concentrated. Our concentration metrics show that the top three and top five players capture a majority share of the market, which has direct implications for bargaining power, capacity discipline, and the pace of price pass-through to downstream industries. The report includes a confidential, company-level roll-up of capacity and production economics that informs near-term tactical moves and long-term strategic positioning.
Competitive landscape: strategic takeaways
The competitive picture is dominated by a combination of large integrated chemicals groups and a set of regional champions. Key themes we highlight in the report:
- Scale plus integration wins in commodity segments: Producers with backward integration into aromatic feedstocks and large-scale phosgenation plants retain cost and security advantages for standard 80-20 grades supplied into high-volume flexible foam markets.
- Technology and efficiency differentiate in higher-margin pockets: Firms deploying advanced gas-phase phosgenation or energy-recovery modernization projects are materially reducing unit energy costs and emissions intensity, enabling profitable supply into premium downstream applications.
- Regional champions shape local supply security: In several markets, domestic or regional producers fill critical demand needs where trade barriers or logistics economics blunt global arbitrage, underscoring the importance of diversified sourcing strategies for multinational buyers.
Illustrative recent developments that shape these dynamics are covered in the report and are directly relevant to commercial planning in 2026:
- Large-scale capacity additions by a global chemical group that materially expand their output footprint and regional export options.
- Plant modernization programs that deliver step-change reductions in energy consumption and CO2 emissions, improving competitive positioning in sustainability-sensitive customer segments.
- Targeted trade measures from national authorities that can reroute trade flows and create spot-market dislocations in import-dependent regions.
Industry dynamics and risk factors
The report synthesizes macro- and micro-level drivers into a calibrated risk matrix. Highlights include:
- Upstream cost volatility: Toluene price excursions are rapidly transmitted through to TDI manufacturing costs. Our base, upside, and downside scenarios quantify exposure for both producers and foam converters, and the report prescribes hedging and contractual structures to mitigate these risks.
- Regulatory tightening: Occupational exposure limits and chemical registration regimes are increasing operating complexity and capital outlays—especially for smaller producers. The report maps regulatory exposures by operating model and offers a compliance-cost playbook that balances capital upgrades against contractual pricing adjustments.
- Trade and policy shocks: Anti-dumping measures and safeguard duties continue to be a lever used by national authorities to protect domestic producers. The report analyzes recent measures and models their potential market impacts under different enforcement durations.
- Decarbonization and energy transition: Energy and emissions intensity have emerged as commercial differentiators. We quantify the return on modernization investments—including energy integration projects that recycle reaction heat to generate steam—and the report provides a prioritized investment roadmap to reduce unit carbon exposure.
Practical implications for stakeholders
For corporate strategy teams and procurement leaders, the PW Consulting analysis suggests a small set of high-impact moves for 2026:
- Reassess supplier concentration against the concentrated market structure: establish contingency capacity contracts or strategic inventory cushions for critical feedstocks and finished product delivery windows.
- Accelerate capital projects that reduce energy intensity and compliance risk where IRRs exceed the organization’s hurdle rate under conservative feedstock scenarios.
- Embed regulatory scenario planning into commercial contracts to insulate margins against compliance-driven cost increases and trade-policy shifts.
- Evaluate bolt-on M&A or strategic partnerships to secure feedstock access, regional distribution capabilities, or specialty-grade capability that offers higher margin and lower commodity cyclicality.
Methodology and confidence
Our forecast and scenario work combine bottom-up plant-by-plant capacity analysis, proprietary commodity price trajectories, and demand elasticity models calibrated to historical demand patterns. We overlay regulatory and trade-policy stress tests to produce a range of outcomes—providing both a most-likely projection (CAGR 3.8% across 2026–2032) and alternative paths under sustained feedstock shocks or accelerated substitution in downstream applications.
What is intentionally withheld
Consistent with the “trailer” approach, this release presents strategic findings and headline macro metrics to inform executive decisions. To preserve the actionable edge for subscribers, detailed segment tables, region- and application-level splits, producer-specific capacity schedules, and full plant-level economics are available only in the full TDI 80/20 Market report on our website. These datasets include the granular figures and proprietary models that underpin the analysis summarized here and are the assets we provide clients to operationalize strategic choices.
Call to action
Executives facing sourcing decisions, capital allocation choices, or M&A opportunities in the polyurethane value chain should use 2026 to build resiliency into supply chains and to capture margin through operational and regulatory readiness. PW Consulting’s full TDI 80/20 Market report delivers the datasets, scenario models, and playbooks you need to move from insight to action. Visit our site to access the full report, downloadable datasets, and a schedule for our upcoming client briefings.
For tailored briefings, scenario work, or to commission a supplier-stress test, contacts and engagement options are available through PW Consulting’s industry practice.
For detailed analysis of this topic, please visit the official page: TDI 80/20 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com