

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Asia Pacific Dominates Lead Based Rare Earth Alloy Market with USD 145.06 Million Market Size in 2025

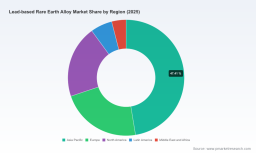
Lead-Based Rare Earth Alloy Market — Strategic Insights for 2026: Executive Brief from PW Consulting
PW Consulting’s latest market research on the Lead-Based Rare Earth Alloy market provides a timely, actionable foundation for corporate strategy as companies plan investments, supply-chain adjustments, and product roadmaps for 2026. Our analysis synthesizes historical dynamics (2020–2025), a base-year assessment (2025), and forward-looking projections through 2032. The brief below highlights the report’s strategic value to decision-makers while preserving the report’s proprietary segment-level detail — a deliberate “trailer” to invite deeper engagement with our full publication.
Lead Based Rare Earth Alloy Market
Market trajectory and headline metrics
After a period of uneven recovery and modest expansion, the global Lead-Based Rare Earth Alloy market reached an estimated USD 306.0 Million in 2025 (base year). Under our central scenario, the market is forecast to grow to roughly USD 430.6 Million by 2032, driven by steady demand in battery-related and industrial end-uses and incremental replacement cycles in legacy products. This trajectory implies a 5.0% compound annual growth rate over the 2026–2032 forecast window — large enough to justify near-term strategic moves but gradual enough that capital allocation should be staged and stress-tested.
Lead Based Rare Earth Alloy Market
Why this report matters for 2026 decisions
- Actionable timing for capex and sourcing: With mid-single-digit CAGR ahead, 2026 is a pivotal year for choices between expanding production capacity, locking in long-term off‑take agreements, or investing in recycling and substitution research. Our report maps the optimal timing and sequencing of these options under multiple price and policy scenarios.
- Risk-adjusted investment cases: We translate macro forecasts into risk‑adjusted return profiles for different strategic plays — from incremental alloy capacity to greenfield rare‑earth metallization lines. Each case includes sensitivity to rare‑earth feedstock price shocks, regulatory cost pass-through, and product-mix shifts.
- Commercial playbooks: For sales and marketing leaders, the report provides go‑to‑market approaches tailored to incumbent OEM relationships, aftermarket channels, and new battery chemistries, framed against customer purchasing cycles and qualification timelines.
Structural dynamics shaping 2026 strategies
Our 2026-focused analysis identifies five structural dynamics that should drive boardroom conversations:
Lead Based Rare Earth Alloy Market
- Upstream feedstock volatility: Rare earth feedstock costs have shown acute volatility; recent industry reports document quarter-over-quarter price surges in concentrate pricing well into 2026. Our report quantifies the exposure of typical alloy value chains to such moves and offers hedge and procurement strategies that can materially protect margins.
- Regulatory tightening on lead handling: Environmental and occupational health requirements for lead production, transport, and end‑use continue to tighten in multiple jurisdictions. Compliance-driven capex and operational changes will be an unavoidable cost of doing business; however, early movers can convert compliance into a competitive moat.
- Policy-driven capacity shifts: Government funding and loan programs aimed at expanding domestic rare-earth and alloy manufacturing capacity have accelerated capacity investments in select markets. Our scenarios contrast outcomes for firms that partner with public programs versus those that pursue purely commercial expansions.
- Product and process innovation: Incremental rare-earth additions remain a high‑value lever for improving lead-acid battery grid performance. Simultaneously, emerging manufacturing techniques and recycling pathways are beginning to alter raw‑material intensity and lifecycle economics.
- Market concentration and competitive positioning: The market exhibits a moderate-to-high degree of concentration among a handful of vertically integrated producers alongside specialized alloy fabricators. Top-tier consolidation gives established players pricing leverage in stable conditions but creates vulnerabilities in supply resilience and regulatory exposure during episodes of raw-material stress.
Competitive landscape — practical implications
Key incumbent profiles in our coverage include large, vertically integrated Chinese producers with upstream metal resources, integrated non‑ferrous groups leveraging zinc/germanium/lead portfolios, and specialist alloy manufacturers focused on product forms and customization. The competitive spectrum runs from mass producers offering scale and integration benefits to niche suppliers delivering high‑purity master alloys, custom shapes, and value‑added processing.
- Integrated producers are strengthened by upstream feedstock access and, in many cases, captive recycling streams. Their strategic choices in 2026 will likely emphasize margin protection via vertical capture, longer-term supply contracts, and selective downstream partnerships.
- Specialized manufacturers, including firms focused on master-alloy forging, strip/foil, and advanced forms, can compete on speed-to-market, tailored specifications, and grades for performance-critical applications. Their 2026 options include capacity modularization, qualification acceleration with OEMs, and targeted alliances with raw-material providers.
- Consolidation logic is active: the market’s concentration levels mean M&A remains a credible route to secure raw material, access new geographies, or acquire niche technological capabilities. Our report contains an M&A checklist that prioritizes targets by strategic fit and integration risk.
Supply‑chain stress tests and price sensitivity
One of the report’s most practitioner‑oriented modules is a set of stress tests that model P&L and cashflow outcomes under multiple raw‑material and regulatory shocks. For 2026 planning, management teams should pay particular attention to:
- Short-term price spikes in rare-earth feedstock and their pass-through mechanics into finished alloy pricing.
- The lag between raw-material inflation and customer contract repricing, especially in legacy battery OEM relationships.
- Logistics and permit delays driven by stricter environmental controls, which can produce episodic supply bottlenecks even absent demand shocks.
What’s inside the full PW Consulting report (high-level)
Our deliverable is built for commercial and technical leaders who need both strategic framing and operational playbooks. Key contents include:
- Multi-scenario demand forecast (2026–2032) with transparent assumptions and sensitivity ranges.
- Supply-side capacity tracker and capex pipeline across primary and secondary (recycling) sources.
- Supplier and raw‑material risk matrix, including counterparty exposure and concentration metrics.
- Competitive benchmark profiles covering integrated producers and specialist Alloy manufacturers.
- Regulatory timeline and compliance cost estimator for major jurisdictions.
- Commercial playbooks: pricing strategies, contract structures, and qualification timeframes for battery OEMs and industrial customers.
- Technology and patent landscape overview, highlighting practical R&D pathways and potential disruptors.
Strategic recommendations for 2026
Based on the analysis, PW Consulting recommends that market participants prioritize the following actions in 2026 to maximize optionality and minimize downside:
- Hedge selectively and negotiate staggered off‑takes: Use a mix of fixed-price and formula contracts to balance cost certainty and upside participation in a volatile raw‑material environment.
- Invest in compliance-forward brownfield upgrades: Prioritize investments that reduce emissions and improve worker safety while increasing production efficiency; such investments reduce regulatory tail‑risk and can improve access to financing.
- Pursue flexible capacity expansion: Favor modular, scalable assets and consider tolling or JV structures that limit upfront capex while securing processing capacity.
- Accelerate product qualification pipelines: Shorten time-to-market for higher-value alloy grades and specialty forms via pre‑competitive collaboration with OEMs and testing houses.
- Explore alliances for feedstock diversification: Combine upstream partnerships with recycling initiatives to reduce reliance on single-source concentrate supplies.
How PW Consulting’s proprietary tools support implementation
Subscribers to the full report gain access to our proprietary models: an off‑the‑shelf scenario builder, a supplier risk dashboard, and a commercial playbook template that can be tailored to an individual company’s balance sheet and customer mix. We also provide a condensed executive workshop package designed to align C-suite decision-making and convert report insights into a 100‑day action plan.
Final note — market signal and the path forward
Our top-line market math signals steady, meaningful growth rather than explosive expansion. That pattern favors strategic discipline: prioritize resilience, flexible growth, and selective vertical moves over aggressive capacity bets that assume persistently low raw‑material volatility. For 2026, the most valuable corporate moves will be those that improve optionality and reduce exposure to concentrated upstream risks while securing differentiated product capabilities.
To view the full segmentation, granular regional and application forecasts, and the proprietary datasets that underpin our scenario models, please consult the complete PW Consulting Lead-Based Rare Earth Alloy Market report on our website. The report includes the detailed segmentation, vendor scorecards, and transaction-ready annexes that boards and investor committees need to finalize 2026 capital and commercial plans.
For detailed analysis of this topic, please visit the official page: Lead Based Rare Earth Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com