

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LCP Antenna Market Poised to Surge at a 17.98% CAGR Through 2026–2032, New Insights Reveal

LCP Antenna Market 2026: Strategic Imperatives for Industry Leaders
PW Consulting today publishes a forward-looking synthesis from our LCP Antenna Market report, designed to arm executives with the strategic perspective they need to make high-consequence decisions in 2026. Our analysis combines a data-driven demand-supply model, scenario stress tests, and an actionable playbook for device OEMs, tier-1 suppliers, materials producers, and financial sponsors navigating a fast-growing, concentrated, and geopolitically exposed segment of the RF value chain.
Lcp Antenna Market
Why 2026 is a Strategic Inflection Point
The LCP antenna market has transitioned from nascent adoption to commercial scale in under a decade. Our model shows the global market expanding at a compound annual growth rate (CAGR) of 17.98% through the forecast window, with the market more than doubling from the 2025 base. This pace of growth is concentrated in high-frequency 5G mmWave implementations for handsets and emerging automotive, IoT and infrastructure use cases—creating a time-limited opportunity for design wins, capacity investments, and supplier consolidation.
Lcp Antenna Market
- Acceleration of high-frequency demand: Continued mmWave rollouts and denser antenna integration in premium mobile devices mean suppliers who secure early design wins will enjoy outsized revenue leverage.
- Material and supply-side constraints: Liquid crystal polymer (LCP) feedstocks and film-grade resins remain limited by a compact supplier base and specialized monomer inputs, which introduces price and lead-time volatility.
- Regulatory and trade friction: Certification complexity (FCC, CE) combined with tariff differentials on polymer-based components increases the operational and commercial complexity for cross-border supply chains.
Market Health: Scale, Concentration and Resilience
By the 2025 base year, the addressable market has achieved solid scale, and our 2026 baseline projects continued robust expansion. Crucially, market concentration is meaningful: the top three suppliers account for roughly 62% of revenue, while the top five approach 78%—a structure that shapes bargaining power, technology standard-setting, and consolidation dynamics. For buyers and investors, this concentration creates both stability in proven suppliers and tactical risk when single-source dependencies emerge.
Lcp Antenna Market
What Matters Most to Decision-Makers in 2026
Companies facing investment and sourcing decisions should prioritize three practical agendas:
- Control over the material stack: Firms that secure long-term LCP resin and film supply—through contracts, tolling, or minority investments—will reduce exposure to price spikes and allocation risk. The LCP value chain depends on a limited number of polymer producers whose capacity moves slowly relative to demand shocks.
- Design-to-manufacturing integration: Winning at mmWave requires tight alignment across antenna design, substrate selection, and module assembly. Suppliers that offer integrated antenna-in-package solutions or validated reference designs shorten OEM time-to-market and reduce NRE for handset makers.
- Flexible commercial models: As tariffs and compliance obligations vary by region, flexible pricing frameworks and localized inventory strategies will be decisive for margin protection and supplier selection.
Competitive Landscape: Who’s Setting the Technical Bar
Our competitive benchmarking highlights a mix of entrenched multinational suppliers and rapid-scale regional players. Several firms stand out for different strategic reasons:
- Murata Manufacturing: Positioned as a technology leader with high-frequency antenna-in-package modules at commercial volumes. Recent capacity ramp of compact 28 GHz modules demonstrates ability to convert R&D into mass production quickly.
- Amphenol and Molex: Broad systems portfolios and deep OEM relationships enable these players to bundle antenna solutions with interconnects, accelerating adoption across smartphones and automotive platforms.
- Luxshare, Sunway, Holitech, and regional specialists: These vendors excel at high-volume manufacturing for consumer electronics and are expanding into mmWave designs, leveraging proximity to major handset OEMs to capture design wins.
- Materials and substrate specialists (Fujikura, Sumitomo, Flexium, Avary): Their differentiated capabilities in LCP flexible boards and film substrates underpin the ecosystem, and their collaboration with module assemblers will be essential to meeting evolving electrical and mechanical specifications.
Recent product and capacity moves underscore the competitive tempo: mass production starts for compact 28 GHz modules and new LCP-based modules that materially reduce high-frequency insertion loss have shortened the development cycle and raised the bar for late entrants. For full company profiles and our supplier scorecard, the report provides side-by-side technical, commercial, and risk ratings to support sourcing decisions.
Supply-Chain Dynamics and Raw Material Risk
Raw material dynamics are a defining constraint for the next 24–36 months. A small group of LCP resin producers account for a dominant share of global capacity—a structural feature that means upstream outages, acquisitions, or capacity reallocation can transmit rapidly through the supply chain. At the same time, nascent film-grade resin production in China introduces near-term alternative supply but with qualification timelines and quality variability to consider.
Compounding this are geopolitical and trade factors: cumulative tariffs and specific measures on polymer-based electronic components raise landed costs for cross-border procurement and influence localization decisions. Additionally, specialty monomers used in LCP manufacture are at risk of supply tightness and lead-time extension—factors companies should include in stress-tested procurement models.
What the Report Delivers: Practical, Executable Content
Rather than a high-level market overview, PW Consulting’s LCP Antenna Market report is built for operators and investors who must decide in 2026. Key deliverables include:
- Bottom-up market sizing with audited historicals and a seven-year forecast, plus sensitivity bands and two alternate scenarios tied to device adoption and trade policy shocks.
- Supplier landscape with technical scorecards, manufacturing footprints, and a CR-driven competitive overlay that highlights concentration risks and potential acquisition targets.
- Raw material mapping: an upstream supply map, capacity dynamics, resin qualification timelines, and procurement strategies to mitigate allocation risk.
- Technology benchmarking and thermal/RF performance comparisons for leading LCP substrates and antenna module architectures.
- Commercial playbooks: sourcing templates, dual-sourcing architectures, pricing pass-through clauses, and inventory hedging frameworks suited to different corporate risk appetites.
- M&A and partnership playbooks: target screens, valuation bucketing for bolt-on versus platform deals, and integration checklists tailored for antenna/module assets.
- Financial modelling tools: unit-cost build-ups, break-even timelines for CAPEX investments, and ROI scenarios for in-house substrate production versus contract manufacturing.
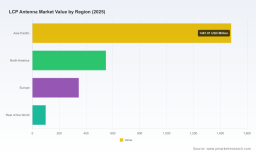
To honor the “trailer” purpose of this release, we deliberately withhold detailed regional and application splits, company-level revenue tables, and cell-level sensitivity matrices—these are available in the full report and accompanying datasets for clients who require hands-on models.
Actionable Recommendations for 2026 Decision Planning
- For OEMs: Move critical design-in activities forward now. Negotiate conditional allocation clauses with top suppliers and establish secondary qualified vendors to avoid late-stage production friction.
- For Tier-1 Suppliers: Prioritize integrated antenna-in-package offers and accelerate co-development with chipset and RF front-end partners to reduce system-level integration risk.
- For Materials Producers and Investors: Evaluate selective capacity expansion near regional demand centers with a focus on quality control, not just volume—film-grade resin qualification wins are sticky commercial assets.
- For Private Equity and Strategic Buyers: Look for consolidation targets that provide both upstream exposure (substrates/resin) and downstream channel access (module assembly/design wins).
Conclusion: Use 2026 to Convert Adoption into Advantage
The LCP antenna market presents a classic “window” of opportunity: rapid top-line growth, technical complexity that benefits incumbents, and supply constraints that reward foresighted investments and partnerships. Companies that translate this understanding into disciplined supplier strategies, design advantages, and targeted capital allocation will secure durable commercial benefits through the next growth cycle.
PW Consulting’s LCP Antenna Market report is crafted to be the playbook executives use during that conversion. For the complete data tables, regional and application breakdowns, company scorecards, and customizable financial models, access the full report and supporting datasets on our website.
For detailed analysis of this topic, please visit the official page: Lcp Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com