

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Heat Transfer Vinyl Market to Expand at a Steady 6.45% CAGR Through 2032

Heat Transfer Vinyl Market 2026: Strategic Imperatives for Growth, Resilience and Sustainable Innovation
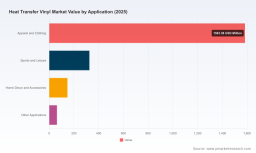
PW Consulting’s latest Heat Transfer Vinyl (HTV) Market report synthesizes five years of market dynamics with a seven-year forward view to deliver decision-grade intelligence for 2026. The HTV industry has evolved from a niche garment-decorating input to a diversified materials and services ecosystem. Our research shows the global HTV market expanding from approximately USD 1,560.4 Million in 2020 to USD 2,120.5 Million in 2025, with a projected trajectory to roughly USD 3,284.4 Million by 2032—reflecting a 6.45% compound annual growth rate across the forecast horizon. For commercial leaders, procurement heads, product teams and private equity investors, these headline metrics are only the starting point: the real strategic value lies in operational levers, risk scenarios and product-roadmap alignment that materially affect margin, agility and market positioning in 2026.
Heat Transfer Vinyl Market
Why 2026 Is a Pivot Year
-
Supply and cost volatility is re-emerging as a principal operational risk. Raw material pressures—most notably movements in PVC resin pricing—are already influencing supplier cost structures and short-term availability. Our market model incorporates recent upstream tightness and scenario sensitivity for major resin inputs to quantify margin exposure across manufacturing and distribution chains.
Heat Transfer Vinyl Market -
Regulatory momentum and buyer preference are accelerating a material shift. The industry is seeing a discernible migration from legacy PVC formulations toward polyurethane (PU) and polyester-based films driven by performance advantages and stricter chemical and waste regulations in key markets.
Heat Transfer Vinyl Market -
Channel fragmentation and new customer archetypes (from mass-customization hobbyists to high-performance sportswear brands) are reshaping supply models and go-to-market priorities. Platforms, tools and bundled hardware (cutters, presses, DTF/DTG integrations) are changing the nature of supplier relationships.
Strategic Implications for Corporate Decision-Makers
-
Prioritize material resiliency over short-term cost: Companies that build flexible sourcing strategies across PU and PVC alternatives, and that hedge or index key resin exposures, will protect gross margins while negotiating premium pricing on differentiated products.
-
Turn sustainability compliance into a competitive moat: With tightened EU and North American chemical and waste standards, investing in low-VOC, phthalate-free and recyclable HTV formulations is both a risk mitigation and demand-creation play. Product roadmaps that embed circularity and transparent material declarations will win retail and institutional contracts.
-
Capture value from tooling and platform ecosystems: Hardware–consumable ecosystems (e.g., cutters, presses, and integrated printer systems) are expanding the addressable market to prosumers and micro-businesses. Strategic partnerships or channel programs that reduce friction for these customers will increase recurring consumable demand and customer lifetime value.
-
Design for differentiation, not parity: As core HTV commoditization continues in certain segments, margin accretion will depend on specialty formulations (stretch, glitter, reflective, printable) and services (custom prepress, color matching, just-in-time small-batch fulfilment).
-
Model multiple pricing and supply scenarios: Our scenario suite quantifies P&L impacts across alternative raw-material price paths and adoption rates for PU over the forecast period—delivering required breakeven points for capex and new product investments.
Competitive Landscape — Tactical Takeaways
The HTV sector sits in a middle ground between specialized chemical producers and graphical-material distributors. Consolidation remains limited—our concentration metrics indicate meaningful fragmentation at the top, leaving space for regional champions and niche innovators.
-
Siser (Siser Srl / Siser North America) : Market reputation and product breadth (EasyWeed and specialty ranges) create strong brand equity among commercial decorators and hobbyists. Strategy: protect technology leadership through faster product lifecycle management, expand technical support for industrial OEMs, and formalize licensing or co-development agreements for printable and specialty lines.
-
B-Flex Italia : Premium positioning and a broad SKU base make B-Flex a formidable supplier to fashion and specialty segments. Strategy: deepening logistics and vertical integration in the Americas and APAC will reduce lead times and provide pricing flexibility versus raw-material shocks.
-
Stahls' : The recent North American distribution partnership for Siser strengthens its access to end-customers and consolidates channel control. Strategy: expand value-added services—training, rental/lease programs for heat presses, and certification for commercial decorators—to increase consumable turnover.
-
Avery Dennison : Portfolio expansion into RFID-enabled and durable heat transfer films signals a move beyond simple decoration into traceability and smart-packaging/garment use-cases. Strategy: pursue cross-selling into brand apparel programs and seek strategic tuck-ins that enhance thermal/adhesive technology.
-
Cricut, Inc. : The consumer-facing ecosystem (cutters + consumables) remains a gateway for mass-customization. Cricut’s new heat press product exemplifies platform monetization. Strategy: suppliers should create OEM or co-branded consumable lines and integrate with Cricut’s software to capture hobbyist repeat purchases.
-
Regional and performance players (ORACAL/Orafol, Arlon, Specialty Materials, Picon, Zhejiang YGM, Poli-Tape, Chemica, CDFLEX) : These firms provide critical diversity in formats, specialty finishes and price points. Strategy: larger buyers should run dual-sourcing playbooks and use technical benchmarking to optimize SKU rationalization across markets.
Supply Chain, Raw Materials and Cost Management
PVC market movements in early 2026 have already prompted price repricing and tightened supply in some corridors. China’s domestic resin pricing and U.S. turnarounds create localized shortages and shipping delays—factors reflected in our short-term stress scenarios. For 2026 planning, procurement leaders should:
-
Implement flexible contracting with index-linked clauses for resin inputs and consider regional second-source suppliers to avoid single-point failure.
-
Accelerate validation of PU and polyester substitutes where material performance meets specs, capturing both regulatory compliance and improved abrasion/flexibility performance.
-
Invest in upstream visibility tools and collaborative demand planning with tier-1 suppliers to reduce order lags and inventory carrying costs.
Sustainability and Regulation: From Compliance to Revenue
Regulatory developments are no longer only compliance checkpoints—they are product and go-to-market levers. Our research identifies meaningful opportunities for first-mover premiumization in certified low-VOC, phthalate-free and recyclable HTV products. Companies that can substantiate environmental claims with verifiable supply-chain data and certified testing stand to capture tenders from institutional buyers and large apparel brands seeking chain-of-custody assurance.
What the PW Consulting Report Provides (Practical, Actionable Deliverables)
-
Executive dashboards and scenario models that quantify margin exposure under alternative resin-price and adoption-rate assumptions.
-
Supplier scorecards and a capability matrix across chemistry, finish, geographic footprint and channel reach—enabling rapid shortlist creation for sourcing teams.
-
Go-to-market playbooks for OEM partnerships, channel distribution, and D2C/prosumer engagement, including sample commercial terms and margin waterfalls.
-
M&A and partnership target screening with valuation sensitivities driven by scale, IP ownership and channel access.
-
Product innovation roadmaps and technical checklists for migrating formulations away from regulated chemistries without compromising performance.
-
Operational readiness templates for manufacturing scaling, CAPEX triggers and staffing plans keyed to demand inflection points.
How Senior Leaders Should Use This Intelligence in 2026
-
Board level: Use our scenario outputs to stress-test capital allocation decisions, especially for investments in new production lines or acquisitions focused on PU capability.
-
Commercial teams: Re-evaluate pricing ladders and channel margins with sensitivity to rising resin costs and increasing buyer willingness to pay for sustainable credentials.
-
R&D and product management: Prioritize swap-in formulations and certification roadmaps that meet upcoming EU/North American standards; accelerate market trials with strategic retail partners.
-
Procurement & operations: Implement dual-sourcing with indexed contracts and synchronized planning cycles to reduce lead-time risk from planned plant turnarounds or supply tightness.
Conclusion — The Strategic Choice
By 2026, success in HTV will be determined by three capabilities: material agility, channel orchestration, and sustainability authenticity. PW Consulting’s HTV Market report is designed as a practical playbook—grounded in quantitative forecasting and qualitative competitor analysis—to inform those capability investments. We provide the frameworks and the data-flex that empower companies to make defensible, revenue-driven choices without overexposing their teams to speculative operational risk.
For executives seeking the detailed segmentation, supplier profiles, and downloadable scenario models that underpin the recommendations above, the full PW Consulting report delivers those confidential appendices and interactive tools. Access the complete study via our official report page to move from insight to implementation this fiscal year.
For detailed analysis of this topic, please visit the official page: Heat Transfer Vinyl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com