

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Microtubule Inhibitor Drugs Market to Reach USD 5,601.26 Million by 2032

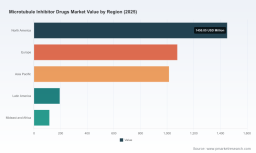
Microtubule Inhibitor Drugs Market: Strategic Preview for 2026 — Why This Report Is a Decision-Maker’s Compass
PW Consulting today releases an executive preview of our forthcoming Microtubule Inhibitor Drugs Market research report — a practitioner-focused intelligence package designed to inform high-stakes decisions across R&D prioritization, commercial strategy, M&A, and payer engagements in 2026. The market for microtubule-targeting therapies has demonstrated resilient growth through the last five years and is entering a phase of tactical realignment driven by next-generation antibody‑drug conjugates (ADCs), evolving regulatory pathways, and concentrated supplier footprints. This preview highlights the strategic value of our full report for senior executives while reserving the granular segment tables and proprietary model outputs for report access.
Microtubule Inhibitor Drugs Market
Market trajectory: durable growth with strategic inflection points
From a historical base covering 2020–2025, the microtubule inhibitor drugs market expanded steadily, reflecting both continued demand for established agents and the emergence of novel ADC constructs. In numeric terms, the market size increased meaningfully from the start of the historical period and reached a notable base in 2025 (base year). Our forecast period extends from 2026 through 2032, during which PW Consulting projects the market to grow at a compound annual growth rate (CAGR) of approximately 5.5%. By the end of the forecast window the market is expected to be materially larger than in 2025, underscoring both sustained clinical demand and the commercial lift from new approvals and optimized combination regimens.
Microtubule Inhibitor Drugs Market
Two takeaways for 2026 planners: first, microtubule inhibitors remain a core backbone across multiple oncology indications; second, the shape of future revenue pools will be re-determined less by legacy brands and more by how companies deploy microtubule payloads in targeted ADC platforms, navigate regulatory accelerations, and secure payer access.
Microtubule Inhibitor Drugs Market
Why this report matters for 2026 corporate strategy
- Portfolio prioritization: Our analysis maps total-market dynamics against product life-cycle stages, enabling rapid triage of in-house assets and licensing prospects. Companies can use the framework to decide whether to invest in incremental label expansions, pursue ADC payload collaborations, or divest underperforming legacy assets.
- Launch sequencing and go‑to‑market: The report provides scenarios for launch sequencing across indications and geographies, integrating regulatory timing, expected reimbursement pressure points, and competing mechanisms of action — essential for sequencing clinical development and commercial rollouts in 2026.
- M&A and partnering playbook: We identify structural opportunities where scale, payload expertise, or targeted biologics capabilities create disproportionate value. Our deal-screening matrix highlights the types of assets that would accelerate commercial positioning versus those that primarily add defensive breadth.
- Reimbursement and pricing strategies: With payer environments tightening, the practical frameworks in the report help shape health economic dossiers, RWE plans, and price-volume trade-offs across orphan and broader oncology indications.
- Manufacturing and supply-chain investments: The report assesses capacity risk for key APIs and payload intermediates, supporting capital-allocation decisions for 2026 that reduce bottlenecks while optimizing time-to-market.
Contents at a glance — actionable deliverables
PW Consulting’s full report is intentionally operational. Highlights include:
- Proprietary market model (historical 2020–2025, forecast 2026–2032) with sensitivity scenarios;
- Pipeline heat map and clinical-stage asset reviews focusing on microtubule-stabilizers, non-taxane inhibitors, and ADC payload candidates;
- Commercial opportunity assessment and launch-scenario playbooks for prioritized indications;
- Regulatory pathway analysis and approval-timing scenarios with implications for accelerated approvals and confirmatory requirements;
- Reimbursement strategy templates, including HTA evidence generation plans and payer negotiation checklists;
- M&A and partnering scorecards, with target archetypes and valuation implications under differing uptake scenarios;
- Risk registers covering supply, price pressure, IP exposure, and biosimilar/generic erosion;
- Customizable slide decks and model extracts for executive briefings and board-level decision-making.
Competitive landscape: concentrated but dynamic
The microtubule inhibitor market remains moderately concentrated: the top three players account for a substantial share of the market, and the top five extend market control further. This concentration creates both barriers and windows for entrants. Incumbents with integrated development and commercial capabilities will retain advantages in scale, while nimble biotechs can carve niches by combining payload chemistry with targeted antibody platforms.
Key company profiles examined in the report include (non-exhaustive):
- Pfizer Inc. — A major incumbent with long-standing microtubule products and deep commercialization experience across multiple solid tumors. Pfizer’s generics and brand-management strategies are discussed in context of lifecycle defense and new combination opportunities.
- Sanofi S.A. — Notable for cabazitaxel in prostate cancer; Sanofi’s strategy illustrates how differentiated formulations and label extensions can prolong commercial relevance.
- Bristol‑Myers Squibb — With ixabepilone and ADC R&D linkages, their approach exemplifies integrating microtubule stabilizers into next-gen payload strategies.
- Eisai Co., Ltd. — Eribulin’s profile offers lessons on maintaining niche leadership and pursuing tertiary-indication expansions.
- Eli Lilly — Active across oncology with growing interest in payload integration and combination regimens.
- AbbVie Inc. — A case study on how regulatory success (e.g., accelerated approvals) can create immediate commercial runway for ADCs with microtubule payloads.
Regulatory and clinical catalysts shaping 2026
Recent regulatory actions underscore a sectoral turning point. In 2025, the U.S. FDA granted accelerated approval to a c‑Met‑directed ADC containing a microtubule inhibitor payload for select NSCLC patients, and later approved a BCMA‑directed ADC for relapsed/refractory multiple myeloma. These approvals validate the payload approach and create precedents for accelerated pathways tied to biomarker-defined populations. The regulatory momentum increases the strategic value of payload chemistry leadership and companion-diagnostic co-development.
For 2026, executives must evaluate the implications of these catalysts through three lenses:
- Clinical differentiation: Is your payload-antibody pairing superior on therapeutic index and biomarker concordance?
- Regulatory risk-reward: Can accelerated approvals be leveraged as de-risked commercial entry points while planning confirmatory programs?
- Payer acceptance: Will payers accept biomarker-driven premium pricing, or require outcome-based contracting aligned to real-world survival and safety endpoints?
ADC momentum and payload economics
Microtubule inhibitor payloads — particularly those used in ADC constructs — continue to hold strong commercial positioning across several oncology areas. The increasing number of ADC approvals and the crowded payload supply chain mean companies must make deliberate choices about in‑licensing versus internal development of payload chemistry, scale-up capital, and intellectual property live issues. Our full report includes a payload-cost sensitivity analysis and a supplier-risk heatmap to guide procurement and partnership negotiations in 2026.
Strategic playbook for decision-makers in 2026
Executives can use the insights in our full report to assemble a practical 12–36 month playbook. Typical recommended actions we outline include:
- Prioritize programs where biomarker prevalence, clinical benefit, and pricing power align to create a clear ROI within a 3–5 year horizon;
- Secure early partnerships for payload supply or co-development with established ADC developers to accelerate time-to-market and share regulatory burdens;
- Strengthen RWE and HEOR capabilities now to support reimbursement submissions for accelerated-approval assets and to prepare for outcome-based contracting pilots;
- Evaluate M&A or bolt-on licensing targets that deliver either payload expertise or rapid access to companion‑diagnostic capabilities;
- Build flexible manufacturing agreements and dual-sourcing strategies to mitigate single-supplier disruptions for critical intermediates.
What we are intentionally holding back — and why
In keeping with the “trailer” principle, this release highlights strategic conclusions and the nature of the evidence supporting them without disclosing the proprietary, granular segmentation tables and financial model outputs that underpin our recommendations (for example, detailed regional splits, application breakdowns, and company-level revenue forecasts). Those elements are embedded in the full report and interactive model — essential tools for transaction diligence, in‑house valuation, and scenario planning.
Access to the full report provides the detailed segmentation, company scorecards, and downloadable model that strategy teams need to move from insight to action.
Next steps
- Download the full report to obtain the complete forecast model, segmentation matrices, and company dossiers;
- Schedule a PW Consulting briefing to walk your executive committee through tailored scenarios for portfolio rebalancing, M&A targets, or launch sequencing;
- Engage our advisory team for bespoke deep‑dives — for example, a payload sourcing due diligence, payer readiness assessment, or RWE study design ahead of pivotal submissions in 2026.
PW Consulting’s Microtubule Inhibitor Drugs Market report is built for leaders who must translate a shifting clinical and regulatory landscape into concrete commercial and R&D choices. As competition concentrates and ADCs reshape value pools, the ability to pair robust market modeling with pragmatic playbooks will determine which organizations convert scientific opportunity into sustainable commercial advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Microtubule Inhibitor Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com