

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
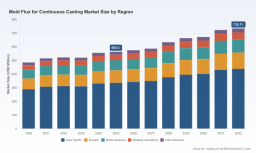
PW Consulting: Mold Flux for Continuous Casting Market Valued at USD 564.3 Million in 2025 to Expand at 3.85% CAGR During 2026–2032

Mold Flux for Continuous Casting Market: Strategic Insights for 2026 Decision-Making
Executive snapshot
PW Consulting’s latest market research on Mold Flux for Continuous Casting positions this specialty materials market at the intersection of metallurgical performance, environmental regulation, and regional capacity shifts. Anchored on a 2025 base year and covering 2020–2025 history with a 2026–2032 forecast window, the study finds the global market expanding steadily at an expected compound annual growth rate (CAGR) of 3.85%. From a mid‑decade valuation in 2025, our model projects material expansion through 2032, driven by both incremental steelmaking output and product-innovation adoption that reduces process losses and improves slab/billet quality.
Mold Flux For Continuous Casting Market
Why 2026 matters for executives
- Policy and product inflection: 2026 is already showing decisive movement toward low‑fluorine and fluorine‑free flux chemistries, and early commercial-scale trials for carbon‑free powders are entering ramp phases. These trends will materially affect reformulation timelines, supplier qualification cycles, and capex for handling alternative raw materials.
- M&A and platform consolidation: Strategic transactions executed in 2025–2026 reflect accelerating consolidation among technology-focused players that can offer integrated supply and technical services. Buyers and integration managers need playbooks now to capture synergies without disrupting metallurgical continuity at steelworks.
- Supply‑chain recalibration: Raw material variability and regional capacity additions—particularly in South Asia—mean procurement and logistics teams must move from annual spot buys to multi‑year commitments and blended sourcing strategies to ensure powder consistency.
Market dynamics: what is changing and why it matters
Three dynamics dominate the near term.
Mold Flux For Continuous Casting Market
- Technological evolution of formulations. The industry is actively reformulating to lower harmful fluoride emissions while maintaining thermal and lubrication performance. Substitutes including borate, titania, and lithium‑based systems are moving from R&D to commercial adoption. For steelmakers producing ultra‑low‑carbon grades, carbon‑free powders are now a procurement consideration rather than an academic exercise.
- Raw material and processing upside/downside. Conventional flux recipes rely on a family of minerals—quartz, wollastonite, fluorite (CaF2), lime, silica, and alumina—plus various glass‑forming and carbon additives. Volatility in these inputs and the need for spray‑drying or pre‑fusion capacity affects both unit cost and product uniformity. Fly‑ash blends remain relevant in some regions, but their role is being rebalanced against tighter emissions norms.
- Competitive and capacity shifts. The market exhibits moderate concentration: the top three and top five suppliers control meaningful shares of global demand, but a diverse set of regional and specialist manufacturers remains active. Strategic investments—greenfield plants, hub expansions, and targeted acquisitions—are reshaping the supplier map and local service footprints.
Competitive landscape — capabilities you must map
In assessing supplier strategies for 2026, we recommend executives benchmark across three dimensions: product‑technology roadmap, technical services and on‑line support, and manufacturing footprint flexibility. Key players exemplify different strategic postures:
Mold Flux For Continuous Casting Market
- Integrated steel‑affiliated suppliers. Longstanding, high‑quality suppliers that combine metallurgical labs with captive supply to major mills continue to dominate premium segments. Their advantage is deep process knowledge and tight integration with steelmakers’ grade transitions.
- Global engineered‑materials vendors. Multi‑national refractories and metallurgical firms bring product breadth, R&D scale, and go‑to‑market networks. Recent plant openings and hub investments illustrate their play to capture regional production growth while offering standardized, quality‑assured powders.
- Specialist and craft manufacturers. Small‑batch and premium powder producers focus on niche alloys and rapid formulation cycles. Their agility makes them attractive for trial programs and differentiated product lines, and they are increasingly targets for strategic minority investments by larger refractories groups.
Notable developments that shape supplier strategy include a 2026 majority stake acquisition by a leading refractories company in a U.S. craft powder producer—an example of how incumbents are buying product innovation and local presence rather than building from scratch. Similarly, major investments in South Asia and plant inaugurations in 2024–2025 underscore an active localization trend that alters logistics cost and response time for regional steelmakers.
Report contents — what PW Consulting delivers (practical, actionable)
The full study is designed as a hands‑on playbook for procurement leads, plant metallurgists, M&A teams, and strategy officers. Key deliverables include:
- Market sizing and top‑line forecasting (2020–2032) with scenario sensitivity to raw‑material and regulatory shocks;
- Supplier scorecards with capability maps (R&D strength, spray‑drying and pre‑fusion capacity, service models, regional footprints) and a shortlist of strategic acquisition targets;
- Application and product matrix covering granular, powder, and pre‑fused technologies tied to continuous‑casting use cases (slabs, billets, blooms) and recommended qualification protocols;
- Procurement templates for multi‑year contracts, sample‑testing regimens, and change‑control checklists to manage reformulations with minimal process disruption;
- Supply‑chain risk maps addressing raw‑material concentration, logistics bottlenecks, and contingency sourcing; and
- Regulatory and environmental impact assessments with transition timelines for low‑fluorine and carbon‑free options and the implied capital and OPEX implications.
To preserve competitive advantage for report subscribers, we deliberately withheld full split tables and granular region/type/application monetary allocations from this press summary. The complete intelligence package provides those segment details alongside downloadable Excel models and supplier contract templates.
Strategic recommendations for 2026 (executive playbook)
- Prioritize reformulation pilot projects now. Allocate a portion of R&D and metallurgical trial budget to validate low‑fluorine and carbon‑free powders in your specific caster environment. Early pilots shorten vendor qualification times when broader regulatory pressure arrives.
- Shift procurement from spot‑to‑portfolio sourcing. Move to a blended supplier portfolio that balances large global suppliers for volume and regional, specialist producers for performance trials. Structure contracts with performance clauses tied to surface quality and inclusion control metrics.
- Design M&A and partnership filters around capability gaps. Look for targets that add rapid formulation capability, spray‑drying capacity, or technical service presence near major casting hubs—these assets accelerate market penetration without long build cycles.
- Quantify total cost of ownership (TCO) not just price per ton. Include reheat uniformity, mold life, and downstream quality losses in procurement KPIs. Some premium powders will deliver net savings through reduced scrap and improved casting speed.
- Invest in supplier co‑innovation programs. Establish joint labs or in‑mill pilot stations with preferred suppliers to accelerate diffusion of next‑generation fluxes while sharing development risk.
How to use the report in Q1–Q2 2026
For boards and executive teams, the report is a decision support tool to: (a) validate capex plans for flux handling and pre‑fusion equipment; (b) prioritize geographies for supplier development or acquisition; and (c) set procurement KPIs aligned with evolving environmental standards. For procurement and operations leaders, the study provides ready‑to‑use tender language, sample test protocols, and shortlists of suppliers by capability tier. For corporate development functions, the M&A filters and valuation sensitives in the appendices accelerate target screening and post‑deal integration planning.
Final note — the value of full intelligence
The Mold Flux for Continuous Casting market is maturing: steady top‑line growth at an approximate 3.85% CAGR masks substantive pockets of disruption from chemistry, raw‑material dynamics, and supplier consolidation. PW Consulting’s full report compiles the granular segmentations, supplier market shares, and downloadable models that boards and operational teams need to convert insight into action for 2026 and beyond.
Access to the complete study will supply the omitted segment tables, the supplier scorecards and contact maps, and the downloadable scenario models—elements we recommend stakeholders review before finalizing procurement strategies or M&A bid documents this year.
For detailed analysis of this topic, please visit the official page: Mold Flux For Continuous Casting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com