

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Blue Film Market to Expand Robustly at a 7.82% CAGR Through 2032

Blue Film Market 2026 Strategic Outlook: Actionable Intelligence for Executive Decision‑Making
PW Consulting’s Blue Film Market research offers a focused strategic toolkit for executives preparing decisions in 2026. Our analysis shows that the global blue film market reached a near‑billion USD scale in 2025 and is projected to expand at a compound annual growth rate (CAGR) of approximately 7.82% through the 2026–2032 forecast window, delivering a materially larger addressable market by 2032. That trajectory captures the combined effects of ongoing semiconductor packaging growth, rising demand for protective and processing films in electronics assembly, and supply‑side shifts in polymer feedstocks.
Blue Film Market
Why this report matters for 2026 decisions
-
Procurement and cost control: The report translates polymer feedstock dynamics into actionable cost scenarios and contracting strategies so procurement leaders can decide between short‑term spot exposure and multi‑year indexation agreements.
Blue Film Market -
Capital allocation and capacity timing: For companies considering capex to expand rolling, coating or converting capacity, our timing guidance ties capacity investments to realistic demand run‑rates and raw‑material availability windows.
Blue Film Market -
Portfolio and product strategy: R&D and product managers get a clear view of where to prioritize low‑residue adhesives, non‑UV film chemistries, and anti‑static properties to capture premium segments.
-
M&A and partnership playbooks: Investment teams receive an evidence‑based framework to screen targets and quantify integration synergies in a moderately concentrated supplier landscape.
What the report delivers — practical, transaction‑ready content
-
Market sizing & forecast model (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario toggles for demand shocks, polymer price shocks and adoption curves.
-
Segment economics and margin waterfall templates that map raw material inputs to finished film cost, enabling rapid 'what‑if' sensitivity runs.
-
Supplier benchmarking and scorecards that assess technology, adhesive performance, residue profile, anti‑static characteristics and geographic resilience—presented as operational metrics rather than marketing claims.
-
Go‑to‑market playbooks for coating converters, adhesive formulators and semiconductor OEMs, including channel strategies, pricing tactics and product bundling examples.
-
M&A diligence pack: valuation comparables, synergy decks, and integration checkpoints tailored to blue film assets and allied polymer lines.
-
Regulatory and compliance appendix—covering key requirements such as RoHS2 conformity for electronic‑grade protective films and practical steps to demonstrate compliance in supply chains.
Segment dynamics — high‑level synthesis (what to watch)
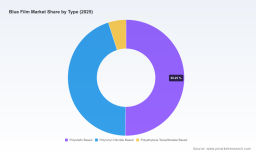
The blue film landscape is defined by distinct polymer chemistries and application use cases, each with unique upstream supply dynamics and technical performance requirements. Polyolefin‑based technologies, PVC‑based systems and polyester‑based solutions coexist in the market, with choices driven by adhesion profiles, peel residues, tensile properties and UV‑exposure behavior. For 2026, the most material upstream factor is polyethylene (PE) feedstock availability and cost.
Key raw material context for 2026 planning:
-
PE remains a principal feedstock for many polyolefin blue films; global PE production expanded materially in recent years and average pricing levels establish the baseline for film economics.
-
North American capacity additions scheduled to come online in late 2026 will alter regional supply balances and create pockets of favorable buyer conditions; procurement teams should model the timing and pass‑through dynamics into contract negotiations.
-
Because polyethylene and allied polymers are petrochemical derivatives, fluctuations in petroleum product prices will continue to transmit into film production costs; our sensitivity matrix quantifies breakpoints at which margin compression forces price renegotiation or drives substitution between chemistries.
Regional and end‑market trends (strategic takeaways)
Demand growth is concentrated in regions with heavy semiconductor manufacturing and assembly activity and in sectors where discrete device handling and packaging quality requirements are intensifying. Application drivers such as wafer dicing, back grinding and protective handling during assembly sustain steady replacement and innovation cycles for blue films. Compliance requirements—particularly RoHS2 for electronic equipment—remain a baseline expectation for suppliers targeting semiconductor and electronics OEMs, adding an operational compliance burden that smaller converters sometimes struggle to meet.
Competitive landscape — who matters and why
The market shows moderate‑to‑high supplier concentration, with the top three firms commanding a clear majority share and the top five approaching headline consolidation levels. That structure creates both stability and strategic risk: stable standards and scale economics on one hand, and supply bottlenecks or supplier power on the other.
-
Mitsui Chemicals Tohcello (Tokyo) — A technology‑led supplier with a strong portfolio of high‑performance protective films and specialty tapes for semiconductor processing. Mitsui’s ICROS™ tape family and non‑UV blue films combine advanced adhesion control with low residue profiles, making them a go‑to for higher‑value wafer dicing and surface protection needs.
-
Nitto Denko (Osaka) — Well recognized in wafer processing circles for robust dicing tapes and a broad product family tailored to backgrinding and cutting stability. Their emphasis on consistent adhesion performance and clean peelability supports long OEM qualification cycles.
-
LINTEC Corporation (Tokyo) — Focuses on precision adhesion solutions and anti‑static properties in its non‑UV backgrinding tapes. LINTEC’s product engineering is oriented to high‑precision process control and integration with automated wafer handling lines.
-
Denka Company Limited (Tokyo) — Offers adhesive films with high tensile strength and low‑residue removal characteristics. Denka’s chemical expertise underpins differentiated formulations that target both handling robustness and downstream cleanliness.
-
Furukawa Electric (Tokyo) — Brings polymer material know‑how that complements blue film applications in semiconductor packaging and protection processes. Their competencies in polymer engineering help bridge material science and application performance.
-
Sumitomo Bakelite (Tokyo) — Combines materials science and conversion capabilities to deliver dicing tapes and protective solutions; strengths include integration with broader electronics materials portfolios and customer service in qualifying new grades.
Strategic implications of concentration:
-
CR3 indicates a material degree of market control by the leading players; CR5 approaches three‑quarter market reach—this favors incumbent scale players in pricing and R&D, but leaves room for targeted entrants with differentiated chemistry or cost advantages.
-
For buyers, dual‑sourcing and qualification of alternative suppliers is a pragmatic hedge; for suppliers, vertical integration into upstream polymer supplies or into higher value adhesive technology can be a value creation lever.
Recommended 2026 playbook — five priorities for executives
-
Lock visibility on near‑term polyethylene flows: Model the impact of the 2026 North American PE capacity additions on delivered cost into 2026–2027; use that insight to time purchase commitments and spot exposure.
-
Prioritize low‑residue, non‑UV formulations: Customers will pay a premium for reduced contamination risk in advanced packaging lines; focus R&D and commercialization resources here.
-
Strengthen supplier scorecards and qualification pipelines: Implement cross‑functional qualification teams that reduce time‑to‑approve alternate suppliers and lower single‑source risk.
-
Stress‑test margin models against oil and polymer shocks: Adopt the report’s sensitivity templates to define trigger points for pass‑through clauses, price renegotiation and product substitution.
-
Evaluate strategic M&A selectively: Targets that provide access to adhesive IP, converting scale, or upstream polymer integration are highest value given current concentration dynamics.
Methodology and data integrity
The report’s base year is 2025, with a historical window covering 2020–2025 and a forecast horizon of 2026–2032. Projections use a hybrid approach combining bottom‑up shipment and conversion data from major end‑users with top‑down market adoption curves, cross‑checked against polymer production statistics and seller reported volumes. We apply probabilistic scenario analysis to derive a central CAGR of 7.82% and to delineate upside and downside outcomes under alternative raw‑material and demand shocks.
How to access the full intelligence
This release intentionally highlights strategic conclusions while withholding granular regional, type and application splits to preserve the full report’s commercial value. The comprehensive dataset in the full report includes detailed regional and application breakdowns, segmented unit economics, downloadable forecast models, and company scorecards with technology matrices—resources designed to support procurement RFPs, capital allocation memos, and M&A diligence.
To capture immediate value from the findings, PW Consulting recommends that executives download the full Blue Film Market report and accompanying Excel model. The dataset enables rapid scenario runs that align purchasing, manufacturing and commercial strategies to the 2026 operational calendar and beyond.
In short: 2026 is a year to align procurement timing with polymer supply cycles, to prioritize product differentiation in low‑residue and non‑UV film chemistries, and to use supplier concentration dynamics as a lens for both risk mitigation and strategic consolidation. Our report provides the operational playbooks and quantitative models needed to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Blue Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com