

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Coal Tar Pitch Market to Expand at a 4.85% CAGR Through 2032, New Insight Report Reveals

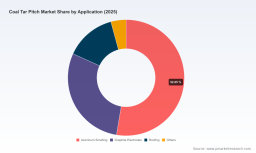
Coal Tar Pitch Market — Strategic Outlook 2026: An Operational Playbook for Capture and Resilience
Executive summary
PW Consulting’s latest Coal Tar Pitch Market report (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) arrives at a pivotal moment for producers, consumers and investors across aluminum, graphite and specialty carbon supply chains. By 2025 the market reached approximately USD 2,185.5 Million and, under our central scenario, expands at a 4.85% compound annual growth rate to roughly USD 3,044.1 Million by 2032. These headline metrics mask structural change: rising regulatory and compliance costs, shifting feedstock availability tied to broader steelmaking transitions, and a consolidation profile that leaves the top three and top five firms commanding a materially large share of supply (CR3 ~58.4%; CR5 ~72.3%).
Coal Tar Pitch Market
This release outlines why the report is a must-read for any executive making capital, sourcing or product-development commitments in 2026 — and describes the practical, executable analysis inside that underpins those recommendations. To preserve competitive integrity we present depth of insight without publishing the granular segment tables and proprietary scenario outputs; full access requires the complete report.
Coal Tar Pitch Market
Why this report matters for 2026 decision-making
- Timing of investments: With mid-decade demand increasing and supply-side friction from feedstock volatility, 2026 is the inflection year where the ROI math for capacity additions, debottlenecking projects and low-PAH conversion technologies becomes unambiguous.
- Contracting and procurement: Buyers face tightening supplier leverage and should redesign contracting strategies now — moving from annual spot procurement to blended, multi-year structures with graduated price and quality triggers.
- Regulatory compliance: Intensifying PAH controls in key jurisdictions mean legacy grades will attract higher treatment and monitoring costs; early movers on low-PAH product lines gain cost and market access advantage.
- M&A and partnerships: Market concentration and capacity expansions announced in 2025 have created attractive bolt-on and greenfield opportunities for both strategic and financial buyers seeking scale and feedstock security.
What the report delivers — operational, commercial and financial tools
The report is designed as an operational playbook for executives and contains layered, actionable analysis rather than high-level conjecture. Components include:
Coal Tar Pitch Market
- Proprietary market sizing and a transparent forecasting model (2026–2032) that produces scenario outputs for demand by end-use, by product grade and by region, with sensitivity levers for feedstock availability, steelmaking mix and regulatory stringency.
- Unit-level economics: normative pricing and cost stacks (feedstock, processing, environmental compliance) expressed in consistent currency and unit terms so CFOs can run rapid NPV and break-even analyses for candidate projects.
- Supply-chain heatmaps and logistics overlays identifying choke points, alternate routing (including new export corridors), and terminal/storage capacity implications for both liquid and solid pitch products.
- Regulatory impact matrix: jurisdictional review of PAH, wastewater and air emission standards, with compliance cost benchmarking and a technology roadmap for low-PAH process conversions and end-of-pipe controls.
- Competitor benchmarking and vendor scorecards: production footprints, grade portfolios, capacity trends, recent strategic moves and exposure to regulatory and feedstock risk — prepared to support sourcing and M&A diligence.
- Customer procurement playbook and negotiating templates: tiered tender designs, quality/specification clauses, and contingency language to mitigate supply disruption and price volatility.
- Scenario-driven strategic options for market entrants and incumbents: capacity timing matrices, partnership archetypes (tolling, JV, offtake), and an M&A shortlist with value-accretion hypotheses.
Competitive landscape — who matters and why
The coal tar pitch market retains strong incumbent positions, but 2025–2026 developments are reshaping competitive dynamics. The CR3 and CR5 concentration metrics point to a market with substantial scale advantages for a handful of global players, while capable regional suppliers create localized competition and agile responses to niche demand.
- Koppers Holdings Inc. (Pittsburgh, USA) — integrated producer focused on carbon pitch from coal tar distillation; core strength is serving aluminum anode and graphite electrode markets with established global customer relationships and technical know-how.
- Rain Carbon Inc. (Stamford, USA) — global distillation and pitch manufacturer; continues to invest in capacity targeting high-growth corridors and downstream battery/graphite applications.
- Himadri Speciality Chemical Ltd. (Kolkata, India) — vertically integrated with substantial pitch capacity and a growing export orientation; notable for aggressive capacity and market access plays.
- Deza, a.s. (Czech Republic) — European-focused producer with capability in binder and impregnating grades and a position in specialty carbon value chains.
- Shree Shyam Chemicals (Bhilai, India) — diversified chemical supplier with industrial-grade pitch offerings serving regional aluminum and graphite markets.
Recent public moves exemplify shifting competitive calculus: in 2025 Rain Carbon announced an initial phase of a new distillation and processing facility in Andhra Pradesh aimed at graphite/battery/aluminum markets; a November 2025 memorandum between a carbon supplier and a major aluminum producer highlights the strategic value of long-term liquid-pitch offtakes; and exports from new Indian terminals signal growing south-to-Middle East trade lanes. These developments illustrate three dynamics: capital redeployment into growth markets, buyer-driven vertical security, and the opening of new logistics corridors.
Regulatory and raw-material dynamics — the operating constraints for 2026
Regulation and feedstock availability are the two levers most likely to surprise the market in 2026. Key elements we analyze in the report include:
- PAH-focused regulations: Jurisdictions including parts of North America and Europe are tightening PAH limits and imposing higher compliance monitoring. The EU REACH framework and various state-level statutes are increasing the effective cost of legacy grades and prompting accelerated low-PAH grade development.
- Local bans and proposals: Long-standing prohibitions on certain coal tar sealant applications and new proposals in other states create localized demand suppression risk for specific downstream uses (notably pavement and sealants).
- Feedstock volatility: As global steelmaking shifts toward electric arc furnaces in some regions, the availability and economics of coal tar as a distillation feedstock are materially affected. Producers need to model feedstock scarcity and variable yields into project valuations.
- Environmental capex: Capital required to meet tightening wastewater and emissions thresholds is rising; the report provides benchmarking data to estimate incremental capex and unit opex penalties for non-upgraded facilities.
Strategic recommendations for 2026
Executives should treat 2026 as a decisive year: those who act on three fronts (supply security, product differentiation, and regulatory preparedness) will create durable advantage. Our prioritized recommendations are:
- Secure diversified feedstock and offtake footprints: Lock in multi-source feedstock arrangements and construct blended offtakes with geographically segmented clauses to smooth logistics risk and capture premium end-users.
- Accelerate low-PAH conversion and certification: Convert at least one product line to low-PAH grades and secure voluntary third-party certification to preempt market access restrictions in priority export markets.
- Time capacity expansion conservatively but proactively: Use milestone-linked investment (phased debottlenecking) rather than single-stage greenfields in markets where feedstock or regulatory risk profiles remain uncertain.
- Adopt more sophisticated contracting: Move to multi-year, indexed contracts with volume-flex and quality-adjustment triggers; include force majeure and substitution provisions tailored to feedstock shocks and regulatory closures.
- Position for M&A selectively: Consider bolt-on purchases that secure port/terminal capacity, low-cost feedstock access, or specialty grade know-how rather than large-scale horizontal mergers that increase regulatory scrutiny.
- Invest in emissions and wastewater solutions: Prioritize technologies with short payback for compliance (and potential co-benefits for product quality), and seek governmental incentives for early adopters.
How to use the report in 2026 tactical planning
For corporate strategy, our report provides the modeling inputs and scenario outputs required to run internal capital allocation rounds, to stress-test procurement strategies and to inform executive-level board decisions. For procurement and operations teams it supplies supplier scorecards, logistics vulnerability maps and contract templates. For corporate development and investors, the report furnishes an M&A framework with valuation sensitivities tied to feedstock and regulatory outcomes.
We designed the deliverable to be a working document: clients receive the full model and a one-hour walk-through with our lead analyst to adapt scenarios to their balance sheet, asset base and risk tolerance. The report intentionally balances transparency in methodology with protection of proprietary segmentation tables — a trade-off that ensures readers gain the analytical tools without prematurely commoditizing sensitive market slices.
Next steps
- Operational leaders: begin supplier re-evaluation and stress-test inventory policy against the report’s mid-case and downside scenarios.
- Technical teams: request the regulatory impact annex and the low-PAH technology roadmap to set a 2026 R&D/Capex timeline.
- Corporate development: use the M&A shortlist and valuation sensitivities to prioritize target diligence in Q1–Q2 2026.
PW Consulting’s Coal Tar Pitch Market report is built for executives who need market-calibrated, operationally relevant insight to make consequential 2026 choices. The report’s models, templates and scores are designed to move decisions from speculative to executable. For access to the full dataset, scorecards and downloadable forecasting model, please refer to the official PW Consulting release channels.
For detailed analysis of this topic, please visit the official page: Coal Tar Pitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com