

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Amorphous Metal Sheets Market Poised for Robust 9.4% CAGR Through 2032, Led by Asia-Pacific Demand

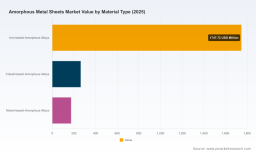
PW Consulting Strategic Brief: Amorphous Metal Sheets Market — 2026 Outlook and Decision Playbook
Executive preview — why our 2026 report is essential for corporate strategy, procurement, and investment
PW Consulting’s Amorphous Metal Sheets Market report (base year 2025; forecast 2026–2032) delivers a pragmatic, decision-focused view of a market that is rapidly moving from niche to mainstream within power electronics, electric traction, and high-efficiency distribution infrastructure. The market has expanded substantially over the 2020–2025 period, with the 2025 baseline positioned at USD 2,185.4 Million (USD, Million units). Our forecast framework projects a compound annual growth rate (CAGR) of 9.4% across 2026–2032, reflecting sustained demand from electrification, grid modernization, and high-performance industrial applications. For executives planning capital allocation, supplier selection, and product roadmaps in 2026, the report is structured to convert this top-line momentum into practical, risk-aware actions.
Amorphous Metal Sheets Market
Why 2026 is a strategic inflection
-
Demand convergence: Multiple end-markets—distribution transformers, electric motors (notably xEV traction motors), power electronics, and precision industrial components—are converging on amorphous metal sheets for loss-reduction and weight/efficiency advantages. This convergence amplifies total addressable demand while elevating technology requirements for core materials and laminates.
Amorphous Metal Sheets Market -
Supply-side consolidation and concentration: The market exhibits measurable concentration among leading producers (CR3 and CR5 metrics indicate the top players collectively control a majority of supply), creating both supply security for large buyers and strategic leverage for those suppliers.
Amorphous Metal Sheets Market -
Technology inflection: Innovations in bonded-lamination, high-density packaging for motor cores, and bulk amorphous (metallic glass) processing for precision components are shifting where value is captured in the chain—from raw ribbon manufacturing to engineered components and subassemblies.
-
Policy and trade tailwinds/risk: Energy-efficiency and CO2-reduction objectives create supportive regulation and procurement standards for low-loss cores, while tariff policy changes (including strengthened Section 232 measures in 2026) introduce near-term import cost volatility that needs scenario planning within 2026 budgets.
What the report contains — practical elements for 2026 decision-making
-
Validated market sizing and trend fractals: year-by-year demand history (2020–2025) and an actionable forecast model for 2026–2032 that maps capacity, utilization, and price elasticity to decision levers.
-
Supply-side scorecards: independent supplier assessments combining technology maturity, capacity posture, vertical integration, and execution risk—arranged to support strategic sourcing and qualifying dual-source strategies.
-
Segment playbooks: application-level value capture templates for transformers, motors, consumer electronics, aerospace/defense, and renewable power systems that translate material performance into lifecycle TCO and regulatory compliance metrics.
-
Operational playbooks: CAPEX sizing templates, lead-time reduction tactics, and pilot-to-scale roadmaps for bonded-lamination, stamping, and additive manufacturing of amorphous-derived components.
-
Scenario and sensitivity analyses: tariff shock scenarios, raw-material feedstock volatility, and adoption-rate breakpoints—designed to feed 2026 board-level stress tests and procurement hedges.
-
M&A and partnership compass: identification of strategic targets, partnership archetypes (capacity JV, IP licensing, co-development), and valuation multipliers tuned to current market concentration and technology differentiation.
Competitive landscape — who matters and why
The market is shaped by a mix of legacy specialists, vertically integrated international groups, and high-precision materials innovators. Key players combine scale in ribbon production, proprietary alloy IP, and growing capabilities in component-level engineering. Highlights:
-
Metglas Inc. — A long-standing leader in rapid-solidification ribbon technologies. Strengths include deep metallurgical know-how and a strong presence in transformer and motor core markets. Buyers evaluate Metglas for supply security and tried-and-tested alloy performance.
-
Proterial, Ltd. (formerly Hitachi Metals) — Focused on high-efficiency laminated/bonded ribbons and engineered motor cores. Recent product introductions aimed at xEV drive motors underline Proterial’s strategy to climb the value chain with pre-engineered core systems.
-
VACUUMSCHMELZE (VAC) — European specialist with high-permeability materials and stamped-part capability for sensitive electronics and power modules; competitive where magnetic performance and precision are paramount.
-
Large Chinese producers (Qingdao Yunlu, AT&M, Shenzhen SAT, others) — Bringing scale, aggressive capacity expansion, and cost leadership to commodity and near-commodity grade amorphous ribbons. Recent capacity additions materially shift global supply balances and shorten lead times for high-volume buyers.
-
Heraeus Amloy, Amorphology, Liquidmetal, Orbray — Innovators in bulk metallic glass (BMG), precision components, and additive processing. These players are capturing margins in high-value niches—precision gears, medical devices, and specialized aerospace components—where amorphous properties provide unique advantages.
Recent developments and implications
-
Capacity expansion at major Chinese facilities has created new high-volume supply corridors; this changes the scoreboard for lead times and spot pricing and opens options for large OEMs to localize supply in Asia or source competitively on global tenders.
-
New laminated bonded ribbons and motor-core systems from established Japanese and European suppliers signal a move to productized, higher-margin offerings—an important consideration for partners that prefer design-in over raw-bundle purchases.
-
M&A and asset acquisitions in adjacent amorphous processing technologies broaden the set of capabilities available for precision and high-diameter glass/amorphous processing, supporting faster innovation cycles for component-level applications.
Market dynamics to incorporate in 2026 plans
-
Raw material and process physics: iron-based amorphous alloys remain the backbone of the market; production is driven by rapid solidification processes that require specific metallurgical throughput and skilled process control. This creates a high entry barrier for new low-cost entrants in high-performance grades.
-
Policy and procurement alignment: governments and large utilities are increasingly favoring low-loss cores in procurement specifications to meet energy-efficiency and CO2 targets. This increases provider bargaining power for suppliers who can demonstrate verified lifecycle gains.
-
Tariff and trade risk: recent trade policy changes around base metals and derivative products mean buyers should include duty-shock scenarios in 2026 sourcing models and consider near-shore or domestic capacity options where total landed cost parity is achievable.
Actionable recommendations for executives in 2026
-
Operationalize dual-sourcing and buffer inventories for critical grades: use our supplier scorecards to qualify at least two capable suppliers with complementary geographies and production technologies.
-
Pursue selective co-development with laminated-bond and stamped-part specialists to capture downstream value and shorten time-to-market for motor-core assemblies in xEV programs.
-
Include tariff-triggered scenarios in 2026 CAPEX planning: where duty exposure is material, evaluate localized production lines or contractual duty pass-through clauses to preserve margin.
-
Prioritize investments in advanced processing (bulk amorphous forming, additive manufacturing) for high-value, low-volume components where the technology creates defensible margins and differentiation.
-
Use a phased M&A playbook: small strategic acquisitions can secure capacity or unique IP without overpaying; our concentration analysis identifies where bolt-on scale will materially shift negotiating power.
How PW Consulting’s report supports boardroom and commercial decisions
The report is designed as both a diagnostic and an operational toolkit. For CFOs and heads of strategy, it provides CAPEX and scenario models tied to quantified price and supply sensitivities. For procurement and supply-chain leaders, it delivers supplier scorecards, qualification matrices, and commercial negotiation levers. For product and engineering teams, the segment playbooks connect material performance to lifecycle cost and regulatory compliance. In short: the report converts macro growth trajectories (9.4% CAGR through 2032) into executable 12–24 month plans that mitigate risk while positioning companies to capture disproportionate upside as adoption accelerates.
Next step
This brief showcases the strategic contours and operational implications we see for amorphous metal sheets in 2026. For the full dataset, granular segmentation analyses, supplier scorecards, and the actionable playbooks referenced above, please consult the full PW Consulting Amorphous Metal Sheets Market report on our website. The detailed appendices include the methodology, scenario spreadsheets, and bespoke advisory offerings to convert findings into implementation roadmaps tailored to your organisation.
For detailed analysis of this topic, please visit the official page: Amorphous Metal Sheets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com