

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
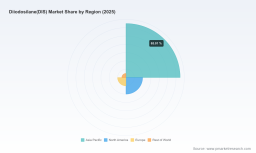
PW Consulting: Diiodosilanedis Market to Climb from USD 115.0 Million in 2025 to USD 207.3 Million by 2032 at an 8.78% CAGR — Asia‑Pacific Grabs ~75% Share as Top‑3 Firms Control 76.4%

PW Consulting Strategic Brief: Diiodosilanedis Market — Preparing Enterprise Decisions for 2026
As semiconductor nodes compress thermal budgets and advanced memory architectures proliferate, the economics and technical dynamics of specialty silicon precursors are moving from niche engineering discussions to board‑level procurement and capital planning. PW Consulting’s new Diiodosilanedis Market report (base year 2025; forecast 2026–2032) synthesizes primary supplier intelligence, materials‑science validation, and demand modelling to give executives the operational playbook they need for 2026. The global Diiodosilanedis market was estimated at USD 115.0 Million in 2025 and, under our base case, will grow at a compound annual growth rate (CAGR) of 8.78% through the 2026–2032 forecast window, with modeled size approaching the low‑hundreds of millions by 2032.
Diiodosilanedis Market
Why this analysis matters for 2026 decision-makers
-
Time to qualify matters: qualification cycles for new precursors and process recipes are measured in quarters, not weeks. Suppliers with validated, high‑purity product and demonstrated scale materially shorten ramp time for fabs and specialty materials buyers.
Diiodosilanedis Market -
Concentration drives strategy: the sector shows meaningful supply concentration, with the top three and top five suppliers accounting for the vast majority of commercial capacity. That concentration creates both opportunity (strategic partnerships, co‑development) and risk (single‑source dependency, pricing power) that must be baked into 2026 procurement and CapEx plans.
Diiodosilanedis Market -
Technical substitution and thermal budgets: Diiodosilanedis is a compelling silicon source for low‑temperature silicon nitride deposition by PE‑ALD and related processes, meaning fab roadmap choices on ALD/CVD architectures will directly shape precursor demand.
What the PW Consulting report contains (practical, operational sections)
-
Comprehensive market sizing and bottom‑up demand modelling (2020–2025 historic, 2026–2032 forecast), including sensitivity tests and alternative demand shocks tied to memory and logic capital cycles.
-
Supply chain mapping and capacity assessment: verified site inventories, estimated effective capacity, lead‑time matrices and turnaround profiles for commercial, research and toll‑manufacturing routes.
-
Technical evaluation and qualification playbook: impurity risk profiles, analytical methods for silicon precursor RPMs, recommended in‑house assays, and a lab‑based validation checklist to accelerate vendor qualification.
-
Commercial benchmarks and contracting templates: practical guidance on PBH (price, batch, hold) negotiation levers, sample vs. bulk conversion, and warranty/recall clauses tailored to hazardous precursors.
-
Regulatory and FTZ analysis: a pragmatic review of safety data sheet language, export/FTZ notifications and their procurement implications — especially in cross‑border sourcing scenarios.
-
Scenario playbooks for procurement, R&D and M&A: tactical options for supplier diversification, co‑development partnerships, tolling agreements, or vertical integration aimed at 12–36 month time horizons.
Competitive landscape — what senior buyers need to know
-
Gelest, Inc. (Morrisville, PA, USA): A differentiated player with a commercial, dedicated production plant and high‑purity product grades (commercial grades and ultra‑high purity >99.9%). Gelest’s early scale‑up for semiconductor‑grade diiodosilane and its targeted positioning for silicon nitride thin films at low thermal budget processes give it a defensive advantage in the semiconductor value chain. Previously announced commercial capacity and plant readiness have translated into prioritized access for customers needing validated, high‑purity supply.
-
Sigma‑Aldrich / MilliporeSigma (Merck KGaA): A strategic channel that spans research and small‑bulk supply. Their product positioning — often with stabilizers for handling — means they are commonly used for early R&D and pilot qualification. Buyers should treat their offering as a convenient baseline for lab validation rather than a guaranteed long‑term production route without further contractual controls.
-
Chinese producers and specialty manufacturers (representative players include Argosun/Argotech, Shanghai Wechem, Daken Chemical, GWI, TNJ Chemical, Warshel/Watson): These suppliers collectively add depth in price‑sensitive and regional supply chains. Several emphasize certifications (GMP/SGS), lead‑time responsiveness and competitive pricing for research‑grade and industrial batches. Differences in origin, documentation practices, and export controls require careful technical and compliance due diligence before conversion to production use.
-
Market structure note: Our supplier interviews and plant audits indicate that a small number of firms control a large fraction of effective commercial supply capacity. This concentration means that strategic supplier allocation and long‑lead contracts are high‑value levers for 2026 procurement teams.
Regulatory and technical realities — what changes in 2026
-
Labelling and usage constraints: Safety data sheets from multiple suppliers continue to emphasize “research use only” or “not for household or medicinal use” language for diiodosilanes. Practitioners must reconcile supplier‑level SDS language with internal qualification requirements and regulatory compliance regimes in production environments.
-
Trade‑policy watch: Diiodosilanedis has appeared in production activity notifications and foreign‑trade zone filings tied to semiconductor materials. These administrative flags often precede stricter handling or documentation expectations; procurement teams should anticipate additional paperwork and potential lead‑time impacts for cross‑border shipments.
-
Process suitability: Scientific literature and lab validations show diiodosilanes can generate active silicon radicals at lower temperatures in PE‑ALD routes, enabling SiNx films with controllable properties. Teams choosing low‑thermal budget process architectures should prioritize precursor impurity profiling and contamination risk assessments.
Strategic recommendations for 2026 (practical actions)
-
Accelerate supplier qualification now: Begin parallel technical validations with at least two vetted suppliers (one high‑purity incumbent and one cost‑advantaged producer) to reduce single‑source exposure. Use staged qualification milestones tied to lot release testing and end‑use wafer performance.
-
Negotiate capacity reservations and flexible offtake: Given market concentration, secure capacity options or call‑off contracts that include quality gates and termination triggers tied to performance tests. Consider hybrid pricing (base + call‑up) to balance cost and availability.
-
Invest in in‑house analytical capability: Equip a materials science lab to run trace halogen and metal impurity assays, surface contamination screens and accelerated aging tests — the ability to certify shipments internally shortens procurement cycles and reduces reliance on supplier certificates of analysis.
-
Embed regulatory monitoring into procurement SOPs: Assign a compliance owner to track FTZ notices, SDS updates and export control changes. Pre‑clear prospective suppliers for cross‑border compliance before issuing POs for production lots.
-
Prepare for substitution risk: Fund a small internal R&D sprint to de‑risk potential precursor substitutions or process recipes that reduce dependence on any single halogenated silane species.
-
Consider strategic partnerships or minority investments: For firms with critical demand growth, equity‑backed supply agreements or co‑located tolling partnerships with specialty manufacturers accelerate secure access and can be cost‑effective compared with sole reliance on spot markets.
Scenario planning — what the numbers imply
Under the base case (our midpoint forecast), the market’s CAGR of 8.78% implies steady demand growth tied to memory capacity rollouts and selective migration of ALD processing. An upside scenario — driven by accelerated adoption of low‑thermal ALD processes in logic/foundry and memory sectors — compresses qualification timelines and increases premium demand for high‑purity supply, rewarding firms with pre‑secured capacity. A downside scenario — triggered by tighter regulatory constraints or rapid substitution to alternative precursors — would reduce demand and shift the balance to cost and compliance efficiencies. Procurement and R&D leaders should stress‑test budgets and capital plans against these outcomes during their 2026 budgeting cycles.
Why PW Consulting’s Diiodosilanedis report is uniquely actionable
-
Source‑verified supplier audits and lab validation: our team conducted on‑site supplier assessments, laboratory cross‑checks and analytical corroboration of key impurity vectors.
-
Practical playbooks, not just charts: the report includes contract language templates, a vendor qualification checklist and a procurement timeline tailored to the realities of hazardous precursor supply.
-
Integrated risk scoring: suppliers and regional sourcing options are scored across technical, regulatory and delivery risk, providing a short list for rapid decision‑making.
-
Executive summary tuned to 2026 planning cycles: clear, prioritized recommendations aligned with CapEx, procurement and R&D timelines for immediate implementation.
We intentionally keep the granular segmentation tables and commercial unit flows — the detailed regional and application splits and supplier share tables — behind the full report paywall to preserve the commercial sensitivity and confidentiality that many of our respondents requested. That same granular intelligence, however, is available to subscribers and includes the full supplier share matrix, contract benchmarking, and downloadable qualification templates.
To discuss how these insights translate to your 2026 sourcing and capital plans, or to obtain the full Diiodosilanedis Market report and our bespoke supplier due diligence add‑on, contact PW Consulting’s Chemicals & Advanced Materials practice. Our team will walk you through the scenario outputs and construct a tailored implementation roadmap aligned with your risk tolerance and business objectives.
For detailed analysis of this topic, please visit the official page: Diiodosilanedis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com