

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
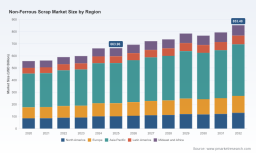
PW Consulting report: Non‑Ferrous Scrap Metal market poised to reach USD 853.48 Billion by 2032 at a 3.6% CAGR

Non‑Ferrous Scrap Metal Market — 2026 Strategic Brief (PW Consulting)
Executive summary
The global non‑ferrous scrap metal market continues to mature as a strategic raw material pool for a decarbonizing industrial economy. Our analysis shows the industry has grown from a market value of approximately USD 558 Billion in 2020 to a 2025 base‑year of USD 664 Billion, and the forecast path to 2032 points to continued expansion to roughly USD 853 Billion. PW Consulting’s model embeds a compound annual growth rate (CAGR) of 3.6% across the 2026–2032 forecast window, reflecting a combination of steady end‑market demand, commodity price volatility, and regulatory drivers that are reshaping trade flows and investment priorities.
Non Ferrous Scrap Metal Market
Why this report matters for 2026 decisions
- Policy inflection points that took effect in late 2025 and early 2026 (regional export limits and new licensing regimes) mean 2026 will be the first year companies must operationalize compliance‑first supply strategies at scale.
- Recent capacity investments and technology deployments (advanced recovery lines, AI‑enabled sorting) are changing unit economics and the competitive frontier—companies that move early can capture higher yields on complex feedstock.
- Macro price pressure on primary metals is expected to persist into 2027, increasing the strategic value of scrap as a buffer and margin lever for integrated producers and recyclers.
- Market concentration metrics indicate a structure with national and regional champions but meaningful fragmentation—this creates M&A arbitrage, partnership potential, and niche scale plays for 2026‑driven value creation.
What this report delivers (practical, decision‑grade content)
- Proprietary market sizing and forecast model (2020–2032) calibrated to recent commodity and trade shocks and the 2025 base year; scenarios include policy‑driven localization and high‑price stress testing.
- Buy‑side and sell‑side playbooks that translate market signals into executable 12–24 month actions: sourcing hedges, capital allocation templates, and contract structures tailored to non‑ferrous scrap flows.
- Technology and CAPEX assessment: ROI frameworks for AI sorting, shredding/upstream recovery, hydrometallurgical add‑ons, and logistics automation—benchmarked to industry peers.
- Regulatory and traceability tracker—step‑by‑step compliance pathways for emerging export controls and state‑level licensing, including audit checklists and sample contractual clauses.
- M&A and partnership screening suite: data‑driven target prioritization, integration risk map, and a short list of archetypal consolidation targets by capability (processing, collection, trading, recovery tech).
- Commercial tools—price sensitivity matrix, break‑even maps and a downloadable Excel model for stress‑testing procurement and production scenarios (full dataset available on the source page).
Competitive landscape — who matters and why
The non‑ferrous scrap market is characterized by a mix of globally scaled processors, regional aggregators and vertically integrated metals producers. Our CR3 and CR5 metrics (approx. 32.5% and 38.0% respectively) signal that while clear leaders exist, meaningful share remains accessible to fast‑moving challengers. Below we synthesize the strategic positioning and 2026 implications for the sector’s prominent players.
Non Ferrous Scrap Metal Market
- Sims Metal Management Inc. (Canada) — A leading global processor and trader with deep investments in high‑purity recovery and AI‑enabled sorting. Recent capacity expansion announcements and upgraded shredding lines reinforce a strategy of margin improvement through technology and e‑waste capture. For 2026, Sims’ moves highlight the competitive advantage of automation and cross‑border footprint optimization.
- OmniSource Corporation (United States) — Integrated North American operations give OmniSource scale in feedstock collection and first‑pass processing. Their model underscores the value of control over the logistics chain and diversified downstream relationships—an advantageous position as state licensing regimes increase operating complexity.
- European Metal Recycling Ltd (EMR) (United Kingdom) — Specialist trading and processing capabilities focused on copper and aluminum grades position EMR to capture value from intra‑regional retention policies and EIB‑backed capacity upgrades. EMR’s agility in high‑grade flows exemplifies a trade‑oriented strategy with selective processing.
- Aurubis AG (Germany) — As an integrated non‑ferrous producer, Aurubis blends recycling with primary processing. The commissioning of a new copper recycling facility in 2025 demonstrates a playbook of capturing complex scrap feedstock and moving it up the value chain—an instructive model for firms seeking to internalize refining margins.
- Shapiro Metals & American Iron & Metal LP (North America) — Regional leaders whose strengths are collection networks and service breadth. They typify consolidation targets for larger processors or attractive partners for feedstock assurance programs.
- Manaksia Aluminium Co Ltd (India) & Hayes Metals (New Zealand) — Examples of regionally focused specialists: Manaksia’s aluminum processing and Hayes’ Australasian market reach illustrate regional strategies that prioritize local feedstock capture and downstream integration.
Regulatory and financing context (select developments shaping 2026)
- European policymakers signaled a move to limit export of certain aluminum scrap from 2026 to retain material for domestic processing—this shifts trade arbitrage and raises the value of regional processing capacity.
- State and provincial licensing (example: California’s copper scrap licensing law effective Jan 2026) introduces compliance costs and erects barriers to informal trading—favoring established players with audit‑ready operations.
- Public capital is following strategy: European financing bodies approved significant funding rounds for recycling capacity and process optimization in late 2025, mobilizing project‑level investment pipelines for 2026.
- Commodity forecasts point to higher primary metal prices through 2027 due to upstream supply constraints—enhancing the competitiveness of scrap as an input and incentivizing increased recovery rates.
Strategic plays for 2026 — prioritized actions
- Lock in regional feedstocks now. Rework supply agreements and establish dual‑mode logistics to mitigate export restrictions and licensing friction. Prioritize long‑dated offtake where feasible.
- Invest selectively in digital sortation and recovery tech. AI sorting and improved shredding materially raise yields on complex e‑scrap—target ROI horizons of 24–48 months for incremental CAPEX to remain competitive.
- Pursue bolt‑on M&A to secure collection networks. Given the industry’s fragmentation, 2026 is a year for targeted tuck‑ins that close feedstock gaps and provide immediate volume to new processing lines.
- Implement compliance and traceability standards. Build audit‑ready provenance (lot‑level traceability, chain‑of‑custody documentation) to minimize regulatory risk and win premium contracts from smelters demanding compliant feedstock.
- Hedge commercial exposure. Use blended pricing mechanisms and index‑linked contracts to protect margins against metal price spikes while preserving upside participation.
- Develop partnership models with primary producers. Long‑term supply and processing collaborations with integrated refiners can unlock shared capex, reduce logistics friction and create downstream margin capture opportunities.
Scenario view and key risks
- Policy‑driven localization. If regional export restrictions deepen, expect tighter domestic supply, regional price dispersion and accelerated investment in local processing—companies should model the local pricing impact and capacity timelines.
- Commodity spike (short‑term). A material run in primary metal prices benefits recyclers but may compress availability of certain grades; prioritize grade‑conversion pathways and high‑yield sorting.
- Technology adoption race. Faster adopters of AI and advanced recovery will widen margin differentials; late adopters may face compression and reduced attractiveness to downstream buyers.
- Compliance fragmentation. Divergent state and national rules increase transaction costs; the ability to scale compliant operations across jurisdictions will be a competitive moat.
How PW Consulting’s insights accelerate 2026 outcomes
This report is purpose‑built for executives and investors who must convert 2025 policy and investment signals into actionable 2026 plans. It combines a granular, scenario‑based forecast model with practical playbooks—covering sourcing, technology, compliance and M&A—that teams can operationalize within 90 days. Our benchmarking and supplier‑screening tools translate strategy into specific targets and measurable KPIs, enabling faster capital deployment and lower execution risk.
Non Ferrous Scrap Metal Market
Next steps — where to find the full intelligence
The analysis above is a concise strategic briefing designed to surface the material implications for 2026 planning. The full PW Consulting Non‑Ferrous Scrap Metal Market report contains the detailed segmentation, plant‑level benchmarking, downloadable financial models and the comprehensive supplier scorecards that underpin the recommendations summarized here. Access to the complete dataset and the interactive Excel model is available on our source page—where subscribers can also request customized scenario runs and a private briefing with our lead analysts.
PW Consulting — helping industry leaders convert market complexity into decisive 2026 advantage.
For detailed analysis of this topic, please visit the official page: Non Ferrous Scrap Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com