

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pneumococcal Vaccination Market Poised for 5.3% CAGR, New Insight Report Reveals

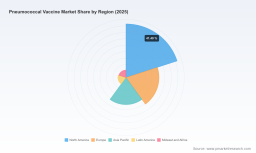
Pneumococcal Vaccination Market — 2026 Strategic Outlook: How PW Consulting’s New Report Informs Boardroom Decisions
Executive summary
PW Consulting’s latest Pneumococcal Vaccination Market report (base year 2025; historical 2020–2025; forecast 2026–2032) provides a practice-oriented roadmap for executives making high-stakes strategic decisions in 2026. The global market has expanded meaningfully over the past half-decade and continues to show steady momentum: overall industry revenues moved from the mid‑single‑billion USD range in 2020 to an estimated roughly USD 9.4 billion in 2025, and our scenario-driven baseline projects continued growth through 2032, reaching approximately USD 13.3 billion under a 5.3% CAGR during the forecast window. The market remains highly concentrated (CR3 ≈ 85%, CR5 ≈ 92%), so competitive moves by leading manufacturers and strategic partnerships will continue to determine access, price dynamics, and growth trajectories.
Pneumococcal Vaccination Market
Why this report matters for 2026 decision-makers
-
Timing: Market structure and product innovation cycles (new higher‑valency conjugate vaccines entering adult and pediatric programs) mean that decisions made in 2026—on manufacturing footprint, licensing, pricing, and payer engagement—will determine commercial outcomes for the next decade.
Pneumococcal Vaccination Market -
Supply and access: The combination of localized manufacturing agreements and global tender dynamics is reshaping access pathways. Executives must assess not just demand, but the practical constraints of supply‑side scale, cold chain, and contract structures.
Pneumococcal Vaccination Market -
Regulatory and reimbursement inflection points: Recent regulatory milestones and evolving payer rules (including updated Medicare Part B payment structures) change the calculus for adult immunization strategies and value‑based pricing pilots.
Market dynamics — what’s driving growth and where the pressure points are
Growth drivers are multi‑faceted: continued pediatric immunization efforts, expanding adult immunization guidelines in several markets, higher‑valency product launches, and targeted public‑sector procurement in low‑ and middle‑income countries. At the same time, pressures originate from tender competition, pricing differentials across public and private channels, and manufacturing scale‑up risks.
-
Product innovation: The race to higher‑valency conjugate vaccines and adult formulations is central. Pipeline activity and Phase 3 initiations are changing clinical and commercial roadmaps—and therefore demand curves for incumbent vaccines.
-
Supply chain & logistics: Pneumococcal conjugate vaccines require standard cold chain (2–8°C) handling, and stability limitations under elevated temperatures (stability up to a few days at 40°C) influence distribution risk, particularly in decentralized delivery settings.
-
Pricing dispersion: List and tender prices vary widely between private markets in high‑income countries and heavily subsidized or Gavi‑supported programs in low‑income markets. This dichotomy forces manufacturers to adopt differentiated commercial models and to be explicit about cross‑market margin dynamics.
-
Regulatory & payer shifts: Recent regulatory actions and payer updates—ranging from positive CHMP opinions to changes in Medicare reimbursement—are reframing market access timelines and commercial attractiveness for adult vaccination indications.
Competitive landscape — strategies to watch
The pneumococcal vaccine segment remains dominated by a small group of global and regionally important manufacturers. Our competitive assessment highlights three strategic archetypes that will define competitive outcomes in 2026 and beyond:
-
Large integrated innovators: Established multinational vaccine leaders continue to invest in higher‑valency programs and maintain broad commercial reach. Their advantages are deep pockets for late‑stage trials, global regulatory experience, and established tendering relationships.
-
Volume and access specialists: Major contract manufacturers and WHO‑prequalified suppliers are focusing on cost‑efficient supply for large public programs, forming partnerships to localize production and shorten delivery times for immunization campaigns.
-
Specialist and emerging players: Smaller biotech firms are targeting niche value propositions (novel valencies, manufacturing innovations such as new fill‑finish capabilities) that can disrupt pricing and tender outcomes if they achieve scale.
Key companies cited in our study—which are implementing these archetypal strategies—include multinational innovators with broad portfolios, WHO‑prequalified manufacturers focused on access, and regional producers serving domestic and nearby markets. Recent market events illustrate the shifting landscape: a January 2025 partnership for local production under a regional revolving fund, a 2025 CHMP positive opinion for a next‑generation adult vaccine, a 2026 manufacturing line investment by a US biotech focused on fill‑finish capacity, and a 2026 initiation of a high‑valency pediatric Phase 3 program. These developments accelerate regional capability building, shorten procurement lead times, and alter tender dynamics.
Strategic implications and recommended actions for 2026
Our report translates market intelligence into explicit actions investors and commercial leaders should prioritize in 2026. Below are the high‑impact moves we recommend.
-
Prioritize manufacturing and supply‑chain resilience: Evaluate local or regional manufacturing partnerships and invest selectively in fill‑finish capacity or cold‑chain solutions to mitigate lead‑time and temperature‑related risks. Scenario‑based capex planning should be stress‑tested against supply disruptions and scale‑up timelines.
-
Adopt differentiated pricing strategies by channel: Design separate value propositions for public tenders, Gavi or PAHO‑supported programs, and private payors. Use tender simulation tools to model margin outcomes under varying discount and volume assumptions.
-
Align product development with payer evidence needs: Invest in adult and pediatric outcomes data that payers prioritize—real‑world effectiveness, economic models for herd protection, and targeted value dossiers for high‑risk adult populations.
-
Leverage partnerships for market entry: For biotechs and regional players, selective licensing or co‑development agreements with incumbents can accelerate market access while avoiding capital‑intensive global rollouts.
-
Monitor regulatory and reimbursement inflection points closely: Regulatory opinions and public payer updates materially affect launch sequencing. Maintain a regulatory‑watch dashboard to synchronize commercial and market access launches.
-
Prepare acquisition and alliance playbooks: Given the high market concentration, M&A and strategic alliances remain proven levers to gain market share quickly. Use pre‑defined valuation band templates and integration checklists tailored to vaccine assets.
What PW Consulting’s report delivers (practical contents)
The report is built to be immediately actionable for commercial and corporate strategy teams. Key deliverables include:
-
A consolidated market model (historical and forecast) with baseline and alternative scenarios covering 2026–2032;
-
Competitive heatmaps, pipeline trackers, and a regulatory milestone calendar that map product launches to payer decision windows;
-
Manufacturing and supply‑chain risk matrix with prioritized mitigation investments (fill‑finish, cold‑chain, and alternative suppliers);
-
Tender and pricing playbooks with simulation tools for margin and volume tradeoffs across commercial channels;
-
Country prioritization framework and an executable market entry checklist for licensing, partnerships, or greenfield investments;
-
Due diligence templates and an M&A readiness diagnostic for companies evaluating inorganic strategies.
Limits and how to obtain the full granular intelligence
Consistent with our “trailer” approach, this briefing highlights the strategic insights executives need to act in 2026 while intentionally withholding the full set of segmented figures, regional splits, and proprietary worksheets that underpin our models. The granular segmentation—detailing channel, region and application breakdowns, price ladders by market, and proprietary tender‑by‑country analytics—is available through the full report and our interactive web portal. Accessing those elements provides the precise inputs needed to run the scenario and pricing tools described above.
Conclusion
2026 will be a pivot year for the pneumococcal vaccine landscape. Incremental growth at a mid‑single‑digit CAGR masks meaningful structural shifts driven by higher‑valency product rollouts, regional production initiatives, and evolving payer frameworks. Executives who combine a clear understanding of supply chain resilience, differentiated channel economics, and targeted evidence generation will secure disproportionate value. PW Consulting’s report translates these trends into executable strategies, tools, and decision‑grade models for boards and commercial teams preparing for the next phase of the market.
For access to the full dataset, segmented forecast, and the downloadable scenario models that support the recommendations above, visit the PW Consulting report page or contact our advisory desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Pneumococcal Vaccination Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com