

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dental Implant Fixtures Market Set to Expand at 7.01% CAGR as Titanium Fixtures Cement Leadership

Dental Implant Fixtures Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s latest market study on the Dental Implant Fixtures market (base year 2025, historical 2020–2025, forecast 2026–2032) translates granular industry intelligence into an actionable playbook for commercial leaders entering 2026. The sector continues to expand steadily — growing from an estimated USD 4,852.14 Million in 2023 to USD 5,545.0 Million in 2025 and projecting to reach roughly USD 8,947.23 Million by 2032, at a compound annual growth rate of 7.01% over the forecast window. These headline dynamics underline attractive topline momentum, but the strategic challenge for manufacturers, distributors and investors lies in converting growth into sustainable margin and share gains amidst accelerating product innovation, regulatory scrutiny and evolving care pathways.
Dental Implant Fixtures Market
Why this report matters for boardroom decisions in 2026
- Decision-grade forecasts: The report couples scenario-driven forecasts with sensitivity testing to help CFOs and corporate strategy teams stress-test investment cases under different adoption and pricing scenarios for the next seven years.
- Commercial playbooks: Sales, marketing and distribution leaders receive tactical guidance—channel prioritization frameworks, OEM vs. distribution trade-offs, and partnership archetypes—to accelerate penetration without eroding gross margins.
- Regulatory & clinical readiness: Given tightened device standards and the centrality of clinical evidence to adoption, the study outlines pathways for accelerating regulatory clearances and generating practice-changing clinical data.
- M&A and portfolio optimization lenses: Investors and corporate development teams get acquisition scorecards and carve-out rationales that prioritize technology adjacency, margin uplift and cross-sell potential.
What the report delivers — practical content, not platitudes
Beyond headline market sizing and a seven-year forecast foundation, PW Consulting’s report is structured as a toolkit for executable decisions rather than a descriptive overview. Highlights include:
Dental Implant Fixtures Market
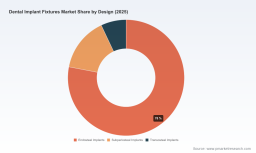
- Market architecture and addressable opportunity analysis by region, material and implant-design categories — modeled with bottom-up unit adoption, ASP trajectories and replacement cycles. (Note: this press release intentionally omits the granular split tables and product-level dollar figures; the full dataset is included in the report.)
- Technology & materials assessment — rigorous evaluation of incumbent materials (Grade 4 titanium and Ti–Zr alloys such as Roxolid) versus advanced ceramic alternatives, including trade-offs in clinical adoption, manufacturing complexity and margin profile.
- Regulatory and standards map — a practical digest of ISO 14801 fatigue testing implications, sterilization requirements aligned with EN 556-1 and AAMI guidance, and navigational notes for achieving FDA 510(k) or CE Mark clearances in reduced timeframes.
- Reimbursement and economic models — procedure-level reimbursement dynamics, care-pathway economics (including DRG-level drivers in mature systems), and profitability levers for clinics and OEMs.
- Commercial intelligence — competitor benchmarking, distribution strategy templates, pricing playbooks and a prioritized list of clinical studies that move purchasing decisions.
- Actionable annexes — deal comparables, manufacturing cost curve models, and an Excel-based forecast engine to run bespoke scenarios using client inputs.
Competitive landscape — what the industry leaders are doing now
The competitive terrain is a blend of large global platform players, innovative mid-sized specialists and regional challengers. Market concentration is meaningful: the top three players account for nearly half the market, and the top five approach two-thirds, which shapes competitive strategy in three ways — scale advantages in R&D and distribution, selective pricing power, and attractive M&A targets among regional specialists.
Dental Implant Fixtures Market
- Straumann Group (Basel, Switzerland) — Continues to drive product-led differentiation with material and system innovation (Roxolid alloys and immediate-loading BLX systems). Recent product introductions emphasize esthetics and surgical simplicity, signaling a focus on premiumization and clinical workflow integration.
- Nobel Biocare — part of Danaher (Zurich, Switzerland) — Maintains a strong clinical and regulatory footprint with implant lines oriented to full-arch solutions and immediate-rehabilitation concepts; recent regulatory clearances have broadened its addressable market in key regulatory geographies.
- Dentsply Sirona (Charlotte, NC, USA) — Leverages long-term clinical datasets to underpin its conical-connection systems; ongoing publication of longitudinal results strengthens adoption among clinician opinion leaders.
- Zimmer Biomet (Warsaw, IN, USA) — Focuses on implant surface and macro-design synergies to improve osseointegration, supported by regulatory recertifications in major markets.
- BioHorizons (Birmingham, AL, USA) — Differentiates via microchannel surface engineering (e.g., soft-tissue attachment technologies) that target clinician preferences for biological outcomes.
- OSSTEM Implant (Seoul, South Korea) & regional brands — Aggressively expand through distribution alliances with global partners, leveraging price-performance for broader market reach.
- Distributors and material specialists (e.g., Henry Schein, Geistlich) — Play pivotal roles in aftermarket consumables, clinical adjuncts and distribution scale; partnership plays can rapidly alter shelf-share dynamics.
Recent moves to watch (selection)
- Straumann’s late‑2024 BLX-R launch underscores a continued premium innovation strategy focused on esthetics and immediate loading workflow efficiency.
- Nobel Biocare’s regulatory approvals in 2024 broaden its commercial flexibilities for certain implant geometries in major markets.
- Dentsply Sirona’s publication of multi‑year clinical evidence for a flagship system continues to be a market-making lever for clinician adoption.
- Regional distribution deals expanding US access for Asian OEMs illustrate the accelerating globalization of lower-cost but clinically validated fixtures.
Key market dynamics shaping competitive and investment decisions
- Clinical evidence is currency: Adoption increasingly hinges on multi‑year outcomes and pragmatic trial designs that mirror real-world practice. Investing in registries and clinician partnerships yields outsized commercial return.
- Material & manufacturing economics: Titanium alloys remain dominant, but materials strategy must balance marginal cost, supply-security and differentiated clinical claims to sustain premium pricing.
- Regulatory complexity: Device standards (e.g., ISO 14801) and sterilization norms shape product development timelines and capital expenditure profiles for manufacturing lines.
- Channel orchestration: Direct sales, distributor partnerships and integrated digital platforms each have distinct margin and scale outcomes — the optimal mix depends on target segments and local regulatory constraints.
- Consolidation & M&A velocity: Given meaningful CR3/CR5 concentration, expect continued interest in bolt-on acquisitions that add novel biologics, digital planning tools or regional footprint.
Strategic checklist for executives entering 2026
- Validate portfolio through unit-economics: identify SKUs with durable pricing power and invest in manufacturing efficiency where ASP pressure is highest.
- Pursue a two-track clinical strategy: randomized or controlled studies for breakthrough claims and pragmatic registries for real-world uptake.
- Design a regulatory playbook up-front: align product, test protocols and sterilization pathways with ISO and regional authority expectations to compress time-to-market.
- Prioritize distribution partnerships in markets where regulatory and commercial barriers are high, while direct models may be preferable where reimbursement and clinical education drive adoption.
- Target tuck-in M&A that accelerates access to digital planning, biomaterials or niche biologic adjuncts that can command premium margins.
Methodology and credibility
This analysis is grounded in a multi-source, reproducible methodology: primary interviews with clinician opinion leaders, purchasing decision-makers and industry executives; audit of company filings and press releases; regulatory and standards review (including ISO, FDA and EU device frameworks); and bottom-up unit/ASP modeling calibrated to observed shipment data and clinic-level economics. The report includes the full forecasting model, competitor scorecards, and an executable go-to-market playbook designed for roll-out in 2026.
Next steps — where to get the full intelligence
PW Consulting’s press summary intentionally surfaces strategic conclusions and executive checklists while withholding full-line segment tables, product-level revenue splits and proprietary model outputs — these detailed deliverables are available in the full report package. For organizations evaluating market entry, product investments, or M&A in 2026, the complete dataset and scenario tools will materially de‑risk commercial choices and shorten decision cycles.
Contact PW Consulting to obtain the full Dental Implant Fixtures Market report, access the downloadable model, and schedule a bespoke strategy workshop to translate market intelligence into a prioritized 90‑day action plan for 2026.
For detailed analysis of this topic, please visit the official page: Dental Implant Fixtures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com