

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Primary Zinc‑Carbon Battery Market at USD 2,121.6 Million in 2025, Poised to Reach USD 2,403.8 Million by 2032 at 1.8% CAGR, Led by Asia‑Pacific

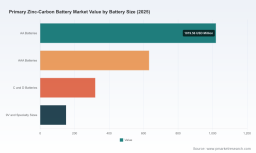
Primary Zinc Carbon Battery Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research — Primary Zinc Carbon Battery Market (base year 2025) — synthesizes a decade of data, supplier intelligence, raw-material dynamics, and regulatory signals into a compact strategic playbook designed for executives planning through 2026. This briefing highlights the report’s strategic value, the key forces shaping the market, and the practical steps executives should prioritize next year. To preserve the commercial value of our granular segmentation and proprietary scenario outputs, detailed region/application splits and unit economics are reserved for report subscribers.
Primary Zinc Carbon Battery Market
Market snapshot: resilience, modest growth, and structural stability
Our assessment places the primary zinc-carbon battery market at USD 2,121.6 Million in 2025 (base year). Over the 2026–2032 forecast window the sector is expected to expand at a compound annual growth rate (CAGR) of approximately 1.8%, reaching just over USD 2,400 Million by 2032. The category has shown episodic volatility in recent years but remains structurally important for low-drain consumer and industrial applications. That modest growth profile, combined with an oligopolistic supplier landscape, creates specific strategic opportunities and risks that corporate leaders must incorporate into their 2026 planning cycles.
Primary Zinc Carbon Battery Market
Why this research matters for 2026 strategies
- Targeted capital allocation: With low but stable growth and limited margin expansion, investment choices must prioritize efficiency gains, regulatory compliance, and channel economics rather than volume-driven capex alone.
- Procurement and supply-risk mitigation: Primary zinc-carbon production is sensitive to manganese and zinc supply dynamics and to changing trade rules; 2026 procurement strategies should be explicitly hedged and diversified.
- Portfolio optimization: The category’s demand remains anchored in low-drain applications. Brand owners, OEMs, and retailers must decide whether to double down on price-led, private-label supply or to differentiate via sustainability and service features.
- M&A and partnership clarity: Consolidation and OEM/private-label plays are visible options; the right moves in 2026 can lock in cost advantages or channel reach without excessive capital commitments.
Key market dynamics for 2026
Four forces will dominate tactical and strategic choices next year: raw materials, regulation, geo-economic policy, and channel demand patterns.
Primary Zinc Carbon Battery Market
- Raw materials and cost pressure.
Electrolytic manganese dioxide (EMD) remains a core cathode input and retains significant end-use exposure to zinc-based batteries due to cost-efficiency in primary applications. Broader manganese markets are growing (our reference sources project mid-single-digit structural demand drivers from adjacent sectors), and zinc mining supply is forecast to expand moderately. These conditions suggest input price volatility will be manageable but persistent — favoring firms with long-term offtake agreements and efficient logistics.
- Regulation and sustainability compliance.
New battery regulatory frameworks, especially in major markets, are raising due-diligence and sustainability reporting requirements for supply chains. Primary batteries are not exempt: traceability and environmental stewardship for cathode and anode feedstocks are emerging procurement filters. Companies that invest early in compliance infrastructure (chain-of-custody, material audits, supplier scorecards) will face lower friction entering regulated markets in 2026.
- Geopolitical and trade policy impacts.
Tariff adjustments and critical-minerals policies enacted through 2025 and into 2026 reshape sourcing economics for certain inputs and finished imports. Executives must factor scenario-based tariffs and selective restrictions into sourcing stress-tests and should consider near-shoring or regional supply hubs where feasible.
- Demand profile: resilient, low-margin, channel-sensitive.
End demand continues to be dominated by low-drain devices where price-per-unit and availability drive purchasing; however, pockets of premiumization appear in branded convenience channels. Retailers and distributors are thus balancing between private-label scale plays and branded assortments that trade on reliability and sustainability credentials.
Competitive landscape — what the report reveals (high level)
The primary zinc-carbon battery market displays moderate concentration: our market concentration metrics show the top three producers control a notable share of industry revenue, and the top five increase that concentration further. The competitive field mixes major global brands, regional champions, and a large set of OEM/private-label manufacturers. Key archetypes include:
- Global branded incumbents — Firms with historic consumer recognition and global distribution reach continue to compete on brand trust, channel penetration, and selective premium SKUs. These players invest in marketing, quality assurance, and selective innovation targeted at differentiated applications.
- Regional and cost-competitive manufacturers — Large-scale producers focused on export and private-label supply leverage scale, low-cost manufacturing footprints, and tight trade-channel relationships to serve price-sensitive markets.
- OEM and specialized producers — A broad segment of dedicated OEMs supply retailers, wholesalers, and industrial customers; flexibility and reliability are their chief competitive propositions.
Prominent companies profiled in our research include Panasonic Energy Co., Ltd., Energizer Holdings, Inc., GP Batteries, FDK, Toshiba, and several large Chinese and Indian manufacturers that dominate export and private-label volumes. Their strategic orientations vary: global brands emphasize channel differentiation and selective R&D; leading OEMs prioritize cost, scale, and supply reliability. Separately, trade-show activity and export promotion among manufacturers underscore ongoing efforts to expand geographic reach and to capture retailer shelf space in growth markets.
What the report contains — practical, transaction-ready outputs
PW Consulting’s full report is structured as a practitioner's toolkit and includes:
- Validated historic series and a 2026–2032 forecast model (sensitivity-tested across multiple price, supply, and regulatory scenarios).
- Supplier and capacity mapping with node-level risk ratings and lead-time analytics.
- Regulatory impact assessment and compliance checklist for major markets.
- Raw-material cost model and procurement stress-test templates for manganese and zinc exposures.
- Commercial playbooks for branded, private-label, and OEM strategies, including channel economics and margin simulations.
- An M&A and partnership matrix identifying targets by strategic fit (scale, capability, channel access) — with prioritized roadmaps.
- Operational levers to reduce unit cost and improve working capital — including lean manufacturing and inventory optimization recommendations.
Note: granular regional and application split tables, unit-volume breakouts, and company-level share details are intentionally omitted from this public briefing and are accessible exclusively within the full report package.
Practical 2026 playbook — prioritized actions for executives
- Immediate (0–6 months)
- Run supplier stress-tests: model tariff scenarios and alternate sourcing routes for manganese compounds and zinc feedstocks.
- Solidify short-term offtake agreements and hedges for EMD and zinc where price exposure threatens gross margins.
- Prioritize regulatory compliance planning for key sales markets — appoint a compliance lead, and complete a gap analysis against new batteries regulation requirements.
- Near-term (6–18 months)
- Execute channel segmentation: decide where to compete on price vs. differentiation; adjust SKUs and packaging to improve shelf economics.
- Pursue selective partnerships or contract manufacturing to shore up supply without large capex commitments.
- Pilot sustainability and traceability initiatives to reduce market-access friction in regulated markets.
- Medium-term (18–36 months)
- Assess M&A and bolt-on opportunities to capture distribution scale, technology inputs, or geographic access — focus on accretive, low-integration-risk targets.
- Invest in process improvements and quality control systems to reduce warranty and returns costs while enabling modest product premiumization.
- Formalize a multi-scenario strategic playbook that maps decisions to market states (e.g., sustained high-input-price, restrictive trade environment, or accelerated premiumization).
Closing — how PW Consulting helps you act in 2026
For executives committing budgets and making sourcing, channel, and M&A decisions in 2026, the primary zinc-carbon battery market presents a mix of stable demand and evolving supply-side complexity. Our research gives you the forecast lens, supplier-level intelligence, regulatory mapping, and playbooks necessary to convert market stability into competitive advantage. The intelligence in this briefing is directional by design; the full report contains the detailed segmentation, supplier scores, and unit economics you will need to execute with confidence.
To obtain the full Primary Zinc Carbon Battery Market report and the accompanying models and playbooks, please visit PW Consulting’s research portal or contact your account lead for an executive briefing and data package.
For detailed analysis of this topic, please visit the official page: Primary Zinc Carbon Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com