

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Nitroguanidine Market Poised for Steady Expansion at a 4.28% CAGR Through 2032

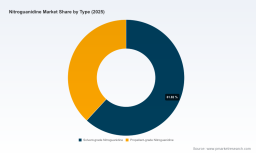
Nitroguanidine Market Outlook 2026: Strategic Imperatives for Industrial, Agrochemical and Defense Players
PW Consulting's latest Nitroguanidine Market report is published as companies prepare 2026 budgets and portfolio decisions under rising regulatory scrutiny and an evolving supply base. Our analysis shows the global Nitroguanidine market expanded from USD 462.15 Million in 2020 to USD 565.4 Million by the 2025 base year, and is forecast to continue growing at a 4.28% compound annual growth rate through the 2026–2032 period (reaching USD 758.17 Million by 2032). This release summarizes the strategic takeaways executives and investors must factor into near‑term plans while intentionally withholding granular segment tables to encourage review of the full report for transaction‑grade detail.
Nitroguanidine Market
Why this report matters for 2026 decision cycles
- Timing sensitivity: Several capacity and policy inflection points converge in H2 2026. Procurement, commercial and capital planning that assume business‑as‑usual risk serious mispricing and availability issues if they ignore these changes.
- Demand mix uncertainty: End‑market drivers (agrochemicals, defense propellants, automotive safety systems and select pharmaceutical intermediates) are diverging — each requires a different product quality, supply risk profile and regulatory playbook.
- Consolidation and concentration: Market concentration is material — the top three suppliers account for a majority share and the top five for nearly 70% — creating asymmetry in negotiation leverage and supply risk.
- Actionable modeling: The report provides forward‑looking demand/supply balances, price‑sensitivity scenarios and investment break‑evens that support procurement contracts, capital allocation and M&A screening for 2026 timelines.
High‑level market dynamics shaping 2026
- Measured growth with pockets of volatility: The market’s steady mid‑single digit CAGR masks asymmetric shocks by application. Overall scale is expanding modestly from the 2025 base, but sectoral reallocations will create winners and losers among producers and buyers.
- Supply‑side turning points: A major incumbent has announced and progressed a capacity expansion in Europe — new capacities are scheduled to start in H2 2026 and are supported by defense customer contracts and public grant funding. That supply coming online will materially affect regional flows and contract pricing dynamics for the back half of 2026.
- Upstream feedstock dependency: Nitroguanidine manufacture is tightly coupled to guanidine nitrate production (itself produced from urea and ammonium nitrate) and to dehydration chemistry that typically uses concentrated acids. Feedstock availability, fertilizer markets and acid handling constraints are therefore direct drivers of production cost and operational risk.
- Regulatory overlays: Regulatory decisions affecting neonicotinoid derivatives have already altered demand patterns in certain markets; ongoing restrictions tied to pollinator health and pesticide reappraisals will continue to affect demand for Nitroguanidine as an agrochemical intermediate. Companies must coordinate regulatory intelligence with commercial planning.
Competitive landscape — what incumbent moves mean for 2026
Our competitive mapping highlights several archetypes among the global supplier set: vertically integrated, export‑oriented large producers in Asia; specialty, quality‑focused producers in Europe and North America; and diversified agrochemical groups that supply intermediates as part of a broader portfolio.
Nitroguanidine Market
- Vertically integrated European/Western players: These firms emphasize high‑purity product grades, backward integration into guanidine nitrate and proximity to defense and automotive customers. A recent announced expansion by a leading European manufacturer — backed by an EU grant and secured defense offtakes — will tighten the market for high‑spec grades during the commissioning window and create contracting opportunities for offtake partners and licensors.
- US specialty producers: North American specialty producers differentiate on quality control and integrated supply to safety‑critical markets (e.g., airbag inflator propellants). Their integration strategy reduces transit risk for customers who prioritize continuity over lowest cost.
- Large scale Asian suppliers: Several Chinese manufacturers supply high volumes into agrochemical supply chains and pesticide intermediate markets. Their competitive strength is scale and cost position, particularly for industrial and agrochemical grades. This creates bifurcated pricing and delivery expectations by application.
- Implication for buyers and investors: The top three suppliers hold a dominant share of the market, and the top five concentrate nearly 69% of capacity — creating outsized influence on pricing, technology trajectory and consolidation dynamics. For buyers, this argues for diversified sourcing and strategic contracts; for investors, it highlights targets for bolt‑on M&A or JV structures to access specific quality grades or regulatory jurisdictions.
Practical playbook for 2026: procurement, portfolio and M&A
Companies should adopt an integrated playbook that aligns commercial, supply‑chain and regulatory actions with capital and M&A planning. Our report supplies the modelling behind these recommendations; high‑level tactical moves include:
Nitroguanidine Market
- Immediate (Q1–H1 2026): Execute short‑term hedges and conditional offtake agreements that include volume flex options timed around H2 2026 commissioning dates. Reassess existing contracts for force majeure and supply prioritization clauses tied to defense and safety customers.
- Mid‑term (H2 2026–2027): Rebalance portfolios by quality grade — secure higher‑purity capacity for propellant and airbag customers while sourcing cost‑competitive industrial grades for agrochemical intermediates. Prioritize suppliers with backward integration into guanidine nitrate to reduce feedstock pass‑through risk.
- Strategic (2026–2030): Consider targeted M&A or minority investments in upstream guanidine nitrate plants, or in specialty downstream conversion technologies that create product differentiation (grain size, moisture specification, impurity profile). The economics shown in our scenario models indicate that modest share gains in high‑spec segments can materially improve margins.
- Regulatory engagement: Establish cross‑functional regulatory monitoring to track neonicotinoid policy developments and ensure R&D pipelines include non‑neonic alternatives where relevant. For suppliers, invest in compliance documentation and traceability to keep EU/US defense and automotive customers.
- Operational resilience: Stress‑test plants for acid handling and feedstock variability; invest in nitration safety and emissions control to minimize shutdown risk and regulatory exposure.
What the PW Consulting report delivers (operational toolkit)
The full Nitroguanidine Market report goes beyond narrative: it contains scenario‑driven financial models, supplier scorecards, demand drivers by application and market‑by‑market supply balances, and a prioritized list of strategic actions with modeled outcomes. Key deliverables include:
- Demand and supply model with base and alternate scenarios through 2032, including sensitivity to feedstock and regulatory shocks.
- Price and margin impact simulations for quality grades used in automotive, defense and agrochemical markets.
- Detailed company profiles and capability assessments for global suppliers, including backward‑integration status and strategic initiatives.
- Transaction screening matrix for M&A and joint ventures with indicative valuation ranges and integration risks.
- Regulatory risk register and mitigation playbook aligned to major regional policies and pesticide reappraisals.
- Implementation gantt for procurement and CAPEX timing that aligns with the market’s 2026 inflection points.
Trailer note — what we are not publishing here
To preserve the utility of the research for decision makers and to support confidential diligence, this announcement intentionally omits the granular regional and application split tables, specific supplier shares by grade, and the itemized price trajectories that underpin our models. Those datasets are included in the full report and are provided with supporting workbooks for licensed clients and diligence teams.
How to access the intelligence and next steps
Executives preparing 2026 budgets, procurement teams negotiating supply agreements, and investors screening opportunistic targets should request the full Nitroguanidine Market report and model package. PW Consulting can provide tailored briefings, scenario workshops and custom diligence packages that overlay your portfolio positions on our market model.
Contact PW Consulting’s Industrial Chemicals Practice to schedule a briefing and obtain access to the complete dataset, supplier scorecards and scenario models needed to convert the 2026 inflection into strategic advantage.
For detailed analysis of this topic, please visit the official page: Nitroguanidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com