

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Explosive Growth Ahead: PW Consulting Forecasts Food-Grade Urolithin A Market to Expand at a 17.5% CAGR

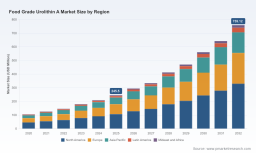
PW Consulting: Food Grade Urolithin A Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
Our new Food Grade Urolithin A Market report equips commercial leaders with the market intelligence required to make decisive, risk-calibrated moves in 2026. The Urolithin A market has accelerated rapidly from a niche research ingredient in 2020 to a commercially meaningful food-grade category by 2025. After expanding from an estimated USD 105.3 million in 2020 to USD 245.5 million in 2025, the category is forecast to grow to approximately USD 759.1 million by 2032 — reflecting a compound annual growth rate (CAGR) of 17.5% across the 2026–2032 forecast window. The 2026 opening-year projection (USD 294.5 million) marks a critical inflection point for procurement, product development and capital allocation decisions.
Food Grade Urolithin A Market
Why this report matters for 2026 strategy
-
Timing and investment prioritization: The projected high-growth trajectory requires teams to decide in 2026 whether to invest now in differentiated formulations, secure supply via long-term contracts, or adopt a wait-and-see stance that risks margin erosion and lost shelf space.
Food Grade Urolithin A Market -
Supplier selection and risk management: With a market structure that shows meaningful concentration among top suppliers, procurement strategies must balance cost, purity, and supply security to avoid single-source dependencies.
Food Grade Urolithin A Market -
Commercial claims and clinical positioning: Clinical evidence is increasingly the differentiator. Brands partnering with clinically validated suppliers or investing in proprietary trials will capture the premium segment.
-
Regulatory and route-to-market clarity: The U.S. GRAS precedent for specified uses provides commercial pathways, but regional regulatory variance and labeling constraints require tailored launch plans for each market.
What’s inside the report — practical, executable intelligence
The report is designed for decision-makers who need more than high-level narrative. Key deliverables include:
-
A calibrated market-sizing model (historical 2020–2025 and forward-looking 2026–2032) with scenario-based forecasting and sensitivity testing for pricing, adoption curves and purity premium capture.
-
Demand-driver mapping that links consumer trends (longevity, active aging, cognitive and mitochondrial health) to commercial adoption pathways across supplement, food and beverage channels.
-
Supply-chain maps and supplier scorecards that assess manufacturing capacity, quality systems (GMP/GMP-like), route-of-supply (synthetic vs. fermentation), scalability, and export compliance.
-
Regulatory playbook summarizing the practical implications of existing precedents (including GRAS) and a roadmap for dossier preparation, claims substantiation, and jurisdiction-specific labeling strategies.
-
Commercial playbooks for product teams: SKU-level launch plans, pricing frameworks, packaging & claims examples, and channel-specific adoption tactics for 12–24 month pilots.
-
Competitive benchmarking and a curated supplier directory with contact-ready profiling for diligence and RFQ outreach (note: granular segment allocations are withheld from this public summary; full supplier matrices are available in the report).
-
Strategic M&A and partnership assessment: target archetypes, valuation heuristics, and integration risk checklists tailored to buyers seeking capacity, IP or clinical platform assets.
Competitive landscape — evidence-driven implications
Our structural analysis finds a market with meaningful concentration at the top: the three largest suppliers together control a significant share of industry revenues, and the top five account for an even larger portion — a situation that both enables premium positioning and creates supply risk for buyers. This concentration favors players who combine IP-backed clinical evidence with scalable manufacturing.
Key strategic profiles emerging from our vendor review:
-
Clinical-anchored leader(s) : Some companies have established a clinically substantiated product narrative allied with regulatory precedence in target markets. Those players command premium positioning for finished goods co-brands and ingredient licensing.
-
Manufacturing specialists : A cluster of producers focuses on high-purity bulk supply and cost-efficient production. These suppliers are attractive partners for brands that prioritize margin and rapid scale but require rigorous QA/QC protocols.
-
Emerging fermentation innovators : Newer entrants using microbial fermentation routes are positioned to improve sustainability and reduce reliance on synthetic chemistry, offering a differentiation route for future-proof portfolios.
Recent clinical milestones — notably late-2025 updates from clinical-led suppliers — materially strengthen the evidence base for claims related to mitochondrial health, muscle function and cognitive endpoints. For brands and ingredient buyers this creates a two-track commercial environment in 2026: clinically-validated Mitopure-style propositions competing alongside commodity-grade supply. The practical implication is that go-to-market strategy must align product claims, price points and channel selection with the supplier’s clinical and regulatory standing.
Strategic playbook for 2026 — prioritized actions
-
Secure supply, then optimize purity mix: Implement a tiered sourcing approach — secure a core supply tranche under medium-term contracts, while piloting higher-purity clinical-grade inventory for premium SKUs. Include audit and release testing milestones in contracts.
-
Align claims with clinical evidence: Only partner for finished-goods claims that can be substantiated. Invest in bridging studies where necessary to extend clinical endpoints to your formulation or population.
-
Run rapid-market pilots: Deploy 6–12 month market tests for two product concepts (clinical-premium and value-mainstream) with clear KPI targets on trial conversion, repeat purchase, and CAC payback period.
-
Negotiate IP and co-marketing terms: For brands seeking exclusivity, consider time-limited regional co-branding arrangements tied to sales milestones and minimum purchase obligations rather than upfront exclusivity fees.
-
Invest in supply-chain resilience: Dual-source key materials, prequalify alternative suppliers, and evaluate near-shore manufacturing options to mitigate logistics and geo-political risk.
-
Prepare regulatory dossiers in parallel: Use existing GRAS precedents to accelerate U.S. commercial launches while preparing jurisdiction-specific submissions for other priority markets.
Commercial risks and mitigation
-
Regulatory drift: Ongoing changes in novel-ingredient scrutiny could alter permissible use-cases. Mitigation: maintain regulatory monitoring and a staged rollout aligned to local approvals.
-
Supply concentration: High market share among top suppliers creates negotiation asymmetry. Mitigation: enter multi-year commitments with flexibility triggers, and invest in qualifying alternative producers.
-
Quality variability: Differences in purity, residuals and process impurities can affect label claims and safety perceptions. Mitigation: demand batch-level COAs, third-party testing, and supplier audits.
-
Market adoption uncertainty: Consumer understanding of “Urolithin A” is nascent. Mitigation: allocate budget to educational marketing, clinician outreach and evidence-based storytelling.
How to use this report in 2026 — three practical scenarios
-
C-suite capital allocation: Use the report’s financial model to stress-test capex for fermentation capacity vs. contract manufacturing and to model ROI timelines for clinical investments.
-
Sourcing and procurement: Leverage the supplier scorecards and contract templates to shorten negotiation cycles and lock in quality-verified supply with protective terms.
-
Product and commercial teams: Apply the go-to-market playbooks to run A/B launch tests, validate consumer messaging, and refine pricing strategies that reflect purity and clinical positioning.
Next steps
PW Consulting’s Food Grade Urolithin A Market report is deliberately structured as a decision-ready toolkit for 2026: it reveals the macro growth trajectory and competitive structure while reserving granular, segment-level matrices to subscribers and clients who need the full dataset for contract negotiations and financial modeling. For commercial leaders planning launches, sourcing, or M&A activity, the report converts market dynamics into executable priorities with timelines, KPIs and contractual templates.
To access the complete supplier matrices, segment-level forecasts, downloadable financial models and market-entry playbooks, request the full PW Consulting report and associated client briefing. Our team can also deliver a tailored, confidential strategy session to translate global forecasts into an actionable 18–36 month roadmap aligned to your portfolio and risk appetite.
For detailed analysis of this topic, please visit the official page: Food Grade Urolithin A Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com