

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Silicon 28 Market to Expand from USD 32.45 Million in 2025 to USD 108.0 Million by 2032, Powered by an 18.74% CAGR

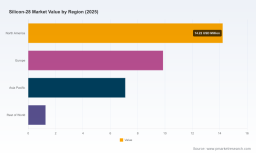
Silicon‑28 Market Outlook 2026: Strategic Imperatives from PW Consulting’s Silicon 28 Market Report (Silicon 28 Market — Silicon 28 Market)
Executive summary
PW Consulting’s new Silicon 28 Market report delivers a focused, actionable roadmap for corporate decision‑makers planning for 2026 and beyond. The silicon‑28 (Si‑28) supply chain — once a narrow research niche — is entering a commercial inflection driven by quantum computing, advanced semiconductor R&D, and precision metrology. Our baseline analysis, calibrated to a 2025 base year and covering 2020–2025 historical performance with a 2026–2032 forecast window, projects sustained expansion at a compound annual growth rate (CAGR) of 18.74%. That expansion moves the global market from a modest research‑era scale in 2025 to a materially larger commercial market by the early 2030s. This report is designed to help strategy teams, procurement leaders, and technology investors prioritize moves that matter in 2026 without overwhelming them with proprietary segment tables in this release.
Silicon 28 Market
Why 2026 is a strategic pivot
The calendar year 2026 represents the first full year when multiple commercial supply streams and industrial buyers converge. For the first time since experimental production efforts began, commercial‑scale shipments and multi‑party contracts move Si‑28 from early adopter trials into supply agreements that can underpin product roadmaps. That transition changes the questions executives must ask: not whether enriched Si‑28 will be available, but at what quality, cadence, and contractual terms it will be integrated into product and process workflows. Our report translates that systemic change into decision frameworks for sourcing, technology validation, and capital allocation.
Silicon 28 Market
Market trajectory and what the numbers mean
-
Momentum: The market exhibits a continuation of the steep growth path observed in the historical window. The underlying growth drivers are technical adoption cycles (quantum and precision semiconductors) and a widening set of industrial use cases.
Silicon 28 Market -
Scale: By anchoring our analysis to 2025 as the base year and running a scenario suite across conservative, central, and aggressive demand paths, the market reaches a materially higher scale by the end of the forecast period. This is driven by commercialization milestones, higher throughput at leading facilities, and the maturation of conversion and wafer‑level processes compatible with isotopically enriched feedstocks.
-
Concentration: Supply is highly concentrated. Measured concentration ratios highlight that a small set of suppliers will account for the majority of commercial availability in the near term — a structural characteristic that elevates counterparty risk, negotiating leverage, and the strategic value of long‑lead supply contracts.
Strategic imperatives for corporate leaders in 2026
-
Procurement: Move from spot testing to contracting where possible. Short lead‑time sample testing will still be necessary, but formalized offtake frameworks and quality‑assurance clauses will de‑risk product roadmaps that depend on high‑purity isotopic inputs.
-
R&D integration: Lock experimental protocols to production‑representative materials early. The gap between research‑grade samples and production processable feedstocks is non‑trivial; early alignment with suppliers on conversion and impurity budgets reduces downstream yield surprises.
-
Manufacturing readiness: Invest in conversion and handling capacity. Isotopically enriched materials often require dedicated conversion lines and traceable handling to preserve isotopic integrity; investment timing should be synchronized with supplier ramp signals.
-
Risk management: Treat supplier concentration as a strategic risk. Alternative sourcing pathways and dual‑sourcing pilots are not luxury projects in 2026 — they are insurance against production disruptions and geopolitical constraints.
Competitive landscape — what the report unpacks
Our competitive analysis synthesizes public disclosures, primary interviews, and supplier technical data to create operational profiles, capability maps, and likely supply‑demand pairings. The market is shaped by technologically differentiated players that fall into three practical archetypes: (1) commercial innovators deploying novel aerodynamic or advanced separation technologies; (2) legacy gas‑centrifuge and diffusion operators adapting isotope know‑how from adjacent sectors; and (3) flexible specialty suppliers offering tailored enrichment and small‑batch services. Key examples we analyze in depth include ASP Isotopes Inc., European centrifuge operators, and a set of specialized suppliers that together determine near‑term availability and technical support.
-
ASP Isotopes Inc. — As the first mover to ramp commercial production using an aerodynamic separation approach, ASP has signaled a step change in throughput capability and commercial engagement. Our report examines its multi‑facility production profile, enrichment performance milestones, commercialization cadence, and the implications for supply security in western markets.
-
Centrifuge‑based suppliers — Operators who have adapted centrifuge and gaseous processing know‑how provide a different risk/benefit profile: strong process reliability and regulatory experience, but longer lead times to reconfigure capacity for ultra‑high enrichment grades.
-
Specialty and service providers — Smaller vendors play a critical role in niche metrology and research markets, and they remain important partners for validation, small‑volume trials, and conversion services.
Supply chain & raw materials — practical levers
From feedstock quality to conversion technology, supply chain nuances have outsized commercial impact. The report maps the key conversion steps from precursor chemistry through wafer fabrication, identifying which stages are most susceptible to bottlenecks, material loss, and isotopic degradation. We provide a decision matrix for where to invest in internal capabilities (e.g., dedicated conversion lines, traceable QA labs) versus where to rely on supplier partnerships. We also model sensitivity to precursor supply interruptions and process yield variation so procurement and operations teams can quantify the cost of different resilience strategies.
Regulation, safeguards and geopolitics
The regulatory backdrop matters. Some enrichment facilities operate under international safeguards and inspection regimes that enhance market confidence but introduce export, transport, and compliance obligations that buyers must operationalize. National stable‑isotope programs and government procurement strategies are emerging as demand anchors in several jurisdictions. Our report provides a compliance playbook that maps inspection regimes, likely transit constraints, and the contractual language buyers should expect when dealing with safeguarded facilities.
What’s inside the PW Consulting Silicon 28 Market report
-
Market sizing and forecast (2020–2032): A transparent model built on historical data and multiple demand scenarios driven by quantum hardware roadmaps, semiconductor R&D trajectories, and standards/metrology adoption.
-
Supplier capability dossiers: Operational parameters, technology differentiation, facility readiness indicators, and a vendor risk matrix to support sourcing decisions.
-
Procurement playbook: Contract structures, quality and acceptance test templates, and recommended SLAs to secure production‑grade supply.
-
Investment and M&A implications: Criteria for vertical integration, partnership models, and valuation sensitivities for strategic investments in conversion or enrichment capacity.
-
Operational checklists: Step‑by‑step guidance for integrating isotopically enriched feedstocks into wafer fabs and quantum device manufacturing lines, minimizing yield impact and isotopic loss.
How to use this report in 2026 planning cycles
We designed the report to be directly deployable in three common corporate workflows:
-
Capital planning: Align capital deployment for conversion and QA infrastructure to supplier ramp milestones and contractual delivery schedules.
-
Supplier selection: Use the vendor risk matrix and capability dossiers to prioritize pilots, negotiate offtake, and stage investments in joint validation work.
-
Product roadmapping: Ground product launch timelines in realistic supply availability windows and QA requirements, avoiding optimistic assumptions that have tripped product teams in historical materials transitions.
Read between the lines — what we intentionally withhold here
This release is a strategic preview. To maintain tactical confidentiality and to preserve the commercial sensitivity of suppliers and buyers, we have omitted granular segmentation tables and the detailed regional/application revenue breakdowns from this press summary. The full report includes proprietary segment-level models, supplier volume allocations, and downloadable decision tools. Those artifacts are available with the full report purchase and are designed to be plugged directly into procurement, R&D, and finance workflows.
Conclusion & next steps
For organizations making go/no‑go decisions in 2026, the central choice is not whether isotopically enriched silicon will matter — it already does — but how to structure the organization to procure, qualify, and scale with it. PW Consulting’s Silicon 28 Market report transforms market provenance, supplier intelligence, and operational checklists into a single pragmatic toolkit. Executives who adopt the report’s frameworks will be positioned to convert early supply certainty into competitive product advantage while avoiding common pitfalls around supplier concentration, material conversion, and regulatory compliance.
Action
To obtain the full Silicon 28 Market report, including the downloadable supplier dossiers, scenario models, and procurement templates, visit the PW Consulting report page or contact our industry practice for a briefing. Our analysts are scheduling limited one‑on‑one briefings in Q3 2026 to walk through customized implications for corporate sourcing, R&D roadmaps, and investment theses.
For detailed analysis of this topic, please visit the official page: Silicon 28 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com