

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PVDF‑TrFE Resin Market Set to Grow at 12.18% CAGR, Reaching USD 698.65 Million by 2032

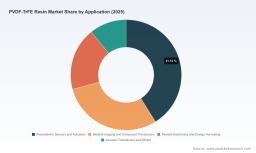
PVDF‑TrFE Resin Market: Strategic Insights for 2026 — A PW Consulting Executive Brief
As industry leaders recalibrate strategies for the accelerating electrification and advanced sensor markets, PVDF‑TrFE resin has emerged from niche polymer chemistry to a core materials play. PW Consulting’s latest market research — with base year 2025, a historical window covering 2020–2025, and a forecast through 2032 — quantifies that transition and translates it into decision-grade guidance for 2026. Our forecast phase (2026–2032) projects a robust compound annual growth rate (CAGR) of 12.18%, with total market value expanding more than twofold from the mid‑2020s to 2032. This brief explains why 2026 is a pivotal year for investment, capacity planning, and commercial differentiation, and what practical steps executives must consider now.
PVDF-TrFE Resin Market
Market trajectory: measured acceleration, persistent concentration
PVDF‑TrFE resin has exhibited steady expansion through the historical period, driven by rising adoption across piezoelectric sensors, flexible electronics, medical ultrasound, and energy‑harvesting devices. By 2025 the market reached a clear inflection point that sets the stage for faster deployment of materials into high‑value, volume‑sensitive applications. Our projection to 2032 reflects both the secular demand for polymer‑based piezoelectric materials and the expected maturation of manufacturing and application ecosystems.
PVDF-TrFE Resin Market
Two structural features matter for strategy: first, the market retains a high degree of concentration at the top. The three largest producers collectively account for a dominant share of supply, and the top five firms consolidate nearly nine‑tenths of the market — a dynamic that creates entry barriers but also predictable partnership pathways for new entrants and downstream integrators. Second, the supply base is sensitive to upstream raw‑material swings and to process complexity — factors that create differentiated margin pools across suppliers.
PVDF-TrFE Resin Market
Why 2026 is strategic — five executive takeaways
- Lock in feedstock and process resilience. Volatility in vinylidene fluoride (VDF) prices and the specialized polymerization required for PVDF‑TrFE mean procurement strategies built around spot buying will face margin pressure. Strategic offtake agreements and process optimization initiatives completed in 2026 will materially reduce total cost of ownership over the forecast horizon.
- Invest in tailored capacity or partnerships, not generic volume. Given the market concentration and premium for advanced grades, targeted capacity expansions or toll‑manufacturing partnerships for differentiated grades will yield higher returns than race‑to‑volume plays.
- Prioritize regulatory‑compliant, low‑emissions production methods. Stricter environmental rules in certain European markets are already shaping supplier selection — firms that invest in sustainable process upgrades and transparent ESG reporting will access preferred buyer lists.
- Differentiate via formulation and downstream integration. Value capture increasingly shifts to suppliers who offer formulated resins, inks, films, and application kits that reduce adoption friction for device OEMs.
- Consider M&A and selective vertical integration. The oligopolistic structure presents opportunities for bolt‑on acquisitions that secure technology, proprietary grades, or regional distribution, accelerating market access without incurring full greenfield risk.
What PW Consulting’s full report delivers — operationally actionable content
Our report is built for executives who must convert technical markets into board‑level decisions. It reframes chemistry and markets into executable workstreams across product, supply chain, commercial, and regulatory functions. Highlights include:
- Proven forecasting methodology and scenario models that translate end‑market adoption curves into capacity utilization and profitability scenarios for 2026–2032.
- Supply chain mapping that identifies single‑point failures, lead‑time sensitivities for VDF feedstock, and recommended hedging instruments for procurement teams.
- Cost benchmarking and margin waterfall analyses that quantify the impact of specialized polymerization (a documented incremental cost factor versus standard fluoropolymers) and show where operational improvements unlock competitive advantage.
- Go‑to‑market playbooks for suppliers and downstream integrators — from tiered pricing frameworks for formulated products to proof‑of‑concept kits for medical and wearable OEMs.
- Investment due diligence templates for capacity expansions, including capex sizing, payback sensitivity to raw‑material volatility, and contract structures that mitigate exposure.
- A regulatory compliance roadmap that aligns production and product specs with emerging environmental standards in key jurisdictions.
- Target lists and valuation heuristics for M&A and licensing opportunities that complement core capabilities rather than dilute margin pools.
We designed these modules to be directly usable: procurement leaders can adapt hedging steps, R&D heads receive a prioritized technology agenda, and corporate development teams obtain an actionable acquisition scorecard.
Competitive landscape: strategic positioning of core players
The PVDF‑TrFE market is shaped by a handful of suppliers with differentiated platforms — global chemical majors, specialty polymer manufacturers, and agile niche specialists. PW Consulting’s competitive analysis synthesizes company capabilities, channel reach, and recent strategic moves to inform partnering and competitive responses.
- Arkema Piezotech (France). Arkema offers a vertically integrated portfolio of electroactive copolymers in powders, inks, and films. Its product breadth across piezoelectric, pyroelectric, and ferroelectric applications positions it well for OEMs seeking single‑vendor simplification. Notably, Arkema announced a capacity expansion in early 2025 focused on innovative grades for EV and energy storage applications — a decisive capacity play that underlines its intent to serve high‑growth end markets.
- Solvay (Belgium). Solvay leverages scale and specialty‑polymer expertise to supply high‑performance PVDF‑based fluoropolymers. Its global commercial network and application engineering capabilities make it a preferred supplier for high‑reliability electronics and sensor suppliers.
- Kureha Corporation (Japan). Kureha’s long history in PVDF manufacturing lends depth to polymer‑grade control and supply stability. Its engineering know‑how is a competitive asset for customers requiring tight material specs across temperature and long‑term stability conditions.
- PolyK Technologies (United States). PolyK’s focus on R&D volumes, films, and resin kits makes it a magnet for innovation partnerships and early‑stage application development. Its ability to supply small to bulk quantities from multiple sources supports prototype and pilot programs for OEMs.
- Peraglobe (United States). The company targets premium PVDF and PVDF‑TrFE grades alongside sensors and transducer solutions — a hybrid model that captures value both upstream (resins) and downstream (components), appealing to buyers who prioritize integrated solutions.
Collectively, these firms create a competitive topography that favors differentiated product portfolios, application support, and supply reliability. The report evaluates strategic responses for challengers and incumbents, including co‑development agreements, supply security contracts, and selective captive capacity.
Supply dynamics and the hidden cost levers
Two upstream facts shape profitability and procurement strategy. First, VDF monomer price volatility materially affects unit economics; procurement teams must design flexible contracts that balance price certainty with supply agility. Second, PVDF‑TrFE manufacturing uses specialized polymerization sequences that increase production costs relative to commodity fluoropolymers — our analysis quantifies this premium and maps where process improvements or economies of scale can compress that gap.
For executives, the implication is clear: margin improvement is a combined play of input risk management and process engineering. Where capacity expansion is contemplated, investment in process intensification or selective automation often yields faster returns than pure throughput increases.
Regulatory and sustainability dynamics
Environmental compliance is no longer a checkbox. Regions with stringent environmental standards are accelerating the adoption of cleaner production methods for fluoropolymers. Suppliers that proactively redesign production footprints and provide verifiable environmental metrics will not only reduce regulatory risk but also win contracts with buyers who have aggressive ESG mandates. The report includes a compliance impact matrix and a staged roadmap to sustainable production that is aligned with the timelines procurement and compliance teams face in 2026.
How to use this research in your 2026 planning cycle
- Embed the report’s scenario models in your capital planning to stress test payback periods under different VDF price assumptions.
- Prioritize partnerships for differentiated grades and formulation capability rather than undifferentiated volume deals.
- Mobilize an interdisciplinary task force (procurement, R&D, legal, and corporate development) to execute a six‑month playbook: secure feedstock corridors, select two preferred suppliers, and define pilot applications with OEM customers.
- Use the M&A scorecard to evaluate targets that deliver either unique formulation IP or regional market access without diluting margin profiles.
Conclusion — trusted foresight, curated disclosure
PVDF‑TrFE resin is entering a phase where material science meets scalable commerce. For 2026, the window for securing advantaged positions — through offtake, capacity, or technology partnerships — is open but narrowing. PW Consulting’s report provides the models, due‑diligence tools, and tactical playbooks needed to convert 2026 actions into durable competitive advantage.
In keeping with our “prequel” approach, this executive brief demonstrates the depth of our analysis while deliberately withholding the granular regional and application split tables that are core to tactical sourcing and commercialization decisions. To access the complete datasets, segmentation matrices, and downloadable scenario models that enable implementation, please visit our official report page and request the full PVDF‑TrFE Resin Market pack.
For detailed analysis of this topic, please visit the official page: PVDF-TrFE Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com