

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PF3 Market Set to Rise from USD 72.45 Million in 2025 to USD 120.19 Million by 2032, Driven by a 7.5% CAGR

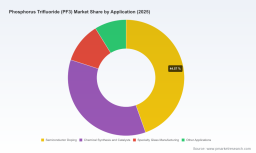
Phosphorus Trifluoride (PF3) Market Outlook 2026: Strategic Imperatives for Decision Makers
Executive synopsis
As PF3 transitions from a niche specialty gas to a strategic precursor for advanced manufacturing, 2026 represents a pivot point for procurement, manufacturing, and investment strategies. PW Consulting’s new market study — spanning 2020–2025 historicals and a 2026–2032 forecast horizon — synthesizes primary interviews, supplier due-diligence, and scenario-based financial modeling to equip senior executives with operationally actionable guidance. Our analysis projects the global PF3 market at approximately USD 72.45 Million in 2025, rising to USD 79.53 Million in 2026 and reaching roughly USD 120.19 Million by 2032, reflecting a 7.5% compound annual growth rate across the forecast period.
Phosphorus Trifluoride (PF3) Market
Why 2026 is a strategic inflection year
-
Policy and tariff dynamics in 2025 have materially altered cross-border flows for specialty chemicals, introducing new landed-cost regimes and time-to-market constraints that will crystallize in procurement contracts signed in 2026.
Phosphorus Trifluoride (PF3) Market -
Raw material volatility during 2025 amplified upstream cost exposure for halogen and phosphorus chemistries; firms that formalize mitigation strategies in 2026 will capture meaningful margin resilience through 2032.
Phosphorus Trifluoride (PF3) Market -
Consolidation among high-purity suppliers, paired with rising demand from semiconductor and specialty chemical sectors, is reshaping bargaining power—an evolution that necessitates differentiated sourcing and qualification roadmaps.
How this report creates immediate strategic value
PW Consulting’s PF3 Market Report is purpose-built for senior leaders and procurement heads who must reconcile supply security with competitive cost structures. Rather than abstract forecasts, the report offers:
-
Scenario-based cost and supply models that translate macro drivers into P&L and working-capital impacts over 18–60 month horizons.
-
Supplier scorecards with operational readiness indicators (purity grades, packaging innovations, global distribution footprints, and contingency capacities) that map directly to qualification timelines for semiconductor and industrial customers.
-
Tariff and trade-policy playbooks that quantify landed-cost delta under prevailing and stress-case tariff regimes and prescribe contracting clauses and local value options to mitigate 25–50% duty shocks.
-
Raw-material sensitivity analyses demonstrating the profit and cost thresholds at which alternative chemistries or in-house synthesis become economically attractive.
-
Implementation roadmaps for dual-sourcing, strategic inventory positioning, and supplier collaboration agreements tailored to both high-purity semiconductor requirements and larger-volume industrial uses.
Market dynamics — growth, concentration, and demand drivers
The PF3 market is expanding steadily: from roughly USD 52.14 Million in 2020 to approximately USD 72.45 Million in 2025, with our base-case projection reaching about USD 120.19 Million by 2032. Demand growth is underpinned by continued adoption in semiconductor doping and related etch/CVD processes, alongside a steady uptake in specialty chemical synthesis where PF3’s reactivity profile is valued. Concentration metrics indicate a market with moderate-to-high supplier concentration: the top three firms account for a majority share of global supply, while the top five capture nearly four-fifths of the market—conditions that amplify the commercial consequences of supply disruptions and quality differentials.
Supply-side anatomy and competitive positioning
Our competitive analysis identifies discrete strategic archetypes among incumbent suppliers:
-
Tier-one high-purity specialists who focus on semiconductor-grade PF3 and integrated customer support (including packaging innovations and trace-impurity guarantees). These players command premium pricing but reduce qualification risk for advanced fabs.
-
Large industrial gas suppliers that leverage scale and distribution networks to serve bulk and general industrial demand, offering robustness in logistics and cylinder management.
-
Regional manufacturers that provide competitive pricing and flexible packaging options for laboratory and process-chemistry customers, but may vary on global lead-times and certification scopes.
Key firms profiled in the report include a major U.S.-based high-purity supplier known for optimized cylinder systems and global continuity protocols; multinational industrial-gas providers with breadth of specialty gas offerings; and a set of smaller-volume and China-based manufacturers that compete on price and packaging flexibility. Each profile includes an assessment of production technology, quality-certification posture, and likely strategic moves under stress scenarios (e.g., feedstock price shocks or tariff escalations).
Operational and commercial risks — what to watch in 2026
-
Raw-material inflation: 2025 saw a pronounced spike in feedstock costs that materially increased production expense for fluorinated and phosphorus inputs. Buyers must stress-test supplier quotations against volatility scenarios and insist on transparent cost-builds.
-
Trade and tariff exposure: Recent policy changes have elevated duties on specialty chemicals and semiconductor inputs in key markets, increasing landed costs and incentivizing nearshoring or local manufacturing partnerships.
-
Concentration and supplier single points of failure: With a concentrated supply base, any capacity outage in a top supplier can create multi-week shocks in availability—mitigation options include staggered inventory strategies, qualified secondary suppliers, and contractual service-level commitments.
-
Quality and packaging requirements: For advanced-node semiconductor processes, packaging integrity and ultra-low impurity profiles are non-negotiable. Buyers should align procurement KPIs with wafer-yield impact rather than per-unit gas price alone.
Practical recommendations for 2026 decision-making
-
Re-baseline TCO models: Replace spot-price heuristics with scenario-driven total-cost-of-ownership frameworks that integrate tariff risk, freight corridors, and purity-related yield impacts.
-
Adopt a graded qualification pipeline: Tier suppliers by capability and role—primary partners for high-purity needs, regional sources for buffer capacity, and long-term agreements with performance-based clauses.
-
Secure feedstock levers: Where upstream feedstock volatility is material, consider co-investment, offtake agreements, or localized feedstock contracts to stabilize input costs.
-
Insist on contractual transparency: Include audit rights, change-of-control clauses, and force-majeure definitions that reflect modern trade and geopolitical risk realities.
-
Evaluate strategic inventory buffers: For mission-critical manufacturing sequences, a calibrated strategic stock can neutralize 4–8 week supply interruptions without excessive working-capital drag.
What PW Consulting’s report delivers — and what we intentionally withhold here
This article highlights the analytical backbone and the types of actionable outputs clients will receive. The full report contains granular models, downloadable supplier scorecards, forecast tables by year (2026–2032), sensitivity matrices, and executable contract templates. In keeping with our “trailer” approach, we have intentionally withheld detailed regional and application-level percentage splits and certain commercially sensitive cost tables in this summary. Those consolidated data and proprietary segmentation models are available in the full report package and via our interactive client portal.
Next steps for executives
For procurement directors, product-line leaders, and corporate strategists preparing budgets and qualification plans in 2026, the choices made this year will determine resilience and margin trajectory for the rest of the decade. PW Consulting offers tailored briefings that map our forecast to your supply base, TCO implications, and recommended sourcing playbooks. Contact our PF3 market team to schedule a confidential strategy session and to obtain the full dataset, supplier scorecards, and the scenario models referenced in this brief.
PW Consulting’s PF3 Market Report is the practical intelligence toolkit for organizations that need more than forecasts: it delivers operationally grounded counsel that converts market insight into defensible commercial action.
For detailed analysis of this topic, please visit the official page: Phosphorus Trifluoride (PF3) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com