

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Enzymes for Fuel Ethanol Market to Grow at 6.3% CAGR — From USD 1,418.7 Million in 2025 to USD 2,175.8 Million by 2032; Amylases Dominate as CR3 Hits 75.4%

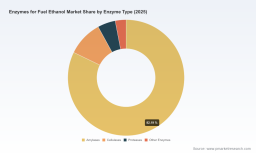
Enzymes for Fuel Ethanol Market: Strategic Imperatives for 2026 — A PW Consulting Executive Brief
The industrial enzyme market serving fuel ethanol producers is entering a phase of tactical consolidation and technical maturation. Our new Enzymes For Fuel Ethanol Market report — covering 2020–2025 historical performance and providing a 2026–2032 forecast — quantifies the commercial runway and translates regulatory shifts into operational choices. In aggregate terms, the market is measured in the low‑billion USD range today and is expected to grow at a mid‑single‑digit CAGR (6.3%) through the 2026–2032 forecast window, underscoring a durable expansion driven by both incremental yield gains and nascent cellulosic pathways. This brief summarizes the report’s strategic value for decision makers preparing for 2026, while reserving the detailed, segment‑level tables and models for the full report.
Enzymes For Fuel Ethanol Market
Why 2026 is a Strategic Inflection Point
-
Policy coupling with enzyme innovation: Recent regulatory updates in the U.S. (notably EPA guidance enabling co‑production of D3 cellulosic RINs alongside starch ethanol using kernel fiber technologies) have altered the revenue calculus for enzyme investments. Producers capturing D3 value streams can materially improve returns on enzyme optimization and retrofit spend.
Enzymes For Fuel Ethanol Market -
Commercial scale and efficiency gains: Global fuel ethanol production and U.S. throughput remain elevated, and enzymatic process efficiency has advanced — for example, operational conversion peaks have been reported in industry data in 2025. That creates tangible per‑unit value from enzyme performance improvements without necessarily increasing feedstock use.
Enzymes For Fuel Ethanol Market -
Consolidation and supplier concentration: The enzyme supplier base is consolidating; a small number of global players account for the majority of supply. Recent strategic transactions and alliance changes are re‑shaping bargaining dynamics and access to next‑generation enzyme platforms.
-
Plant modernization and incremental tech: New plant‑level programs that increase capacity and energy efficiency without wholesale equipment replacement are making enzyme upgrades a higher‑return, lower‑friction pathway to near‑term margin improvement.
What the PW Consulting Report Delivers (Practical, Executable Content)
Our report is structured as a field manual for commercial, technical and corporate strategy teams preparing 2026 budgets and partnerships. Key deliverables include:
-
Market sizing & outlook: A consolidated market model (historical and forecast) with scenario variants that isolate the incremental impact of cellulosic co‑processing, RIN pricing sensitivity, and low‑carbon tax credits on enzyme demand and supplier revenue.
-
Demand driver decomposition: A granular hypothesis framework mapping policy, blending mandates, feedstock supply, and conversion efficiency to enzyme consumption and spend — presented as prescriptive drivers rather than raw lists of segment figures.
-
Supply‑chain mapping and supplier playbook: Detailed supplier profiles, capability matrices, and commercial negotiation levers, plus a supplier risk heatmap tailored for tier‑1 and regional ethanol producers.
-
Competitive benchmarking and concentration analysis: Independent benchmarking of enzyme classes and vendor platforms, combined with concentration metrics that highlight where supplier power is greatest and where negotiating leverage can be established.
-
Plant‑level techno‑economic models: “What‑if” models that link enzyme dosing, performance deltas, and retrofit choices to per‑gallon economics and payback periods. These models are configurable to user inputs (plant size, feedstock mix, local incentives).
-
M&A and partnership roadmap: Target identification framework for acquisitions, licensing, and co‑development agreements focused on enzyme IP, cellulase capability and regional distribution synergies.
-
Procurement playbooks and contracting templates: Practical clauses and KPI constructs for long‑term enzyme supply agreements, including risk sharing on performance guarantees and joint R&D milestones.
To preserve commercial value for our subscribers, the report deliberately refrains from publishing the full segment‑level tables in public summaries. The full dataset, supplier scorecards and downloadable financial models are available through the official report portal.
Competitive Landscape — Who Matters and Why
The market dynamics are shaped by a mix of global enzyme champions, specialized biotech innovators and regional formulators. Three facts matter for strategy:
-
High concentration at the top: Market concentration metrics show that the leading few firms account for a dominant share of commercial enzyme volumes and technology licensing. This creates both supply risk and opportunity for differentiated procurement strategies.
-
Complementary specialists: A set of smaller, agile firms and engineered‑enzyme developers deliver critical capability in cellulosic conversion and bespoke formulations — functions that larger incumbents either acquire or partner to access.
-
Recent consolidation events: Strategic transactions in 2025 have reinforced the market position of major biosolution providers and altered alliance networks that were once stable; these shifts have immediate implications for access to proprietary enzyme platforms and co‑development pathways.
Representative vendor positioning (high‑level): Novonesis (formerly Novozymes) remains a platform leader with broad alpha‑amylase, glucoamylase and cellulase portfolios optimized for conventional and advanced ethanol pathways. Large diversified bioscience firms (including divisions now integrated within ingredient conglomerates) offer scale, global distribution and integrated fermentation solutions. Engineered enzyme companies and specialized cellulase developers provide the performance delta for cellulosic and kernel‑fiber conversions. Regional formulators and distillery enzyme suppliers compete on cost and service in local markets.
Strategic Plays for 2026 — Concrete Actions Leaders Should Consider
-
Re‑negotiate supply agreements with performance‑based KPIs: Move from fixed‑price, volume‑only contracts to deals that share upside from yield improvements and lower carbon intensity outcomes.
-
Invest selectively in co‑development: Co‑fund enzyme R&D with a vendor to secure first‑right access to cellulosic or low‑CI enzyme blends that unlock D3 RINs and tax credit benefits.
-
Run plant‑level pilots now: Use the report’s techno‑economic models to justify short pilots that can validate per‑gallon uplift and the payback on enzyme upgrades within a single production season.
-
Pursue portfolio hedging via vendor diversification and regional sourcing strategies to reduce exposure to concentrated supplier risk.
-
Align procurement with carbon‑credit strategies: Enzyme choices influence lifecycle carbon intensity; integrating enzyme performance into CI accounting enhances access to credits and clean fuel incentives.
-
Scan the M&A market for bolt‑on enzyme specialists: Acquiring a niche cellulase or engineered‑enzyme provider can be an effective way to internalize margin and control co‑processing economics.
How PW Consulting’s Analysis Supports Boardroom Decisions
Executives will appreciate that our deliverables are organized to answer three questions in the 90‑day planning cycle:
-
“Where should we allocate capital between enzyme upgrades, plant retrofits and feedstock diversification?” — answered through our return profiles and sensitivity matrices.
-
“Which suppliers should we prioritize for long‑term partnerships or acquisition?” — answered through our supplier capability maps, concentration metrics and M&A filters.
-
“What is the regulatory upside or downside to each pathway?” — answered through scenario work that quantifies the effects of RINs, clean fuel credits and likely regulatory trajectories.
Recent Market Signals to Watch in Early 2026
-
Strategic M&A and alliance shifts among top enzyme vendors are continuing to re‑shape channel relationships and access to proprietary platforms.
-
Plant modernization programs that increase capacity without major CAPEX are raising the ROI for enzyme optimization projects.
-
Regulatory mechanisms that monetize low‑carbon ethanol (including D3 RINs and modified clean fuel credits) are now material line items in project economics and should be incorporated into bid modeling and contract negotiations.
Next Steps — How to Use This Intelligence
For commercial teams, the immediate action is to run one or two plant‑level pilots using the scenarios in our downloadable models and to open strategic talks with at least two different enzyme platforms (one incumbent, one engineered specialist). For corporate development and strategy teams, the priority is to map a short‑list of acquisition targets and co‑development partners informed by the supplier capability matrices in the report.
PW Consulting’s Enzymes For Fuel Ethanol Market report provides the models, vendor scorecards and contracting templates to convert these strategic moves into measurable margin and carbon outcomes. We intentionally limit segment‑level public disclosure here to preserve the commercial advantage our subscribers gain from detailed breakdowns and the full suite of financial models.
Accessing the Full Report
Decision makers seeking the granular datasets, downloadable Excel models, vendor scorecards, and the full competitive annex should visit the official report page to request access. The full package includes the proprietary plant TEA templates and negotiation playbooks you will need to convert the market’s projected mid‑single‑digit CAGR into demonstrable per‑gallon gains in 2026.
For detailed analysis of this topic, please visit the official page: Enzymes For Fuel Ethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com