

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Robust 6.42% CAGR for Automated Side‑Load Garbage Trucks Market (2026–2032)

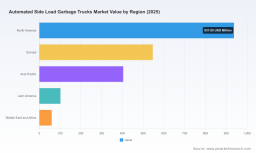
Automated Side Load Garbage Trucks Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
PW Consulting’s new market study on Automated Side Load Garbage Trucks offers a forward-looking, actionable playbook tailored to procurement teams, fleet operators, OEMs, and private capital evaluating opportunities in 2026. The market has moved from an estimated USD 1,502.4 Million in 2020 to roughly USD 2,050 Million in 2025, and our modeling projects continued expansion through the forecast horizon (2026–2032), reaching approximately USD 3,168.95 Million by 2032 at a compound annual growth rate (CAGR) of 6.42%. These headline dynamics frame a market that is maturing—but still in a phase where timely strategic choices determine winners and losers.
Automated Side Load Garbage Trucks Market
Why this report matters for decisions in 2026
-
Procurement windows are tightening: municipalities and large waste contractors that begin negotiations in 2026 will lock in fleet profiles that affect TCO and regulatory compliance for a decade. The report highlights when to pilot, scale, or defer purchases based on scenario-driven TCO curves.
Automated Side Load Garbage Trucks Market -
Electrification and low-emission fuel pathways are no longer optional. Regulatory pressures in North America and Europe, together with emerging local mandates, make zero- and low-emission compatibility a strategic procurement filter. Our analysis quantifies payback sensitivities under realistic duty cycles and energy-cost scenarios.
Automated Side Load Garbage Trucks Market -
Competition is concentrated enough to matter: the top-tier manufacturers collectively capture meaningful share, shaping OEM bargaining power, aftermarket availability, and innovation diffusion. Our concentration metrics and vendor benchmarking help buyers balance performance, risk, and future-serviceability.
-
Safety and compliance are design drivers. OSHA-style operator-safety requirements and EU Machinery Directive obligations are changing specs for automation, sensors, and operator interfaces—an important procurement checklist for 2026 tenders.
What the PW Consulting report delivers — practical, decision-ready content
-
Integrated financial tools: configurable TCO models (capital, energy/fuel, maintenance, residuals), lease vs. buy calculators, and capex/opex break-even analyses tailored to municipal and private contractor use cases.
-
Procurement playbook: bid language templates, performance-based contracting structures, warranty & service-level frameworks, and evaluation scorecards that operationalize safety and emissions requirements.
-
Pilot & rollout blueprints: step-by-step guidance for designing pilots (sample KPIs, duration, route-mix selection), scale-up triggers, and retrofit vs. replacement decision trees.
-
Vendor & supplier diligence packs: comparative profiles, strengths & weaknesses, interoperability checklists (chassis compatibility, battery & hydraulic interfaces), and a supplier risk heat map to align procurement timelines with lead times and capacity constraints.
-
Scenario planning & sensitivity analyses: multiple market and regulatory scenarios through 2032, with stress-testing on energy prices, battery cost curves, and labor-cost trajectories to identify robust strategies across plausible futures.
-
Digital transition roadmap: practical steps to deploy telematics, route-optimization, predictive maintenance, and data governance—topics that materially affect operating costs and uptime for automated side loaders.
Competitive landscape — who’s shaping product and service expectations
The automated side load space is characterized by a mix of long-standing specialists and bodybuilders with deep refuse experience. Market concentration metrics indicate the three largest vendors control a substantial proportion of the market and the top five extend that dominance further; together these dynamics create both scale advantages and vetting challenges for buyers who want optionality without service risk.
-
Heil Environmental (Chattanooga, TN) — Strength: breadth of continuous-pack and rapid-pack automated side loaders, plus early electric-body variants. Strategic implication: strong R&D pipeline in electrified collection bodies, attractive to fleets prioritizing low-emission retrofits and new EV chassis integration.
-
McNeilus Truck and Manufacturing (Dodge Center, MN) — Strength: versatility and arm-design innovations aimed at tighter residential environments and hybrid operation models. Strategic implication: a go-to for contractors needing mixed-mode fleets and robust dealer support networks.
-
Labrie Enviroquip Group (Quebec) — Strength: flexible manual/semi/fully automated series tailored to North American route diversity. Strategic implication: attractive for markets that require interoperability across collection modes and varied labor models.
-
New Way Trucks (Scottdale, IA) — Strength: high-lift capacity models and under-CDL options. Strategic implication: options for operators focused on payload optimization and regulatory payload thresholds.
-
Amrep (California) — Strength: durable, wear-resistant body construction and breadth across body types. Strategic implication: buyers with harsh duty cycles will value lifecycle durability and lower MRO frequency.
-
Curbtender Inc. — Strength: deep legacy expertise as the originator of commercial automated side loaders. Strategic implication: strong brand trust and incremental product refinements make it a safe choice for conservative fleets.
-
KANN Manufacturing — Strength: high compaction bodies and multiple eject/tip configurations. Strategic implication: suit fleet strategies emphasizing compaction efficiency and route density optimization.
Our vendor benchmarking goes beyond feature lists to assess dealer footprints, aftermarket lead times, software & telematics compatibility, and upgrade pathways—data points that determine operational resilience in multi-year fleet deployments.
Regulatory and technical dynamics reshaping product choice
-
Emission regulations are accelerating adoption of electric and alternative-fuel collection vehicles. The most forward-looking procurement strategies include technology-agnostic pathways that preserve options for battery, CNG/LNG, or hybrid integrations depending on local energy economics.
-
Safety standards require electronic anti-collision systems, operator-presence detection, and emergency override capabilities; these features are de facto inclusion criteria for modern automated side loaders in many jurisdictions.
-
Design norms—reach, lift capacity, compaction metrics—are converging, but differences in hydraulic architecture, arm kinematics, and independent battery systems (for electric bodies) remain key competitive differentiators. Our technical appendix maps these design choices to route archetypes and maintenance regimes.
Key risks and operational headwinds to model in 2026
-
Supply chain volatility: lead times for chassis, semiconductors, and advanced materials can disrupt scheduled rollouts—contingency sourcing and staged delivery clauses are now essential contract language.
-
Battery and energy-price uncertainty: electrification payback depends on local electricity pricing, charging infrastructure, and evolving battery costs—our scenarios quantify financial sensitivity so buyers can hedge procurement timing.
-
Workforce and training: automation changes crew roles and safety responsibilities; successful rollouts depend on change management, operator training programs, and adoption incentives.
-
Residual value and secondary markets: resale assumptions materially influence lease structures and TCO; we provide a conservative framework for residual-value stress testing.
Recommended strategic moves for stakeholders planning in 2026
-
For municipal fleets: pilot electrified automated side loaders on representative routes in 2026, pair pilots with aggressive measurement of uptime, energy usage, and operator feedback, and use procurements that include supplier performance penalties tied to uptime and emissions targets.
-
For private contractors: negotiate flexible purchasing windows and service guarantees to preserve fleet agility; prefer vendors with proven telematics ecosystems to extract route-efficiency gains quickly.
-
For OEMs and suppliers: prioritize modular body designs that decouple collection systems from chassis powertrain choices, reducing buyer friction and enabling faster market adoption across multiple fuel strategies.
-
For investors and financiers: structure financing to recognize the multi-year emissions regulatory runway and the potential for higher-than-expected residual values in regions with accelerated zero-emission mandates.
How to use this preview
This announcement is a strategic extract from PW Consulting’s full Automated Side Load Garbage Trucks Market report. It highlights the macro trajectory, competitive dynamics, regulatory imperatives, and the practical toolkits buyers and suppliers need when making 2026 decisions. Detailed segmentation data and granular vendor scoring are intentionally withheld from this public preview to preserve the tactical value of the full deliverable.
Next steps — where to get the full intelligence
If your 2026 capital and operational plans include automated side loaders, the full PW Consulting report provides the detailed regional, propulsion-type, and chassis-capacity splits, the complete vendor scorecard, downloadable TCO models, procurement templates, and scenario-specific rollout calendars. Contact PW Consulting to obtain the complete report and arrange a tailored briefing where we will map the findings directly onto your fleet, budget, and regulatory context.
For detailed analysis of this topic, please visit the official page: Automated Side Load Garbage Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com