

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts High Purity L-Glutamine Market to Expand at a 7.91% CAGR Through 2032

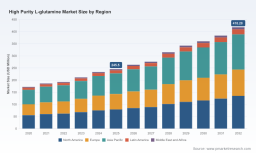
High Purity L‑Glutamine Market: Strategic Signals for 2026 Decision‑Makers
PW Consulting’s latest market study on High Purity L‑Glutamine arrives at a pivotal moment for pharmaceutical, biomanufacturing and nutraceutical executives preparing strategies for 2026. Our analysis synthesizes five years of historical performance, vetted supplier intelligence and forward‑looking scenario work to deliver actionable guidance for procurement, manufacturing, M&A and regulatory engagement. The market-sized narrative is unambiguous: between 2020 and 2025 the addressable market expanded from USD 172.45 Million to USD 245.50 Million, and our baseline forecast anticipates growth to USD 418.28 Million by 2032 — an implied 7.91% CAGR across the 2026–2032 forecast window. This trajectory carries clear implications for capacity planning, quality assurance investments and trade strategy over the next 24 months.
High Purity L Glutamine Market
Why this study matters for 2026 planning
-
Durable demand growth. The compound expansion we model reflects converging demand vectors — increased use in cell culture and biologics manufacturing, the steady maturation of clinical nutrition applications, and continuing growth in high‑margin nutraceuticals. Each vector has different procurement and quality requirements; our report translates aggregate growth into decision‑grade implications for production scheduling and supplier selection.
High Purity L Glutamine Market -
Supply concentration and competitive dynamics. The market is moderately consolidated: the top three players account for a meaningful share of supply and the top five capture well over half the market’s capacity footprint. That concentration matters for buyers negotiating long‑term offtakes and for investors evaluating consolidation strategies.
High Purity L Glutamine Market -
Input and process risk. Fermentation remains the dominant production route globally, with agricultural feedstocks driving upstream volatility. Recent commodity movements and inventory cycles have immediate pass‑through effects on producer margins and spot availability — dynamics that procurement teams must incorporate into 2026 budget cycles.
-
Regulatory and trade sensitivity. Emerging trade measures and investigations are reshaping how sponsors and suppliers structure sourcing and certification strategies. Our report maps these regulatory levers and provides playbooks for minimizing disruption to drug substance and excipient supply.
Core findings (high level)
-
Market scale and growth: From USD 172.45 Million in 2020 to USD 245.50 Million in 2025, with a forecast that reaches USD 418.28 Million by 2032 under our central case (7.91% CAGR for 2026–2032). This pace justifies near‑term capacity investments, especially where high‑purity or low‑impurity grades command premium pricing and tight qualification cycles.
-
Competitive concentration: Measured concentration ratios indicate a market where a limited set of global and regional specialists wield meaningful influence over quality standards and lead times. This dynamic elevates the value of validated supply relationships and preemptive qualification of second‑source manufacturers.
-
Production economics: Fermentation‑based manufacturing dominates the technology stack; upstream feedstock fluctuations and inventory cycles have already produced localized price movements. Producers with integrated upstream sourcing or flexible fermentation platforms enjoy faster margin recovery in volatile cycles.
-
Regulatory risk: Trade policy developments, including investigations into pharmaceutical imports and potential tariff actions, create an overlay of uncertainty that can affect lead times, landed costs and contractual terms for 2026 procurement. Companies should adopt dual sourcing and tariff mitigation approaches now.
What the report contains — pragmatic deliverables
-
Validated market sizing and trend models: annualized market figures from 2020 through 2032, plus sensitivity scenarios for demand shocks, price pass‑through and regulatory events.
-
Commercial playbooks: step‑by‑step procedures for supplier qualification, long‑term contract design, and price indexation mechanisms tailored to fermentation feedstock volatility.
-
Supply chain heatmaps and capacity schedules: strategic maps showing where high‑purity capacity sits, lead‑time contours, and where near‑term expansions are most likely to relieve bottlenecks.
-
Regulatory and tariff matrix: an executive primer on current investigations and trade measures, with recommended action checklists for importers, exporters and in‑country manufacturers.
-
Vendor scorecards and risk dashboards: qualitative and quantitative grading of active suppliers across product quality, certification footprint, scale, low‑endotoxin capability, geographic flexibility and commercial transparency.
-
M&A and partnership targets: a prioritized shortlist for strategic investors looking to buy capacity, secure specialized grades or accelerate vertical integration — supported by valuation heuristics and integration risk assessments.
Competitive landscape: who matters and why
Our supplier analysis combines on‑site audits, regulatory filings and open‑source intelligence to profile established global players and regionally important manufacturers. Key competitive archetypes are evident:
-
Global fermentation leaders with broad pharmacopeial filings — companies that combine scale, multiple pharmacopeial certifications (e.g., USDMF, CEP, JP/EP) and deep experience supplying cell‑culture and injectable excipient markets. These suppliers set quality benchmarks and are core partners for multinational biopharma customers.
-
Specialist cGMP producers focused on parenteral/excipient quality — manufacturers who emphasize low‑endotoxin, low‑metals specifications and who often serve niche biologics customers with stringent sterile‑grade requirements.
-
Large‑scale commodity producers with growing high‑purity capability — producers that historically served food and feed markets but are upgrading processes and certifications to capture higher‑margin pharmaceutical and nutraceutical demand.
-
Regional API and nutraceutical suppliers — firms that provide rapid local access and competitive pricing but may require additional qualification for global pharmaceutical supply chains.
Representative firms we examine in depth include established multinationals known for pharmacopeial filings and robust quality systems, European specialty chemical players with strong pharmaceutical credentials, and a cohort of Asian producers scaling capacity and certification footprints. Recent capacity announcements and product rollouts by several of these firms underscore the market’s bifurcated future: both scaling and differentiation will matter.
Recent market signals and implications
-
Capacity moves: Multiple producers have accelerated expansion programs, particularly those targeting export markets. These moves will moderate short‑term tightness but will also intensify competition on price for standard grades while elevating premium grades as a differentiated margin pool.
-
Feedstock dynamics: The primary upstream feedstock complex has shown inventory‑driven price pressure recently; a modest price retrenchment was observed in early 2026. Buyers should not assume this is permanent — our scenarios model both inventory cycles and production ramp‑ups.
-
Regulatory developments: Governmental investigations and tariff measures under review in key markets have introduced an overlay of policy risk. Firms with flexible manufacturing footprints and validated domestic suppliers can translate regulatory uncertainty into competitive advantage.
Strategic recommendations for 2026
-
Operationalize dual sourcing for critical grades. Prioritize qualification of one global leader plus a regional backup that meets pharmacopeial and supplier‑audit requirements.
-
Accelerate quality investment where product is margin critical. Upgrading testing, ensuring low‑endotoxin processes and securing documentation packages will shorten qualification cycles and command price premiums.
-
Hedge feedstock exposure. Negotiate index‑linked contracts to mitigate upstream glucose/corn‑starch price swings and evaluate limited hedging instruments for high‑volume purchases.
-
Engage on trade policy. Proactively participate in industry comment periods and develop contingency plans for tariff scenarios — including managed onshoring or toll‑manufacturing arrangements—to preserve market access.
-
Pursue selective M&A and partnerships. The market reward will be greatest for buyers who acquire certified capacity or capability to produce low‑impurity, low‑endotoxin grades. Our report ranks targets by strategic fit and integration complexity.
How PW Consulting’s report supports implementation
Beyond the narrative, the deliverables include granular models, downloadable vendor scorecards, stepwise supplier qualification templates and scenario planning tools that procurement, regulatory and corporate development teams can operationalize immediately. The study is purpose‑built to convert market intelligence into measurable actions for 2026 budgeting and contract cycles.
Next steps and where to find the full intelligence
This press briefing intentionally highlights the strategic signal and omits the detailed segmentation tables and proprietary valuation models that underpin our conclusions. PW Consulting’s complete High Purity L‑Glutamine Market report contains the full set of breakouts by product grade, application and region, vendor‑level data, and our interactive forecast model. For teams preparing 2026 procurement strategies, regulatory mitigation plans or M&A diligence, the full dataset and the executive playbook are available through PW Consulting’s report portal.
To gain access to the comprehensive data tables, supplier scorecards and scenario models that we used to derive the growth trajectory and recommendations above, please visit our report page or contact PW Consulting’s industry desk. Our analysts can also provide tailored briefings for leadership teams with bespoke scenario runs and supplier‑specific risk assessments.
For detailed analysis of this topic, please visit the official page: High Purity L Glutamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com