

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polymer Gel Market Poised to Grow at a 7.5% CAGR as Hydrogels Drive Demand

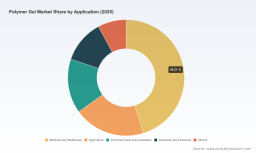
Polymer Gel Market 2026 Strategic Brief: Actionable Intelligence for Boardrooms and Business Units
PW Consulting’s latest market research — the Polymer Gel Market Report (base year 2025, forecast 2026–2032) — synthesizes commercial, technical and regulatory intelligence into a single operational playbook designed to inform capital allocation, product strategy, and supply‑chain resilience decisions in 2026. This executive briefing highlights the report’s strategic value and the practical, decision‑grade outputs senior teams will use to accelerate growth while managing emerging risks. Consider this a trailer: we surface the critical directional findings and the implications for corporate strategy, while the underlying segment tables, company revenue splits and full scenario matrices remain available in the full report.
Polymer Gel Market
Why this report matters for decisions in 2026
-
Market trajectory now requires active management, not passive forecasting. The polymer gel market continues its multi‑year expansion, transitioning from a post‑pandemic recovery phase into a structurally growing market driven by healthcare, high‑value industrial applications and specialty consumer uses.
Polymer Gel Market -
Our model projects growth from a global market size of approximately USD 20.5 billion in 2025 to roughly USD 34.0 billion by 2032 — a compound annual growth rate (CAGR) of 7.5% across the forecast period. That pace creates both scale opportunities and near‑term capacity stress points for producers and buyers.
Polymer Gel Market -
Decision windows in 2026 are compressed. Capital projects that are initiated this year are likely to come online during the most dynamic years of demand growth; regulatory and feedstock headwinds require preemptive mitigation steps if firms want to avoid margin erosion or missed market share.
Topline market forces to prioritize
-
Demand polarization: Higher‑value clinical and specialty uses (advanced wound care, medical hydrogels, battery and thermal insulation segments) are driving premiumization, while cost‑sensitive channels remain tied to volatile commodity cycles. This creates a bifurcated competitive field where product differentiation and cost leadership can both be winners if executed with clarity.
-
Feedstock volatility and supply risk: Upstream acrylic‑acid markets moved from a period of softening in late 2025 to renewed price pressure in early 2026. The pattern is one of elevated volatility — not stable inflation — which means procurement strategies must incorporate dynamic hedging, dual‑sourcing and strategic inventory to avoid production interruptions or margin swings.
-
Regulatory tightening: New restrictions on intentionally added microplastics in Europe and anticipated PFAS restrictions are already shaping formulation choices, supplier selection and innovation roadmaps. Compliance is becoming a differentiator; companies slow to adapt will face business continuity and market‑access headwinds in key geographies.
-
Trade policy and localized capacity: Recent tariff actions have increased the effective cost of certain polymer imports into the U.S., accelerating regionalization of supply chains and making local capacity investments more attractive despite higher unit capex in some geographies.
Competitive landscape — what the lead players are doing
The sector is moderately consolidated: the top three players account for roughly one third of market share while the top five approach half of the market. That concentration profile supports both selective consolidation and differentiated niche plays.
-
BASF SE: Recent capital investments underscore an emphasis on efficiency and footprint optimization. A notable upgrade to the Freeport, Texas SAP facility illustrates the strategy: improve asset productivity, reduce logistics complexity and tighten lifecycle emissions. Expect BASF to continue deploying targeted capex rather than broad greenfield expansion in mature markets.
-
Evonik Industries AG: Product engineering is their lever. New launches focused on antimicrobial, clinically validated wound dressings signal a move up the value chain — prioritizing performance specifications that are difficult to replicate at scale and attractive to healthcare OEMs.
-
Nippon Shokubai, Sumitomo Seika and other Asian majors: These firms are expanding regional capacity and piloting next‑generation SAP and hydrogel chemistries. Their playbook is dual: secure cost‑competitive feedstock and move quickly to serve growing regional hygiene and medical markets.
-
Diversified chemical players and specialty suppliers (Dow, LG Chem, Ashland, Cabot, SNF, Chemtex, Saudi Amiantit): Each is positioning around complementary strengths — from acrylic chemistries and additives to aerogel thermal systems and water‑treatment gels. Expect increased strategic partnerships and selective vertical integration across the value chain.
-
Near‑term signals to watch: capacity upgrades, pilot plant inaugurations, and product launches tied to clinical claims or regulatory compliance. These are the fastest indicators of where premiums and bottlenecks will emerge.
Strategic implications and prioritized actions for 2026
-
Re‑tool margin management for volatility: Implement a price‑pass‑through framework linked to acrylic‑acid indices and build a procurement dashboard that quantifies margin exposure at SKU level. For lead times exceeding eight months, enforce contractual clauses that permit indexation or establish shared risk mechanisms with customers.
-
Fast‑track compliance‑driven reformulation: Run a 90‑day program to catalogue all intentionally added polymer microparticles and any fluorinated additives in your portfolio. Where exposure exists, prioritize substitution roadmaps for formulations subject to EU microplastics and looming PFAS restrictions — especially for exported product lines.
-
Reassess capex under scenario matrices: Use a three‑scenario framework (Base, Upside with rapid premium adoption, Downside with prolonged feedstock stress) to size capacity decisions. Smaller, modular lines and pilot plants (rather than single large greenfields) can preserve optionality and reduce time to market for specialty grades.
-
Build a two‑track innovation funnel: (1) near‑term cost and compliance optimizations for existing product ranges; (2) longer‑term R&D for high‑margin, performance‑differentiated gels (medical, thermal, battery systems). Link both to discrete commercialization KPIs and joint‑development agreements with OEM partners.
-
Prioritize M&A and partnership targets that fill capability gaps: Given the moderate market concentration, bolt‑on acquisitions in specialty niches or regional feedstock advantages can accelerate scale. The report includes a due‑diligence checklist to validate synergies across technology, regulatory readiness and logistics.
-
Operationalize sustainability as a commercial advantage: Quantify carbon and material footprint for product lines; then map reduction levers that also create cost or margin benefits (e.g., solvent recovery, waste minimization, circular polymer initiatives).
What the PW Consulting report delivers — operational contents
-
Dynamic market model: A stress‑tested demand model (2020–2032) with scenario toggles for feedstock pricing, regulatory shocks and end‑market adoption curves.
-
Go‑to‑market playbooks: Segmented GTM strategies for medical OEMs, hygiene brands, agriculture and industrial buyers — including commercial templates, margin engineering worksheets and supplier scorecards.
-
Supply‑chain stress tests: Node‑level simulations that quantify inventory, lead‑time and tariff exposures by routing and supplier selection.
-
Regulatory and materials tracker: An updatable register covering microplastics, PFAS, and trade measures with impact quantification and compliance timelines.
-
M&A and JV toolkit: Screening criteria, valuation adjustment checklists for regulatory liabilities and operational integration playbooks.
-
R&D prioritization matrix: Technical gating criteria, commercialization timelines and estimated capex for pilot‑to‑scale transitions.
-
Case studies and company dossiers: Competitive summaries and strategic implications for major players, including recent capacity upgrades, product launches and regional expansions.
How senior teams should use this intelligence in 2026
-
Boardrooms: Use the report’s scenario outputs to validate capital allocation requests and to stress transfer pricing, tariff impacts and regulatory compliance costs across business units.
-
Corporate development teams: Shortlist targets using our M&A filters and run rapid target screens in the report’s analytics workbook to size synergy capture and downside risk.
-
Supply‑chain and procurement: Adopt the procurement dashboard and supplier scorecards to implement dual sourcing, index‑linked contracts and contingency inventory buffers.
-
R&D and product management: Implement the two‑track funnel and prioritize formulations that reduce regulatory and feedstock exposure while expanding into premium clinical and specialty markets.
Closing — the 2026 decision point
The polymer gel market sits at an inflection: attractive compound growth and premium end‑market opportunities are counterbalanced by upstream volatility and regulatory tightening. Firms that align capital deployment with targeted product differentiation, lock in resilient feedstock strategies and accelerate compliance‑led innovation will convert market growth into sustainable margin expansion.
PW Consulting’s Polymer Gel Market Report is structured to convert uncertainty into executable actions. For access to the full data tables, granular segment forecasts, company‑level revenue splits and the downloadable decision‑toolkit, please refer to the full report on the PW Consulting website. Our advisory team is available for bespoke workshops to apply these findings to your specific portfolio and operating model.
For detailed analysis of this topic, please visit the official page: Polymer Gel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com