

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.12% CAGR for Carpal Tunnel Syndrome Treatment Market, New Report Reveals

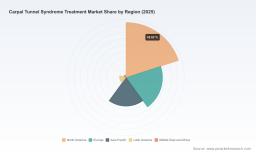
PW Consulting Releases Strategic Brief: Carpal Tunnel Syndrome Treatment Market Outlook to 2032 — Tactical Intelligence for 2026 Decision-Making
PW Consulting today publishes a focused industry brief accompanying our full market research report on the Carpal Tunnel Syndrome (CTS) Treatment Market. This executive-level release is designed to translate market intelligence into near-term commercial and clinical strategy for executives, investors, and payer leads who must act in 2026. The accompanying dataset and proprietary models underpinning this brief are available through our report portal.
Carpal Tunnel Syndrome Treatment Market
Executive snapshot
Using 2025 as the base year and a forecast horizon of 2026–2032, the global CTS treatment market is projected to grow at a compound annual growth rate (CAGR) of 6.12% (values stated in USD, revenue unit: Million). After increasing from the mid‑hundreds of USD million in 2020 to approximately 748.6 USD million in 2025, our baseline model projects continued expansion through the forecast period and a market value exceeding 1.1 billion USD by 2032. This trajectory reflects a combination of secular drivers — demographic trends, rising procedure volumes in ambulatory settings, reimbursement code shifts, and technology-driven modality substitution — alongside episodic regulatory and competitive developments that will shape adoption curves in the near term.
Carpal Tunnel Syndrome Treatment Market
Why this report matters for decisions in 2026
- Coding and reimbursement are game‑changers: Effective January 1, 2026, a new Category I CPT code for percutaneous carpal tunnel decompression (CPT 64728) enters the coding universe, with specific valuing conventions (notably a 0‑day global period and separate reporting of post‑procedure visits). This alone alters commercial economics for percutaneous device innovators and triggers a re-evaluation of procedure site selection, pricing, and contracting strategies.
- Procedural modality mix is in flux: Endoscopic, ultrasound‑guided, and percutaneous approaches all have different OR time, consumable, and training profiles. Recent regulatory clearances and independent clinical publications supporting ultrasound‑guided approaches have accelerated provider interest and payer scrutiny alike.
- Regulatory vigilance remains material: The FDA’s enforcement actions in 2025 against unapproved therapy claims underscore the reputational and financial downside for regulatory non‑compliance. Conversely, 510(k) clearances for image‑guided and endoscopic systems have lowered the barrier to market entry for differentiated technologies.
Recent developments that should be in every 2026 playbook
- Regulatory clearances in 2025–2026 for several image‑guided and endoscopic CTS treatment systems have validated new procedural pathways and expanded commercial options for minimally invasive release.
- Independent clinical publications in 2026 have given ultrasound‑guided carpal tunnel release additional credibility across the diagnosis–treatment continuum, supporting hospital and ambulatory adoption where reimbursement is favorable.
- Reimbursement guidance in 2026 assigns specific payment constructs to both percutaneous and endoscopic approaches under existing CPT frameworks (and Medicare payment schedules), which will materially affect device pricing and hospital/ASC contracting strategies.
What the report contains — practical, executable intelligence
This report moves beyond descriptive market sizing to provide tools and frameworks that executives can apply immediately in 2026 planning cycles. Key deliverables include:
Carpal Tunnel Syndrome Treatment Market
- Proprietary market sizing and demand-driver decomposition (2020–2032), with transparent methodology and sensitivity testing to changes in reimbursement and procedure mix.
- A reimbursement and coding playbook that decodes CPT changes, Medicare payment positions, and commercial payer negotiation levers — with templates for capturing incremental margin impact under alternate coding adoption scenarios.
- Regulatory risk matrix and compliance checklist tailored to CTS device and software vendors, mapping likely FDA interactions and real‑world evidence expectations.
- Competitor diagnostic — a strategic scorecard evaluating clinical differentiation, channel reach (hospitals, ASCs, specialty clinics), product breadth, and barriers to entry for each significant participant.
- Go‑to‑market playbooks for device OEMs and diagnostics firms: seller economics for hospitals vs. ASCs, training and adoption roadmaps, and partnership models with imaging/AI vendors.
- M&A and investment due‑diligence templates, including a valuation overlay that links device adoption scenarios, coding sensitivity, and payer coverage assumptions to enterprise value ranges.
- Primary research appendices and an Excel® model packaged for scenario testing at culture, pricing, and reimbursement inflection points.
Competitive landscape — synthesis and implications
The report evaluates the competitive field across established medtech OEMs, specialist device firms, and emerging ultrasound/AI diagnostic vendors. Major incumbents retain leadership through installed surgical systems, distribution reach, and clinical relationships. Notable strategic positions observed during our research include:
- Companies with established endoscopic portfolios leverage procedural familiarity and hospital channel strength to defend share, but face pressure on procedure cost and OR time.
- Newer entrants offering ultrasound‑guided or percutaneous solutions are capitalizing on the new CPT environment and on the operational advantages of outpatient delivery; however, they must accelerate real‑world evidence generation and clinician training to broaden adoption.
- Diagnostic imaging vendors that pair handheld ultrasound with AI tools are creating an upstream funnel by improving diagnosis accuracy and standardizing pre‑operative workups — an advantage for platform players aiming to control the peri‑procedural pathway.
From an industry concentration standpoint, the market exhibits a moderate top‑end concentration: the combined share of the three largest players and of the five largest players indicate meaningful scale advantages for incumbents while leaving substantial room for specialists and disruptors. For potential acquirers or investors, this duality — incumbent scale vs. niche opportunities — creates differentiated deal archetypes: tuck‑ins that consolidate supply and platform deals that accelerate adoption of new procedural approaches.
Top strategic imperatives for 2026
- Make reimbursement the first line item: Prioritize coding strategy, payer evidence generation, and early engagement with CMS and major commercial payers. CPT 64728 changes will determine the economic runway for percutaneous devices.
- Invest in real‑world evidence: Rapidly build registries and post‑market surveillance capabilities that answer payers’ questions on safety, re‑intervention rates, and total cost of care.
- Optimize channel strategy for ASCs: Align pricing, consumable bundles, and surgeon training programs to the operational constraints of ambulatory settings where procedure migration is intensifying.
- Integrate diagnostics and procedural offerings: Pairing AI‑enabled ultrasound diagnostics with guided release technologies can lock in clinical pathways and create differentiated value propositions to payers and health systems.
- Prepare for regulatory and reputational risk: Incorporate label compliance, marketing review, and clinical claim governance into go‑to‑market timelines to avoid costly regulatory enforcement actions.
Why we withhold granular splits here (and how to get them)
In service of the report’s role as a strategic “trailer,” we present high‑confidence, audited market totals and structural insights here while intentionally withholding the granular region, treatment‑type, and end‑user revenue splits that most directly drive execution decisions. The full report delivers these detailed segmentation matrices, payer reimbursement crosswalks by procedure code, and downloadable financial models that allow teams to run bespoke scenarios for 2026 board decisions. If your immediate objective is to model acquisition targets, build a reimbursement submission, or reconfigure a commercial field force, the full dataset is required to operationalize those steps.
How to use this report in the 2026 planning cycle
- Board briefings and capex approvals: use scenario outputs to justify investment in percutaneous vs. endoscopic platforms.
- Commercial strategy: reconfigure sales incentives and training budgets based on projected migration to ASCs and new coding economics.
- R&D prioritization: allocate spend to evidence generation where payers and clinicians will require it (e.g., long‑term outcomes and procedural efficiency).
- M&A screening: apply our valuation overlay to identify targets whose upside is most sensitive to favorable reimbursement or rapid real‑world adoption.
Closing — immediate next steps
For leadership teams planning 2026 initiatives, the window to influence payer policy, clinician adoption, and site‑of‑service economics is narrow. PW Consulting’s full Carpal Tunnel Syndrome Treatment Market report couples authoritative market sizing with executable playbooks and financial models to turn insight into action. Access to the complete report provides the granular segmentation, payer crosswalks, and deal templates necessary to execute with confidence.
To request the full report, the underlying Excel® models, or to arrange a bespoke briefing for your executive team, please visit our report portal or contact PW Consulting’s strategic services desk. Our analysts are available for targeted sessions to translate the data into a prioritized 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Carpal Tunnel Syndrome Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com