

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Selective Soldering Equipment Market to Expand at 6.8% CAGR Over 2026–2032

Selective Soldering Equipment Market: Strategic Preview for 2026 Decisions
PW Consulting’s latest market intelligence brief on the Selective Soldering Equipment market equips senior executives, capital allocators, and operations leaders with a concise, decision-focused view ahead of critical 2026 investment cycles. The market is poised for renewed momentum: after a five-year historical span of oscillating demand, our base-year benchmarking (2025) and forward-looking modeling through 2032 indicate a robust compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. This growth trajectory, coupled with mid-market concentration and rapid technology adoption in mixed-technology PCB assembly, creates a strategic inflection point. Below we summarize the strategic implications, competitive dynamics, and the tangible, operational modules included in the full report—while deliberately withholding detailed subsegment breakdowns to preserve the report’s proprietary value and encourage direct engagement for comprehensive data access.
Selective Soldering Equipment Market
Market Snapshot and What It Means for 2026 Strategy
After recovering from cyclical pressures in the early 2020s, the Selective Soldering Equipment market reached a new benchmark in our 2025 base year and is projected to expand meaningfully in 2026 and beyond. The anticipated growth is not merely a function of rising electronics production volumes; it is structural. Key tailwinds include the acceleration of lead-free and mixed-technology assemblies, the electrification of vehicle platforms with denser through-hole and mixed SMT requirements, and stricter quality standards in regulated sectors such as aerospace, medical, and automotive where void control and reliability are non-negotiable.
Selective Soldering Equipment Market
For executives planning CapEx, the 6.8% CAGR should be interpreted as an opportunity window rather than a guarantee: adoption is concentrated in facilities that prioritize precision, repeatability, and process integration. Our modeling shows recovery and step-change investment behaviors—some OEMs will retrofit selective soldering into legacy lines, while others will rationalize production around automated inline platforms. This bifurcation creates distinct implications for equipment vendors, contract manufacturers, and corporate procurement teams.
Selective Soldering Equipment Market
Strategic Imperatives for 2026 Decision-Makers
-
Prioritize precision and process integration: Investments should favor platforms that enable deterministic soldering outcomes with integrated fluxing, preheating, and automated process monitoring. Mitigating rework and achieving first-pass yield improvements are the fastest routes to justify CapEx.
-
Balance modularity and throughput: Buyers must evaluate whether modular, scalable systems or high-throughput inline platforms better align with near-term production schedules and product roadmaps. Our report provides a decision framework and ROI scenarios that quantify the trade-offs under different volume and mix assumptions.
-
Embed regulatory and reliability requirements into procurement specs: Compliance with industry standards for void control and reliability is increasingly driving equipment selection. Procurement teams that incorporate technical acceptance criteria up front avoid costly retrofits and extended qualification times.
-
Account for operational savings beyond unit price: Selective soldering can materially reduce solder consumables and nitrogen usage versus legacy wave methods. When modeled over typical production lifecycles, these operational savings significantly narrow payback periods for higher-end systems.
-
Plan for service, spare parts, and lifecycle management: Given moderate market concentration and the presence of global service networks, after-sales support capability is a differentiator. Our vendor assessment ranks providers on service footprint, spare-parts lead time, and upgrade pathways.
Competitive Landscape: Who Matters and Why
The Selective Soldering Equipment market sits in a mid-consolidation phase—our CR3 and CR5 measures indicate a market where leading suppliers hold meaningful share but room remains for regional specialists, niche innovators, and cost-focused entrants. Buyers and investors should read market share metrics as a signal of scale and service continuity, not as a prescriptive buying guide. Below is a synthesis of strategic positions and capabilities from the vendor universe we analyze in the full study.
-
Kurtz Ersa GmbH (Germany) — A global leader with modular systems spanning entry-level to high-volume production. Their VERSAFLOW and ECOSELECT platforms, combined with electromagnetic pump technology and multi-nozzle configurations, make them a go-to supplier for manufacturers transitioning from prototype to continuous high-volume runs. Recent trade-show activity and new platform introductions underscore their push to capture automation-led growth.
-
Nordson SELECT (United States) — Offers a broad portfolio including standalone, inline, and multi-station systems with a strong global service network. Their strength lies in supporting geographically distributed manufacturers who require consistent uptime and standardized process recipes across multiple sites.
-
SEHO Systems GmbH (Germany) — Known for solutions that integrate fluxing, preheating, and soldering zones to optimize throughput and yield. Their systems are frequently specified where productivity and solder quality are jointly prioritized.
-
Pillarhouse International Ltd (United Kingdom) — A heritage innovator credited with pioneering selective soldering. Their emphasis on engineering rigor and patented technologies appeals to high-reliability sectors.
-
JUKI Corporation & Apollo Seiko (Japan) — Both offer batch and inline solutions for through-hole and mixed-technology boards. Apollo Seiko’s dual-pot innovations and recent expanded inline lineup indicate a focus on throughput and precision for high-mix environments.
-
North American and niche suppliers — Companies such as DDM Novastar, RPS Automation, TM Soldering Solutions, and several regional vendors provide compelling value for short- to medium-run production and for customers prioritizing domestic support and compatibility with legacy systems.
Our competitive analysis does more than profile product lines: it maps capability clusters to buyer archetypes (e.g., high-volume OEMs, regional EMS providers, niche aerospace suppliers) and quantifies where each vendor’s value proposition accelerates or constrains adoption. Recent market moves—new product launches, trade-show showcases, and geographic expansions—are evaluated for their likely impact on share shifts and service expectations over 2026–2028.
Market Dynamics and External Drivers
-
Technological drivers: Miniaturization, mixed-technology PCBs, and lead-free requirements are persistent structural drivers that favor selective soldering’s precision capabilities.
-
Regulatory and quality standards: Increasingly stringent acceptance criteria for voiding and joint integrity in regulated industries elevate selective soldering from a “nice-to-have” to a mandatory process in many assemblies.
-
Raw material and process economics: While solder fluxes and related consumables remain a substantial adjacent market, selective soldering’s lower solder usage and optimized gas consumption can create measurable OPEX reductions—an important lever during tightening margins.
-
Market concentration: Mid-level consolidation (as reflected in our CR3/CR5 analysis) means buyers can access both global service-backed platforms and innovative regional alternatives; the resulting vendor landscape supports competitive procurement dynamics if buyers emphasize lifecycle cost and service-level agreements.
What the Full Report Contains (Operational & Decision-Ready Modules)
PW Consulting’s full report goes beyond narrative and provides operationally actionable tools that procurement, operations, and strategy teams can deploy immediately. Highlights include:
-
Executive dashboards with scenario-based demand forecasts and sensitivity analysis tied to product mix and production volumes.
-
CapEx decision framework with payback calculators, TCO templates, and upgrade-versus-replace matrices customized for different buyer archetypes.
-
Vendor due-diligence playbook covering technology fit, service footprint, upgrade pathways, and spare-parts risk mapping.
-
Process integration checklists to accelerate qualification and reduce time-to-volume after equipment installation.
-
Regulatory compliance matrices and acceptance test plans tailored for high-reliability sectors.
-
Deal structuring recommendations for OEMs and EMS providers—including procurement levers for financing, lease options, and performance-based maintenance contracts.
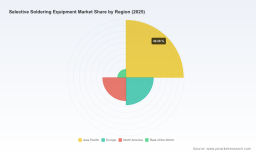
To respect the preview nature of this release, detailed subsegment tables (regional splits, type and application breakdowns) and company-level revenue by subsegment are reserved for the full report and data package available through our distribution channels.
How to Use This Insight in 2026 Planning Cycles
-
Align CapEx timing with product roadmaps: Use our scenario outputs to determine whether Q2–Q3 2026 is optimal for procurement, considering supplier lead times and qualification windows.
-
Embed operational KPIs into vendor contracts: Specify yield, voiding, and cycle-time targets to reduce scope creep and ensure predictable performance.
-
Consider hybrid deployment strategies: A blend of inline systems for core products and standalone/batch platforms for low-volume, high-mix SKUs can optimize utilization and speed to market.
-
Use lifecycle cost modeling to justify premium systems: When modeled across typical production lifespans, improved yield and lower OPEX often offset higher initial equipment outlays.
Access the Full Report
For procurement teams, technology scouts, and corporate strategists preparing budgets and roadmaps for 2026, the full PW Consulting Selective Soldering Equipment Market report provides the granular data, scenario tools, and vendor intelligence needed to make defensible decisions. The preview above outlines core strategic takeaways—but the full dataset, vendor scorecards, and executable templates are accessible through our secure distribution channel. Contact PW Consulting to arrange a briefing, obtain the comprehensive data package, or commission a tailored workshop to translate our findings into your operational plan.
PW Consulting is dedicated to delivering market research with operational immediacy: our Selective Soldering Equipment study is designed to be directly actionable on the shop floor, in procurement negotiations, and at the boardroom level as companies finalize 2026 capital and strategic plans.
For detailed analysis of this topic, please visit the official page: Selective Soldering Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com