

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cloud Logistics Software Market Set to Surge from USD 22.5 Billion in 2025 to USD 58.05 Billion by 2032 at a 14.5% CAGR (Forecast 2026–2032)

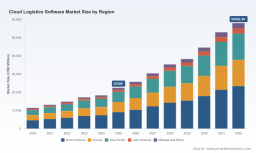
Cloud Logistics Software Market 2026: Strategic Imperatives from PW Consulting’s New Market Report
PW Consulting today releases a forward-looking market study on the Cloud Logistics Software market that translates macro momentum into practical decision-making frameworks for enterprise technology leaders planning investments in 2026. Grounded in a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study quantifies a rapidly expanding opportunity — the market reached roughly USD 22.5 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 14.5% through 2032, reaching approximately USD 58.1 billion by the end of the period. This release highlights the report’s strategic value for procurement, IT leadership, and supply chain transformation teams while deliberately reserving the report’s granular segment tables and vendor scorecards for the full study.
Cloud Logistics Software Market
Why this report matters to 2026 decision-makers
-
Timing and scale: The growth trajectory between 2025 and 2032 signals continued enterprise migration to cloud-native logistics stacks — creating windows for both strategic expansion and tactical procurement. Buyers that move beyond feature checklists and into scenario-based TCO modelling will materially improve negotiation outcomes and deployment ROI.
Cloud Logistics Software Market -
Complexity of choice: The vendor landscape is neither a pure oligopoly nor a fragmented long tail. The market concentration profile reveals a mid-level consolidation dynamic (CR3 ~35%, CR5 ~48.5%), which means large platform vendors co-exist with specialized challengers. This mix elevates the importance of modular architecture and integration governance in vendor selection.
Cloud Logistics Software Market -
Regulatory and cost shocks: Two external dynamics — rising cloud hosting and server hardware costs (industry forecasts show hosting increases of 5–10% in mid‑2026 and upstream server cost inflation of 15–20%) and tightening regulatory requirements around data transfer and AI — materially affect procurement timelines, contract structures, and lifecycle TCO assumptions.
From insight to action: What the report delivers for practitioners
PW Consulting structured the study to be operationally prescriptive. Beyond market sizing and directional forecasts, the report provides step-by-step tools that CIOs, heads of logistics, and procurement teams can use immediately to sharpen strategy and execution in 2026:
-
Decision frameworks for selection: a vendor-fit matrix that prioritizes interoperability, API maturity, and cloud deployment models against enterprise control points (data sovereignty, latency, SLA needs).
-
TCO and scenario models: build-your-own calculators that incorporate cloud price shocks, hardware cost pass-throughs, and multi-year maintenance. These models enable procurement to stress-test 3–7 year scenarios during RFP negotiations.
-
Migration and integration playbooks: sequence-based roadmaps for brownfield lifts, greenfield deployments, and hybrid cloud coexistence, including cutover risk checklists and rollback criteria.
-
AI-readiness and governance checklist: practical steps to align logistics AI use-cases with GDPR cross-border transfer documentation, EU AI Act obligations, and vendor attestations for model transparency and risk classification.
-
Compliance and security blueprints: prescriptive controls for zero‑trust architecture, continuous monitoring, and third-party vendor risk assessments tailored to cloud logistics workflows.
-
Commercial playbook: contract clauses and procurement levers — from blended pricing structures to performance-based SLAs and capacity hedges — that protect buyers from mid-contract cloud price increases.
Competitive landscape: who to watch and how to evaluate them
The report profiles both platform incumbents and specialist innovators, offering comparative insight on strategic positioning, product breadth, integration ecosystems, and enterprise traction. Sample profiles include:
-
Descartes Systems Group (Waterloo, Canada) — a longstanding provider of cloud-based freight, customs compliance, routing, and visibility solutions oriented to transportation providers.
-
SAP SE (Walldorf, Germany) — integrates cloud logistics within a broader enterprise suite, appealing to customers seeking end-to-end SCM alignment with ERP landscapes.
-
Oracle Corporation (Austin, USA) — delivers cloud-native SCM and transportation capabilities that target large-scale logistics orchestration and demand-supply matching.
-
Microsoft Corporation (Redmond, USA) — leverages Dynamics 365 and Azure for real-time visibility and planning, with an emphasis on platform extensibility and partner ecosystems.
-
Magaya Corporation (Miami, USA) — a focused freight forwarding and warehouse solution vendor, recently recognized in industry awards for its cloud logistics suite.
-
Blue Yonder (Panasonic) — known for AI-driven planning and optimization layered on cloud-native warehouse and transportation modules.
-
Manhattan Associates — a cloud-native provider targeting warehouse, transportation, and order management at scale.
-
Trimble, E2open, WiseTech Global and others — a mix of fleet, forwarding, and supply chain execution specialists that underpin vertical use-cases and regional hubs.
The report provides a vendor evaluation rubric that weights capabilities differently depending on buyer archetypes — from global integrators to regional forwarders and last‑mile operators. For example, the rubric emphasizes AI transparency and data portability for enterprises with strict compliance requirements, while prioritizing routing optimization and carrier network depth for high-volume logistics operators.
Recent market signals that alter strategy in 2026
-
Product innovation: new entrants and fast-scaling startups continue to push unified, AI-driven platforms for execution (e.g., recent launches of unified last-mile cloud platforms), forcing incumbents to accelerate modularization and partner programs.
-
Awards and recognition trends: vendor differentiation increasingly exhibits through product-led reputation (software review platforms, industry awards), influencing procurement shortlists in mid-market segments.
-
Cost and supply-chain pressure: cloud hosting vendors’ announced pricing pressures and downstream hardware inflation require procurement teams to re-examine capex vs. opex trade-offs and to demand more flexible commercial protections.
-
Regulatory tightening: enforcement emphasis on cross-border data transfer documentation (SCCs, Transfer Impact Assessments), and operationalizing EU AI Act mandates, particularly affects multi-jurisdictional logistics operations using third-party cloud AI services.
Risk matrix and mitigation playbook
Adoption of cloud logistics software in 2026 carries both upside and structural risk. PW Consulting’s report uses a concise risk matrix and prescriptive mitigations:
-
Cost volatility — mitigate with blended contracts, multi-year caps, and cloud cost-sharing clauses.
-
Regulatory compliance — require vendor documentation for data flows, model risk assessments, and contract-level indemnities tied to data processing and AI outcomes.
-
Integration failure — adopt phased rollouts, invest in API-first middleware, and embed rollback triggers into runbooks.
-
Operational resilience — enforce zero‑trust access, continuous monitoring, and cross-supplier SLAs to reduce single-provider systemic exposure.
How buyers should act in Q1–Q2 2026
-
Run a rapid, 8-week vendor pre-selection using PW Consulting’s checklist to separate strategic fits from tactical fixes.
-
Demand scenario pricing from shortlisted vendors that includes stress cases reflecting the 5–10% hosting increase window and vendor-passed hardware cost adjustments.
-
Prioritize contract language on data portability, AI transparency, and audit rights; do not defer compliance requirements to a future addendum.
-
Invest in integration pilots that validate real-world throughput and SLA observability before committing to enterprise-wide rollouts.
Report scope, methodology and the next steps
The study uses a mixed-methods approach combining bottom-up vendor analysis, primary interviews, and macroeconomic drivers across a 2020–2025 historical window and a 2026–2032 forecast horizon. Forecasts apply a 14.5% CAGR to reflect adoption curve dynamics, technology maturation, and enterprise digitalization rates observed in our primary research. Detailed segment-level tables, vendor scorecards, pricing benchmarks, and downloadable tools are reserved for the full report.
Conclusion — strategic value proposition
For leaders making cloud logistics investments in 2026, the choice is no longer binary between cloud and on-premises; it’s about designing resilient, cost‑efficient, and compliant logistics platforms that can scale across every node of a global supply chain. PW Consulting’s market study translates a multi-billion-dollar growth trajectory into a set of executable actions: vendor selection rubrics, TCO models sensitive to near-term hosting inflation, compliance blueprints for GDPR and the EU AI Act, and pragmatic migration playbooks. These are the constructs procurement teams and technology leaders need to reduce deployment risk, accelerate time-to-value, and secure strategic advantage.
To review the full dataset, vendor profiles, and downloadable decision tools referenced in this release, authorized readers should consult the complete PW Consulting Cloud Logistics Software Market report.
For detailed analysis of this topic, please visit the official page: Cloud Logistics Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com