

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial-Grade Trichlorosilane Market to Nearly Double from USD 6.45 Billion in 2025 to USD 11.14 Billion by 2032 at an 8.12% CAGR

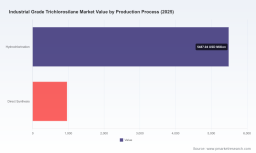
Industrial‑Grade Trichlorosilane Market: Strategic Imperatives for 2026 — PW Consulting Outlook
PW Consulting today releases a strategic preview of our Industrial Grade Trichlorosilane (TCS) Market research — a concise executive distillation designed to orient C‑suite decision makers, investment committees, and upstream/downstream supply‑chain leaders as they plan for 2026. The market is at an inflection point: after a steady recovery through the mid‑2020s, our modeling shows the global industrial‑grade TCS market (base year 2025) standing at USD 6,450 Million and poised to reach approximately USD 11,140 Million by 2032, expanding at a compound annual growth rate (CAGR) of 8.12% over the 2026–2032 forecast horizon. This combination of growth momentum and structural change presents both opportunity and strategic complexity for market participants.
Industrial Grade Trichlorosilane Market
Why this matters for 2026 decisions
-
Investment timing: Firms considering capacity additions, purification upgrades, or vertical integration need frameworks that balance near‑term feedstock volatility with multi‑year demand acceleration driven by polysilicon and specialty silicone markets.
Industrial Grade Trichlorosilane Market -
Supply‑chain resilience: Feedstock sourcing and exposure to regional trade measures are now critical determinants of margin stability. Executives must assess supplier diversification, hedging strategies, and on‑site integration versus market procurement.
Industrial Grade Trichlorosilane Market -
Regulatory and ESG readiness: Compliance investments and emissions control are material line‑items in Europe and will influence location, permitting timelines, and operating cost forecasts.
What the PW Consulting report delivers (actionable, but intentionally previewed)
Our full report combines a transparent market model with practitioner‑grade tools that convert data into decisions. Highlights include:
-
Dynamic market model (historical 2020–2025; forecast 2026–2032) calibrated to primary supply and demand drivers, enabling scenario runs for policy shocks, feedstock price swings, and demand cascades from polysilicon and silicone end‑markets.
-
Forward‑looking demand driver matrix connecting consumer electronics, solar PV manufacturing trends, and industrial silicone demand to TCS grade and volume requirements.
-
Unit cost and break‑even curves for prevailing production routes, with a supplier cost‑competitiveness heatmap and margin sensitivity to silicon metal price moves.
-
Regulatory impact assessment and permitting risk ladder (including REACH matrixes and likely compliance timelines across EU member states), mapped to likely capital interventions and throughput changes.
-
Commercial playbook for 2026: short‑list of high‑impact actions across sourcing, contract structure, capex phasing, and product‑grade prioritization — prioritized by value at risk and implementation lead time.
-
M&A and JV heatmap that identifies the types of assets and geography that create near‑term optionality versus long‑term strategic advantage.
Note: This preview deliberately omits the report’s granular segmentation tables, supplier level volume and price schedules, and downloadable financial model — these are available in the full report and interactive dashboard.
Market structure and competitive dynamics
The industrial‑grade TCS market is best characterized as moderately concentrated, with a narrow set of integrated chemical and polysilicon players holding the largest volumes. Leading incumbents combine upstream silicon metal integration or long‑term feedstock contracts with downstream purification capabilities and customer relationships in polysilicon and silicone supply chains. Key strategic archetypes we identify include: vertically‑integrated polysilicon producers, specialty chemical firms focusing on purity and regulatory know‑how, and high‑volume, low‑cost producers deploying advanced reactor technologies.
Representative company profiles and structural moves in recent quarters illustrate the mix of strategies shaping 2026 competitive dynamics:
-
Wacker Chemie AG (Munich) — continues to invest in electronic‑grade purification infrastructure while keeping industrial‑grade TCS integrated into its polysilicon and silicone chains; recent commissioning of a new purification facility underscores a strategy focused on higher‑value grades and regional security of supply.
-
Hemlock Semiconductor (Michigan) — a U.S. polysilicon producer that benefits from domestic policy support; CHIPS Act funding awarded in early 2025 strengthens its upstream position and reduces reliance on imported feedstock for strategic semiconductor flows.
-
OCI Company Ltd. (Seoul) — expanding capacity in Southeast Asia to capture regional polysilicon demand and leverage cost advantages in feedstock procurement and energy integration.
-
GCL‑Poly and other large Asian manufacturers — deploying fluidized‑bed reactor (FBR) and other high‑efficiency production technologies to scale industrial and solar‑grade TCS volumes while driving down energy intensity per unit.
-
Specialty chemistries (Tokuyama, Shin‑Etsu, Evonik, Dow, REC, TBEA) — retaining relevance through high‑purity grades, specialty applications, or integrated client service models aimed at silicone and electronic markets.
Recent developments we track as immediate decision inputs for 2026: Wacker’s late‑2025 purification facility launch in Germany; OCI’s capacity expansion in Malaysia; GCL‑Poly’s FBR‑based production start in Inner Mongolia; and Hemlock’s CHIPS Act funding award. Each event recalibrates regional competitive positions, purity availability, and potential offtake dynamics.
Supply‑side and feedstock dynamics
Feedstock — primarily metallurgical silicon metal — is the single most consequential input for TCS economics. Price fluctuations and policy interventions along silicon chains feed directly into manufacturer margins and location decisions. We highlight several material signals:
-
Pricing spike and volatility signals: Northeast Asia metallurgical‑grade silicon prices, and the variability recorded across industrial silicon grades in China in 2025, materially influence short‑run capacity utilization and contracting strategies for 2026.
-
Trade and policy interference: Measures such as Canada’s extended duties on certain silicon imports and temporary shifts in Chinese export controls create transient but high‑impact supply‑risk windows that require rapid contractual responses or contingency sourcing.
-
Technology and energy intensity: Newer reactor technologies and energy‑efficient processes (e.g., FBR) can reduce cost exposure, but they call for different capex profiles and operating expertise — a key trade‑off when planning expansions in 2026.
Regulation, ESG, and permitting — how compliance shapes capacity
Environmental compliance and permit regimes, particularly in Europe under REACH and allied reporting frameworks, are no longer back‑office issues. PW Consulting’s assessment shows that increased testing requirements and stricter emissions oversight can introduce both direct compliance costs and indirect lead‑time risks (inspections, temporary shutdowns) that make brownfield optimization and modular, lower‑emission expansions more attractive than greenfield projects in some markets.
Strategic playbook for 2026 (prioritized)
-
Secure feedstock optionality: Negotiate tiered supply contracts, explore local feedstock partnerships, and evaluate partial vertical integration where regulatory and policy support exist.
-
Optimize grade mix: Use demand elasticity analysis to prioritize investment in purification capabilities for grades with the highest margin uplift relative to incremental capex.
-
Invest in low‑carbon process options selectively: Target energy efficiency upgrades and reactor technologies that materially lower operating cost exposure to future carbon or energy price shocks.
-
Build compliance as a competitive moat: Early movers that build robust REACH and equivalent compliance programs can reduce downtime risk, win preferred‑supplier status with large OEMs, and command price premia.
-
Design M&A playbooks around optionality: Acquire assets that add tactical capacity, feedstock control, or purification IP rather than solely scale, given the market’s moderate concentration and geographically disparate demand growth.
How to use PW Consulting’s full report in 2026 planning
Executives should use the full PW Consulting industrial TCS package as both tactical and strategic input: run bespoke scenarios for corporate planning cycles, stress test procurement contracts under disruptive policy outcomes, and apply the supplier scorecards to shortlist partners for long‑term offtake or joint ventures. The interactive model supports customized sensitivity analyses (feedstock price swings, regional demand shocks, emissions cost trajectories) that align directly to capital budgeting and commercial negotiation timelines in 2026.
Next steps — where to find the full intelligence
This preview outlines the strategic contours and immediate decision levers for 2026. For the granular segmentation, supplier‑level financials, downloadable model, and the complete set of playbooks and templates referenced above, access to the full PW Consulting Industrial Grade Trichlorosilane Market report and dashboard is required. The full package contains the data tables and scenario outputs that translate this strategic framing into executable plans and quantified value estimates.
PW Consulting stands ready to run custom briefings and tailored scenario workshops for executive teams and investment committees seeking to convert this intelligence into board‑ready recommendations for 2026 capital allocation, sourcing strategies, and M&A moves.
For detailed analysis of this topic, please visit the official page: Industrial Grade Trichlorosilane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com