

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Clear Vision Ahead: PW Consulting Forecasts Anti‑Fog Polycarbonate Film & Sheet Market to Expand at a 5.45% CAGR Through 2032

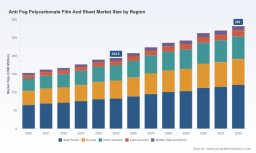
Anti-Fog Polycarbonate Film And Sheet Market: Strategic Imperatives for 2026
Introduction
PW Consulting today releases its authoritative market study on the Anti Fog Polycarbonate Film And Sheet Market. The analysis equips executives with the forward-looking intelligence necessary to shape product roadmaps, capital allocation, and supply-chain choices in 2026 and beyond. The market has shown steady expansion through the early 2020s and, on our base-year view (2025), stands at approximately USD 194.5 Million. Our forecast sees the sector expanding to roughly USD 282.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.45% across the 2026–2032 horizon.
Anti Fog Polycarbonate Film And Sheet Market
Why this report matters for 2026 decision-makers
-
Planning precision in a maturing market — As demand drivers shift from pandemic-related PPE to durable industrial and architectural applications, managers must align production and R&D investments to capture higher-margin, durable-demand segments without over-committing to legacy product forms.
Anti Fog Polycarbonate Film And Sheet Market -
Cost volatility and margin preservation — Fluctuations in polycarbonate feedstock and related chemistries are creating input-cost noise that can erode margins quickly; procurement and pricing strategies crafted with near-term scenario analysis will separate winners from the pack.
Anti Fog Polycarbonate Film And Sheet Market -
Regulatory and sustainability inflection points — Evolving limits on persistent additives and growing sustainability mandates are accelerating product re-engineering; firms that move early can secure market access while commanding premium pricing.
-
Competitive positioning in a moderately concentrated market — The market concentration profile indicates meaningful scale advantages for market leaders, but also room for focused challengers with differentiated coatings, service models, or localized capacity.
What the PW Consulting report delivers — practical, executable content
-
Consolidated market sizing and seven‑year forecast (2026–2032) with scenario pathways tied to raw material, regulatory, and end-market demand variables.
-
Demand-signal matrix by application and product form that links buyer specifications to expected willingness-to-pay and retention risk (note: the published summary intentionally omits granular regional/application share tables to preserve lead capture).
-
Cost‑to‑serve and margin simulation tools — interactive templates that let procurement and finance teams model the P&L impact of feedstock swings and coating-cost differentials.
-
Regulatory compliance playbook — a mapped set of near-term policy changes and compliance deadlines, cross-referenced to product formulations and recommended certification pathways.
-
Competitor value-mapping and capability heatmaps — actionable intelligence on manufacturing footprints, coating technologies, supply partnerships, and channel strengths.
-
M&A and partnership triggers — an acquisition-priority framework that highlights the capability gaps best filled by buy, build, or partner approaches.
-
Commercial pilots and field validation blueprints — turnkey protocols for testing anti-fog performance (lab & in-situ), lift-out criteria, and productization timetables.
Market dynamics: cost, regulation, and demand drivers
The industry is being shaped by three intersecting forces. First, feedstock cost volatility—driven by upstream phenol/acetone value chains—has increased raw-material unpredictability. Procurement teams that move to hedging strategies, long-term supplier agreements, or vertical integration gain near-term insulation.
Second, regulatory tightening in jurisdictions across Europe and elsewhere is driving R&D away from legacy additives toward alternative chemistries and PFAS-free coating platforms. Several recent regulatory updates have introduced substance limits and compliance deadlines that materially affect formulation choices and time-to-market for new grades.
Third, application-side evolution is diversifying demand. While personal protective equipment and medical visors remain important, durable requirements from greenhouse glazing, refrigerated applications, and architectural uses are driving demand for longevity and abrasion resistance rather than single-use anti-fog performance. This shift favors suppliers able to certify long-term anti-fog lifecycles and offer extended warranties.
Competitive landscape — snapshot and tactical implications
The market exhibits moderate concentration: the top-three players command a meaningful share of available revenue, and the top-five together account for a majority slice of the competitive footprint. This structure favors firms that can leverage scale in coating application, distribution, and brand trust, but it leaves niches open for specialized innovators.
-
POLYVANTIS (formerly SABIC Innovative Plastics) — a global materials innovator offering LEXAN™ anti-fog film grades that combine long-term hydrophilic performance with abrasion and impact resistance. Ideal benchmark for companies designing PPE- and high-humidity-use specifications.
-
Covestro AG, Mitsubishi Gas Chemical, and Teijin Limited — leading polymer and chemicals groups that supply engineered film and sheet forms with formulations targeted at automotive and electronic-display OEMs. These suppliers set technical benchmarks and licensing standards.
-
FSI Coating Technologies (SDC Technologies) — a North American specialist in permanent anti-fog and abrasion-resistant coatings; its recent commercial activity around PFAS-free formulations is a strategic signal for coating transitions.
-
Regional producers (select Chinese and global fabricators) — a cohort of manufacturers focused on coated sheets and customizable fabrication services that serve construction, greenhouse, and local OEM markets. Their agility on lead times and price makes them preferred partners for regional programs.
-
Brett Martin’s American capacity build and similar mid-market expansions are reshaping North American supply dynamics by adding localized scale for multiwall and corrugated products.
Collectively, these players illustrate three repeatable strategic approaches: (1) integrated material/grade leadership with global distribution, (2) coating-chemistry specialization with service-led differentiation, and (3) regional mass-production with cost and logistics advantages. We map each public move (capacity builds, product launches, and product‑life claims) to the likely competitive impact in the report.
Recent industry movements to monitor in 2026
-
Capacity reshaping: strategic investments in North American multiwall/corrugated production are likely to shorten lead-times and increase local competition for greenhouse and horticulture applications.
-
Coating innovation: the introduction and rapid uptake of PFAS-free and long-life anti-fog chemistries change specification conversations with OEMs and institutional buyers.
-
Performance claims: supplier guidance and third-party validation of decade-plus anti-fog lifecycles will materially influence procurement preferences for long-term installations.
Strategic recommendations for executives in 2026
-
Prioritize dual-track product development: short-term reformulations to comply with tightening regulations, plus longer-term investment in sustainable, high-durability coatings.
-
Lock in diversified feedstock agreements and model price pass-through mechanisms to protect margins during episodic raw-material spikes.
-
Deploy targeted capacity near key demand clusters to mitigate tariff risk and logistics costs; assess toll-coating partnerships as a capital-light route to localized supply.
-
Invest in independent, third-party validation of anti-fog longevity to create procurement defensibility for premium positioning.
-
Use buy/build/partner criteria from our M&A framework to evaluate acquisitions of coating specialists or regional converters that could accelerate market entry.
-
Introduce commercial pilots that bundle product guarantees with life-cycle service to convert risk-averse institutional buyers.
How PW Consulting helps
Our Anti-Fog Polycarbonate Film And Sheet Market report is not a static PDF — it is a transaction-focused toolkit. Clients receive tailored scenario workshops, procurement stress-tests, and a competitor-intelligence dashboard calibrated to their strategic choices. We run practical due diligence for M&A targets, co-develop compliance roadmaps, and design pilot protocols that reduce commercialization time by benchmarking against validated industry tests.
Next steps
For companies considering capex commitments, launching next-generation coating grades, or evaluating acquisition targets in 2026, this report provides the empirical foundation and executable playbooks to de‑risk decisions. To access the full report, complete datasets, and the proprietary modeling tools that underpin our forecasts, please visit PW Consulting’s Anti Fog Polycarbonate Film And Sheet Market landing page or contact your PW Consulting representative to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Anti Fog Polycarbonate Film And Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com