

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High-Purity Tungsten Market Poised for a 6.5% CAGR Through 2032

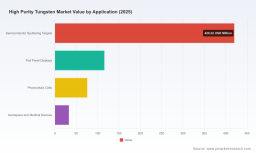
High Purity Tungsten Market — Strategic Insights for 2026: A PW Consulting Report Preview
PW Consulting’s new High Purity Tungsten Market report (base year 2025; forecast 2026–2032) synthesizes market sizing, supply-chain thermodynamics, regulatory inflection points, and competitor strategic positioning into an actionable playbook for executive decision-makers. The market reached approximately USD 644.6 Million in 2025 and, under the base forecast, is expected to expand at a compound annual growth rate (CAGR) of 6.5% through the forecast window, reaching roughly USD 1,001.6 Million by 2032. These topline dynamics frame both near-term tactical choices and longer-term strategic investments for 2026 and beyond.
High Purity Tungsten Market
Why this report matters for 2026 corporate strategy
-
Timing: 2026 will be a pivotal year when regulatory shocks, raw-material price volatility and new primary supply come into operational alignment. Companies that translate market intelligence into procurement, capacity and partnership moves this year will secure asymmetric advantages.
High Purity Tungsten Market -
Risk-to-Reward mapping: Our analysis quantifies how supply shocks and policy levers translate into input-cost exposure and margin pressure. The report offers scenario-based financial impacts, enabling CFOs and commercial teams to prioritize hedges, contracts, and inventory levers with precision.
High Purity Tungsten Market -
Competitive positioning: With the market exhibiting moderate concentration (top-three share ~46%; top-five share ~62%), there is a clear incentive for either consolidation plays or focused differentiation. We provide playbooks for both challengers and incumbents.
-
Capital allocation: The forecast horizon highlights where capex and M&A can deliver the highest risk-adjusted returns—whether through upstream security of feedstock, downstream value-capture, or technology-led product differentiation.
What the report contains — practical, implementable intelligence
PW Consulting designed this study as a practitioner’s manual. Highlights include:
-
Robust market sizing and trend decomposition: historical analysis (2020–2025) and a transparent, model-driven forecast (2026–2032) with scenario sensitivity to raw-material prices, tariff regimes, and demand elasticity.
-
Supply-chain mapping: detailed visualization of critical nodes (APT and tungsten oxide intermediates, reduction and powder production, downstream mill products) and points of geopolitical concentration.
-
Price-model toolkit: an executable model calibrated to observed APT price movements, Rotterdam benchmarks and midstream processing margins—designed for CFOs to run “what-if” scenarios.
-
Regulatory impact assessment: quantifies the effect of recent policy measures and likely follow-on actions in major markets, with mitigation recommendations by stakeholder (procurement, legal, operations).
-
Supplier due-diligence and scorecards: qualitative and quantitative assessments of the major players, manufacturing footprints, integration levels, and strategic intents—structured for quick comparison in sourcing decisions.
-
Investment and M&A playbooks: valuation checklists, integration risk matrices, and five practical transaction archetypes (upstream security, capacity bolt-on, technology acquisition, offtake-led JV, and recycling/secondary-market entry).
-
Operational playbook: inventory policies, contract templates (term vs spot mix), and technology adoption pathways to reduce feedstock intensity.
Competitive landscape — what the leading firms signal
The report profiles the ecosystem of manufacturers and materials firms that will shape pricing, availability and technology adoption over the next five years. Key themes and firm-level implications include:
-
Fully integrated domestic producers (e.g., Elmet Technologies LLC): their integrated oxide-to-mill-product model reduces feedstock exposure and accelerates responsiveness to specialty downstream requirements. For buyers, these firms are attractive counter-parties when delivery reliability and product traceability trump lowest upfront price.
-
Independent powder specialists (e.g., Buffalo Tungsten Inc., Global Tungsten & Powders Corp.): these suppliers play a decisive role in niche, ultra-high-purity product segments and maintain strong relationships with semiconductor and electronics customers. Their flexibility makes them logical partners for co-development and specialized offtake arrangements.
-
European technology champions (e.g., H.C. Starck Tungsten GmbH, Plansee Group): their strengths lie in high-value applications and advanced material forms. These players typically set technical standards and are preferred suppliers for mission-critical, quality-sensitive applications.
-
Asian integrated capacity (e.g., A.L.M.T., JX Nippon, Xiamen Tungsten, Chongyi Zhangyuan, Masan High‑Tech): their scale and raw-material linkages give them cost-advantage in commodity grades but also expose them to trade policy and export-control risk—an important consideration for companies designing multi-sourced supply chains.
Taken together, these firm profiles underscore two strategic imperatives: (1) align source selection to the company’s tolerance for price vs reliability trade-offs, and (2) decide early whether to pursue vertical integration, strategic partnerships, or long-term offtake agreements to manage upstream risk.
Market dynamics and risk drivers to watch in 2026
-
Policy and trade measures: Recent policy moves—most notably significant tariff increases in major markets and new export-control regimes affecting upstream intermediates—have already tightened supply channels and elevated transaction risk. These policy levers remain key swing factors for pricing and access throughout 2026.
-
Raw-material price volatility: Ammonium paratungstate (APT), the critical intermediate, recorded sharp price runs in recent periods; market signals point to sustained volatility until new upstream capacity comes online and stock management practices stabilize.
-
New primary supply and strategic mining projects: Production starts at new deposits and strategic funding programs (including government support for domestic critical-minerals projects) will incrementally relieve tightness but with a multi-year lag from sanction-to-production.
-
Project-level developments: Recent project advances and offtake agreements demonstrate how developers and established materials firms are pre-positioning for tighter markets—events we use as leading indicators in our scenario analyses.
Practical implications for sourcing, manufacturing and investment decisions
For procurement and operations teams:
-
Adopt a layered sourcing strategy: blend spot purchases with prioritized long-term contracts and strategic reserves keyed to modeled price thresholds.
-
Negotiate flexible offtake terms with escalation clauses tied to transparent indices and feedstock benchmarks to share upside and downside with suppliers.
-
Accelerate qualification of multiple suppliers across jurisdictions to mitigate export control and tariff risk, while balancing traceability and quality compliance for sensitive end-markets.
For corporate strategy and finance:
-
Assess upstream investment via JV or bolt-on acquisition when internal cost-of-capital and strategic value of assured feedstock justify the capex and integration risks.
-
Prioritize investments in recycling and secondary feedstock technologies to reduce exposure to APT and improve margin resilience.
-
Use scenario-based valuations to price acquisition targets in a market where near-term price spikes can bias simple trailing-multiple approaches.
What PW Consulting recommends for 2026 action plans
-
Immediate (0–6 months): run the report’s price-model stress test against your P&L; renegotiate critical supplier contracts incorporating destination-agnostic clauses and force majeure clarifications tied to export controls.
-
Near-term (6–18 months): establish or expand strategic inventory bands; fast-track qualification of at least two alternate suppliers for each critical product grade; evaluate recycling pilots.
-
Medium-term (18–36 months): complete a portfolio review to determine whether vertical integration or equity stakes in upstream projects (domestic and allied jurisdictions) are warranted given your market exposure.
Where the value of the full report is concentrated
This preview outlines the strategic contours and the executive playbook. The full PW Consulting report contains the granular, decision-grade intelligence executives need to operationalize these recommendations: detailed segment-level forecasts, supplier scorecards, downloadable Excel models, contract templates, and actionable M&A checklists. In keeping with our “trailer” approach, we intentionally withhold detailed subsegment tables and region-specific market-share figures in this release to ensure that subscribers access the full model set and supplier appendices on the report landing page.
Concluding perspective
High purity tungsten is simultaneously a specialty materials market driven by advanced electronics and a strategic raw-material system shaped by geopolitics and mining cycles. The coming eighteen months will determine which firms secure advantaged positions and which are forced into reactive procurement that erodes margins. PW Consulting’s High Purity Tungsten Market report equips executives with the scenarios, commercial tools and supplier intelligence needed to convert market turbulence into strategic opportunity during 2026.
For organizations preparing procurement strategies, capital allocations, or M&A in the critical materials space, the full report provides the granular inputs and executable playbooks required to act with confidence.
For detailed analysis of this topic, please visit the official page: High Purity Tungsten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com