

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Defense Asset Management Software Market Poised to Reach USD 3,432.72 Million by 2032, Expanding at an 8.45% CAGR

Defense Asset Management Software Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, actionable briefing anchored to our latest market research on Defense Asset Management Software. The report documents a multi-year expansion of the market and delivers the practical toolset that procurement, sustainment, and IT modernization leaders need to make defensible 2026 decisions. To respect the “trailer” principle that governs this release, this communique highlights strategic conclusions, market trajectory, and vendor landscape insights while intentionally withholding detailed segment tables and scorecards—those are available in the full report on our website.
Defense Asset Management Software Market
Market Trajectory at a Glance
Defense asset management software has moved from niche utility to a mission-critical capability across defense organizations and their supplier ecosystems. Our study shows the market reached USD 1,945.5 Million in 2025 and is projected to expand materially over the coming decade, reaching USD 3,432.72 Million by 2032. That projection reflects a 2026–2032 compound annual growth rate (CAGR) of 8.45%, driven by accelerated modernization programs, expanded cloud adoption under DoD guidance, and increasing investment in AI-enabled predictive maintenance and logistics optimization.
Defense Asset Management Software Market
Why 2026 Is a Pivotal Year
-
Policy momentum: The DoD Software Modernization Implementation Plan (FY25–26) has crystallized expectations around SaaS ATO processes, enterprise licensing strategies, and FinOps discipline. These policy shifts shorten decision cycles for SaaS-capable vendors while raising requirements for security reciprocity and compliance documentation.
Defense Asset Management Software Market -
Regulatory and contract pressure: CMMC 2.0 asset management practices, DCMA Manual 4401-17 requirements, and longstanding Defense Logistics Management Standards (DLMS) are converging to make traceability, transformability, and contractual compliance non-negotiable. Buyers must select solutions that map directly to these frameworks.
-
Program-level modernization: Programs such as the Next-Generation AOC Weapon System and other service modernization efforts are placing a premium on data fusion, AI readiness, and lifecycle visibility—attributes that increasingly determine platform eligibility for major sustainment contracts.
-
Vendor innovation cadence: Large platform vendors and niche specialists alike are announcing AI, cloud, and interoperability enhancements—moves that force procurement teams to balance lock-in risk against short-term capability gains.
Competitive Landscape — Leaders, Integrators, and Specialists
The market structure is characterized by a mix of global enterprise software providers, defense primes that bundle asset management into broader sustainment offerings, and specialist vendors who focus on defense-grade functionality and regulatory conformity. Market concentration metrics indicate a moderately consolidated field—top incumbents hold meaningful share but there remains room for specialist vendors and challengers.
-
Platform incumbents (enterprise suites): IBM, SAP, Oracle and Dassault Systèmes deliver broad lifecycle management platforms that are often chosen for cross-domain deployments and deep ERP/PLM integrations. These solutions emphasize enterprise governance, integration, and a pathway to predictive maintenance at scale.
-
Defense primes and systems integrators: Lockheed Martin, Northrop Grumman and similar primes integrate asset management modules into sustainment contracts and platforms, offering end-to-end logistics, MRO and lifecycle services—often with strong alignment to government procurement models.
-
Best-of-breed and specialized vendors: Vendors such as IFS, AssetWorks, Prometheus Group, Ramco, Hexagon, CGI, Infor, and eQuip offer niche functionality tailored to fleet management, complex inventory flows, and DoD contractual compliance. Their strengths include rapid configuration, domain-specific workflows, and hands-on support models.
Recent vendor moves reinforce this mosaic: IBM announced AI-powered enhancements aimed at defense asset management in January 2026, Dassault Systèmes released notable platform updates in 2025, and program starts such as the US Air Force Kessel Run initiative are accelerating demand for interoperable, AI-ready solutions. These developments increase the importance of vendor roadmaps and their alignment to DoD modernization timing.
What the PW Consulting Report Delivers — Practical, Procurement-Ready Tools
Our report is structured to inform immediate 2026 decision cycles. Key deliverables include:
-
Executive brief and scenario-based market forecasts (including upside/downside cases and sensitivity to policy shifts).
-
Vendor profiles and comparative capability matrices covering enterprise suites, integrators, and specialists—highlighting security posture, SaaS ATO readiness, API ecosystems, and implementation footprints.
-
Compliance mapping: explicit checklists that map CMMC 2.0, DLMS, DCMA Manual 4401-17 and DoD SaaS ATO requirements to functional and technical controls.
-
Procurement playbook: RFP templates, scoring rubrics, procurement negotiation playbooks (enterprise licensing and FinOps clauses), and recommended contractual language for sustainability and data portability.
-
Implementation toolkit: 100-day deployment roadmaps, data-migration templates, integration patterns for ERP/PLM/MRO systems, and workforce-training plans that specifically address clearance and domain expertise constraints.
-
TCO and ROI models that surface the hidden costs (specialized labor, compliance remediation, data transformation) and the measurable benefits (reduced downtime, parts optimization, readiness improvements).
-
Strategic options analysis: build vs buy vs partner frameworks and an M&A watchlist for buyers seeking inorganic growth or consolidation targets.
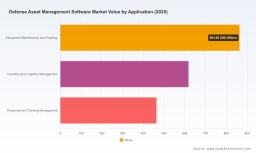
Note: Detailed regional and application-level breakouts, vendor scorecards, and price benchmarking samples are intentionally excluded from this release—these are contained in the full report and interactive data workbook.
Operational Realities and Cost Drivers
Two operational realities should shape 2026 plans:
-
Human capital is a primary cost and risk vector. Specialized labor—engineers with clearance, integrations specialists, and sustainment planners—remain the largest line item in implementation budgets. Reducing manual overhead through automation and standardized data schemas is therefore a high-return investment.
-
Compliance complexity creates both friction and opportunity. Systems that can natively output compliance evidence, transform legacy DLMS-constrained datasets, and align to DCMA software license tracking requirements materially shorten procurement-to-deploy timelines.
Actionable Recommendations for 2026 Decision-Makers
-
Prioritize SaaS ATO-ready vendors and insist on an enterprise licensing pathway that supports service-wide scaling and predictable FinOps outcomes.
-
Require a compliance mapping exercise as a pre-contract deliverable—every shortlisted vendor should demonstrate how their solution meets CMMC 2.0, DLMS, and DCMA requirements.
-
Negotiate phased delivery tied to capability milestones (data migration, interoperability tests, and compliance artifacts) to reduce implementation risk and align payments to outcomes.
-
Invest in an internal “integration center of excellence” to retain institutional knowledge, accelerate future platform rollouts, and reduce reliance on external labor.
-
Use modular, API-first architectures to preserve optionality—this reduces lock-in and allows substitution of best-of-breed modules as technologies evolve.
Conclusion — Strategic Value of the Report for 2026
For defense organizations and their contractor ecosystems, 2026 is the year to move from pilot projects to scaled sustainment and logistics modernization. Our research quantifies the opportunity and provides the practical implements—templates, compliance mappings, vendor assessments, and financial models—required to make informed procurement choices under contemporary DoD mandates.
PW Consulting’s Defense Asset Management Software Market report is designed to support tactical procurement decisions and long-term strategy alike. For teams preparing RFPs, negotiating enterprise licensing, or planning multi-year sustainment strategies, the full report supplies the missing data and vendor intelligence necessary to act with confidence. To access the complete market breakdowns, vendor scorecards, and downloadable implementation toolkits, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Defense Asset Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com