

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CPE Antenna Market Poised to Reach USD 2,755.6 Million by 2032, Growing at an 8.27% CAGR

Cpe Antenna Market 2026: Strategic Playbook for Operators, OEMs, and Investors
As PW Consulting’s senior strategic advisor and industry lead, I present an executive briefing distilled from our latest Cpe Antenna Market research. This is a “trailer” — designed to demonstrate the analytical depth and practical value of the full report while preserving the proprietary granularity that drives decisions. Read on to understand why the CPE antenna opportunity should be central to your 2026 strategy, what market forces will shape supplier selection, and which actions reliably separate successful deployments from stalled projects.
Cpe Antenna Market
Why CPE Antennas Matter for 2026 Choices
The CPE antenna sector is no longer a component-level afterthought: it sits at the intersection of spectrum strategy, network economics, and end-user experience. Our modelling shows the global market (measured in USD, revenue terms) reached approximately $1.58 billion in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 8.27% across the 2026–2032 horizon. By 2032 the market is projected to be meaningfully larger, reflecting continued investment in fixed wireless access (FWA), next-generation home gateways, and satellite-access terminals.
Cpe Antenna Market
For 2026 decision-makers, this trajectory is actionable. A suboptimal antenna choice amplifies CAPEX and OPEX downstream: fewer satisfied subscribers, higher truck rolls, and muted performance gains from upgraded radio layers. Conversely, an optimized CPE antenna strategy can extend base-station reach, reduce site density requirements, and unlock higher ARPU segments via premium low-latency and high-throughput services.
Cpe Antenna Market
What the Full Report Delivers (Operational, Purchase-Ready)
- Market sizing and scenario models that translate macro forecasts into region- and application-level demand curves (scenario-driven, with downside, base, and upside outcomes).
- Technology readiness and TRL-aligned assessments for integrated vs external high-gain solutions, including maturity timelines for AI-assisted beamforming and wideband multi-band designs.
- Supplier benchmarking and competitive scorecards built on technical performance, manufacturability, supply-chain resilience, and aftermarket support.
- Deployment playbooks: field-test protocols, RF acceptance criteria, integration checklists for gateway vendors, and KPIs for retailers and operators.
- Regulatory impact matrices mapping likely spectrum reallocation and policy shifts into practical procurement and rollout contingencies.
- Commercial models and TCO templates that convert antenna-level choices into five-year ROI projections for operators and gateway OEMs.
Each deliverable includes templates, sample test data, and decision heuristics so teams can move from analysis to RFPs, lab tests, and live trials within quarters — not years.
Market Dynamics Shaping 2026 Tactics
- Spectrum policy volatility: Recent regulatory activity in major markets has sharpened the strategic value of mid-band capacity and raised the stakes for antenna performance. Proposed repurposing of certain upper C-band blocks and broader federal directives to identify additional commercial spectrum are likely to accelerate mid-band FWA opportunities; at the same time, legal and policy reversals have increased compliance and planning complexity for cross-border rollouts.
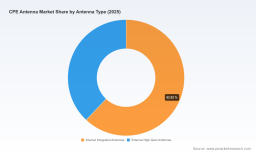
- Technology consolidation: The industry is converging on two enduring technical paths — highly integrated indoor multi-element antennas designed for dense urban FWA and robust external high-gain enclosures for long-reach and rural bridges. AI-enhanced antenna control (beam tracking, adaptive beamforming) is moving from premium R&D to commercial product roadmaps.
- Channel and OEM dynamics: Design wins for embedded high-performance gateway antennas (particularly for next-generation Wi-Fi and fiber gateway hybrids) are the new currency of long-term supplier relationships. OEMs seek partners who can co-design, validate in anechoic chambers, and support rapid firmware-driven tuning.
- Moderate industrial concentration: The supplier landscape is neither atomized nor monopolistic. A group of global and regional specialists command significant influence through proprietary antenna systems, field-proven enclosures, and scale manufacturing — creating opportunities for selective partnerships and risk-sharing across the value chain.
Competitive Overview — What to Watch From Key Players
- Vantiva (France) — Differentiator: a proprietary Indoor5G™ multi-Rx architecture with patented mid-band boosters targeting high-density FWA indoors. Strategic implication: compelling partner for operators seeking short- to mid-term performance uplift without additional site density.
- ZTE Corporation (China) — Differentiator: aggressive integration of AI-driven antenna solutions across indoor and outdoor FWA CPEs, coupled with mmWave-capable outdoor designs. Strategic implication: strong contender for large-scale operator rollouts where bundled CPE+service offerings are prioritized.
- Poynting (South Africa) — Differentiator: ruggedized outdoor enclosures and wideband coverage with IP-rated designs suited for challenging rural and industrial environments. Strategic implication: preferred for long-reach, weather-exposed deployments where durability reduces OPEX.
- TP-Link, Huawei, and regional OEMs — Differentiator: broad channel reach and cost-effective directional and omni solutions for ISP and SMB segments. Strategic implication: valuable when cost-per-subscriber is the dominant constraint and rapid scale matters.
- Specialist component suppliers (Airgain, VLG Tech, Antenna Products, select Shenzhen OEMs) — Differentiator: embedded antenna technology, anechoic testing, and modular designs that accelerate gateway vendor time-to-market. Strategic implication: look to these partners for co-engineered, high-performance gateway solutions and to secure design wins early in product cycles.
Recent market moves illustrate the dynamic. In early 2026 Vantiva and ZTE each announced next-generation FWA CPE platforms emphasizing multi-Rx and AI-assisted antenna systems. Separately, an embedded antenna supplier secured a multi-year design win for next-gen fiber gateways with Wi‑Fi 7 antennas, validating the commercial runway for high-performance embedded solutions.
Strategic Recommendations for 2026 Execution
Operators, OEMs, and investors should treat CPE antenna strategy as a lever for both top-line growth and cost optimization. Our recommended playbook for calendar 2026 comprises immediate, near-term, and tactical moves:
- 0–90 days (priorities): Map your service-product mix to antenna-class requirements — identify which subscriber cohorts require integrated indoor solutions versus rugged external CPE. Run a rapid supplier-screen using performance, supply risk, and lifecycle support criteria from our scorecards.
- 90–180 days (validation): Execute co-engineering pilots with two suppliers (one integrated indoor specialist, one external high-gain expert). Use the report’s field-test protocol and acceptance KPIs to compare real-world throughput, latency, and installation OPEX.
- 180–360 days (scale): Convert successful pilots into staged rollouts with clear upgrade paths. Negotiate design-win protections, service-level agreements tied to in-field KPIs, and options for firmware-driven antenna tuning linked to OSS/BSS telemetry.
- Ongoing (regulatory & sourcing): Maintain an active spectrum-policy dashboard and create contingency procurement lanes — one optimized for rapid mid-band ramp-ups and another for long-range rural deployments. Integrate regulatory scenarios into procurement triggers so supplier selection and inventory planning reflect likely auction outcomes and repurposing timelines.
Risks & Mitigations
- Regulatory churn: Risk: sudden shifts in spectrum availability or national classification of broadband services. Mitigation: scenario-based procurement clauses and spectrum-flexible antenna designs.
- Integration delays: Risk: gateway–antenna co-design mismatches. Mitigation: mandate anechoic chamber validation and provide suppliers with early access to firmware/firmware APIs.
- Supply concentration: Risk: reliance on a small set of suppliers for critical components. Mitigation: dual-sourcing and qualified second-tier suppliers with ramp certs documented in the report’s scorecards.
Conclusion — Where Value Will Be Captured in 2026
As the CPE antenna market grows from the $1.6 billion scale in 2025 and continues on an 8.27% CAGR, the winners in 2026 will be organizations that treat antenna selection as strategic rather than tactical. This means embedding antenna metrics into procurement, aligning them with spectrum strategy, and accelerating co-engineering tracks that shorten lab-to-field cycles.
PW Consulting’s full Cpe Antenna Market report delivers the granular market mappings, supplier scorecards, and executable playbooks required to operationalize these recommendations. For teams preparing 2026 capital plans, vendor RFPs, or rollout roadmaps, the report is designed to convert insight into measurable outcomes — with templates, test protocols, and negotiation playbooks that reduce time-to-decision.
To access the complete analysis, proprietary segmentation tables, and vendor scorecards, please visit our official report page for the Cpe Antenna Market. The full report contains the detailed data and appendices necessary to populate procurement models and investment memos.
For detailed analysis of this topic, please visit the official page: Cpe Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com